
Advanced Glass Market Report Scope and Overview
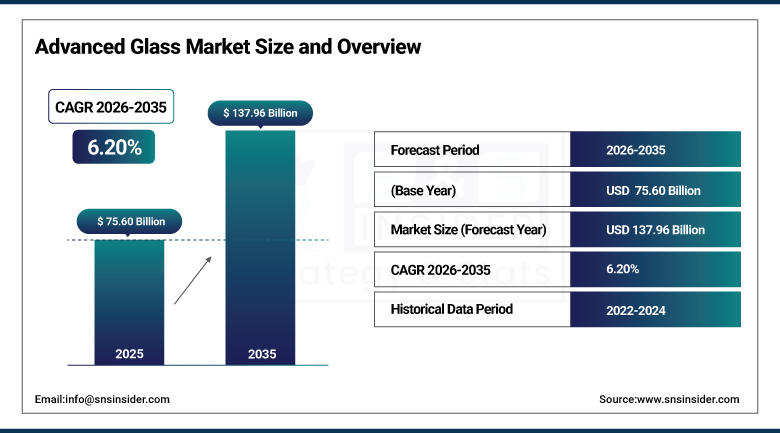
The Advanced Glass Market was valued at USD 75.60 Billion in 2025 and is estimated at USD 80.29 Billion in 2026. The market is forecast to reach USD 137.96 Billion by 2035, registering a CAGR of 6.20% from 2026 to 2035. Growth reflects rising use of safety, energy-saving, and high-performance glass in buildings, vehicles, electronics, and solar modules. The scope covers revenue from tempered, laminated, coated, smart, and other engineered flat glass products, and excludes container and fiber glass. Processed products sold as glazing units, laminated panels, and coated sheets are counted, while raw float glass sold without further processing is not.
To Get more information On Advanced Glass Market - Request Free Sample Report
Key Market Trends & Insights
-
By product: Tempered glass held the largest market share of 40.70% in 2025.
-
By application: Safety and security held the largest market share of 41.30% in 2025.
-
By end use: Building and construction held the largest market share of 43.50% in 2025.
-
Asia Pacific accounted for the largest regional share of 40.20% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 7.30% from 2026 to 2035.
-
The U.S. is the leading country market in North America, supported by large commercial construction activity, vehicle production, and growing demand for energy-efficient windows.
Growth Outlook
Building energy rules in Europe are raising the specification of glazing. In May 2024, the revised Energy Performance of Buildings Directive entered into force, with member states required to transpose it within two years, and it makes zero-emission buildings the standard for new construction while introducing life-cycle emissions reporting from 2028. Architects and developers respond with triple glazing, solar control coatings, and laminated units that reduce heating and cooling loads, which lifts the typical value of glass per building. Several national building codes already require stricter glazing.
Window efficiency standards are also tightening in the United States. In October 2023, the Environmental Protection Agency's ENERGY STAR Version 7.0 specification for residential windows, doors, and skylights took effect, with stricter U-factor limits for northern climate zones that favor low-emissivity coatings and multiple panes. Manufacturers of insulating glass units and coated glass supply the upgraded products, and renovation programs for older homes add further demand. Public agencies also fund replacement programs for older homes, which adds further demand for upgraded windows.
Market Dynamics
Driver: Energy-Saving Buildings, Vehicle Glazing, and Electronics Demand Support the Market
New uses in electronics are widening the range of advanced glass products. In May 2024, the U.S. Department of Commerce announced preliminary terms for an award of up to USD 75.00 Million under the CHIPS program for a glass substrate plant in Georgia, which would make panels used in advanced semiconductor packaging. Glass offers flatness, low expansion, and fine wiring density that organic materials cannot match, and chip makers are testing such substrates for artificial intelligence processors. Equipment makers and glass producers are also investing in laser drilling and metal filling for such panels, and early shipments of samples are going to leading chip designers. Large public funding rounds support this shift.
Buildings and vehicles remain the largest sources of demand. Developers specify laminated and coated glass for safety, noise reduction, and energy savings, while carmakers use larger windshields, panoramic roofs, head-up display glass, and acoustic laminates in more models. Electric vehicles use glass to cut weight and improve comfort, and sensors for driver assistance require clear optical paths through the windshield. Smartphone, tablet, and display makers also buy large volumes of strengthened cover glass, and solar module makers use glass on both sides of bifacial panels. Rising incomes in Asia and the Middle East also lift demand for premium glazing in housing and offices.
Restraint: Energy Costs, Tax Credit Changes, and Carbon Rules Limit Growth
Support for energy-efficient construction in the United States is being reduced. In July 2025, the U.S. Congress ended the residential energy efficient home improvement credit and the commercial building deduction at the end of 2026, and added foreign-entity restrictions to the advanced manufacturing production credit. Homeowners and building owners may bring forward projects before the deadline, and demand for upgraded windows could weaken afterward, while manufacturers face changed conditions for planning investments. Smaller window makers and installers are also exposed to interest rates and housing cycles, and some producers have delayed investments in coating lines. Uncertain rules on eligible products complicate marketing plans for new high-performance windows.
The costs of production and carbon regulations impact the producers. The float glass furnaces use huge quantities of natural gas and work continuously, thus changes in the price of energy will impact their profitability significantly. In January 2026, the definitive period of the European Carbon Border Adjustment Mechanism started. Although the glass industry is currently excluded from the list, the sector stays within the scope of the emissions trading scheme with a very high carbon leakage risk score. The industry organizations are lobbying on behalf of the free allocation and possible future extension, and the price of low-carbon glass melting technology is high. The transport costs of the large glass panels and the risks of damage during transport prevent international trade.
Opportunity: Safety Standards, Glass Substrates, and Smart Glazing Create New Revenue
Quality rules in fast-growing markets favor certified safety glass. In March 2023, India notified a Safety Glass Quality Control Order covering glass used in buildings and road vehicles, which requires producers and importers to hold licences from the Bureau of Indian Standards once it is in force. Such orders raise barriers against uncertified imports, and established manufacturers with testing facilities can gain share as enforcement widens across construction and transport. Producers that obtain certification and local approvals early, and that train distributors and installers in compliant products, are better placed to benefit from the shift toward certified supply in India and other emerging markets over the coming years.
Technology offers further openings. Electrochromic, suspended particle, and liquid crystal glazing allows windows to change tint on demand, which reduces air conditioning loads and glare in offices, aircraft, and vehicles. Glass cores and interposers for chip packaging, augmented reality waveguides, and ultra-thin foldable cover glass are emerging products with high margins. Suppliers that combine coating, laminating, and forming skills can capture these new uses as they scale. Data centers, solar farms, and electric vehicles are also adding demand for engineered glass with special optical and thermal properties, and partnerships between glass makers and device makers shorten qualification times. Pilot lines are already running.
Market Characteristics & Concentration
The Advanced Glass Market is Moderately Consolidated. A small group of global flat glass producers and specialty glass makers supplies most of the revenue, while regional processors, tempering and laminating shops, and smart glass specialists serve local buyers. Competition rests on coating technology, energy efficiency, optical quality, scale, and long-term relationships with builders and carmakers. Float line capacity is costly and runs continuously for years, which limits entry by new producers and favors firms that can secure sand, soda ash, and energy.
Specialty and flat glass producers occupy different parts of the field. Display and electronics glass makers focus on ultra-thin and strengthened products, flat glass groups on architectural and automotive glazing, and start-ups on smart and switchable glass. Many glass makers have been divesting weaker lines, and some smart glass firms have restructured or gone through bankruptcy protection. Processors that temper, laminate, and assemble units close to customers also play a significant role.
Ownership changes are also reshaping the field. In March 2026, a leading Japanese flat glass group announced a recapitalization with a private equity investor that includes a debt-to-equity swap and a plan to delist from the stock exchange. Other groups have sold distribution businesses or exited lower-margin specialty lines to concentrate capital on products with higher growth. Joint ventures with regional partners are also common. Buyers also expect long product warranties and consistent supply across global projects.
Analyst Perspective
The advanced glass market is driven by regulations related to energy in buildings, safety in vehicles, and new applications in electronics and solar panels. The tempered glass accounts for the majority of revenue generated, whereas smart glazing and coated glass are experiencing higher growth rates from a lower base. Energy prices, changes in tax policies, and carbon regulations impact profit margins; therefore, producers with efficient furnaces, advanced coating technologies, and diversified customer segments are positioned much better than commodity producers. An SNS Insider Analyst, Santosh Bhul, stated, “The producers of coated and laminated glass that have low-carbon production and new applications in electronics will experience higher growth rates than the overall market, and Asia Pacific will experience the fastest growth rate until 2035.”
Segment Analysis
Product Insights
Tempered glass held the largest share of 40.70% in 2025. Heat treatment makes the glass several times stronger than annealed glass and causes it to break into small blunt pieces, which suits building facades, doors, shower enclosures, side and rear vehicle windows, and appliances. Processing lines are widely available, and architects specify it where safety rules apply. Volumes follow construction and vehicle output. Producers also add heat soaking and edge treatments that reduce spontaneous breakage in large facade panels, and thinner tempered products help carmakers and appliance makers lower weight.
Smart glass is expected to be the fastest-growing segment with a CAGR of 9.30% during 2026-2035. Electrochromic, suspended particles, and polymer-dispersed liquid crystal smart glass can adjust tint at will, which helps save energy and provides privacy in offices, airplanes, automobiles, and hospitals. Laminated and coated and low emissivity smart glasses add to the bulk of the market, while specialty glass finds applications in optics and electronics. Reduction in costs has been achieved as the film and coating manufacturers increase production. Installation in airport terminals, hospitals, and executive offices raises awareness among architects and facility managers.
Application Insights
Safety and security held the largest share of 41.30% in 2025. Building codes and vehicle standards require tempered or laminated glazing in doors, windows, and windshields, and laminated products also resist forced entry, blasts, and storms. Banks, schools, airports, and government buildings specify them, and insurers favor safer glazing in hurricane and earthquake zones. Sound insulation and ultraviolet filtering are further benefits that make laminated glass a preferred option in urban housing near roads and airports, while thin laminated products reduce weight in vehicles. Certification marks reassure specifiers and insurers.
Solar control is expected to expand at the fastest CAGR of 8.20% from 2026 to 2035. Coatings that reflect infrared heat while allowing daylight help buildings reduce cooling energy, and demand grows with hotter climates and stricter codes. Optics and lighting, and high-performance uses such as aerospace canopies and display covers, add further demand. Spectrally selective coatings that transmit visible light but block heat are replacing tinted glass in many commercial projects, and suppliers also offer coatings that reduce reflection from facades into neighboring buildings. Energy codes in hot regions favor such coatings.
End Use Insights
Building and construction held the largest share of 43.50% in 2025. Facades, windows, curtain walls, skylights, and interior partitions use large volumes of tempered, laminated, and coated glass. Energy codes drive the shift to insulating units with coatings and gas fills, and renovation of older buildings adds replacement demand. Commercial towers and large public buildings use the most advanced products. Developers also use fire-rated and acoustic glass in towers, hospitals, and schools, and prefabricated facade systems built in factories raise the share of advanced glass per project in the region.
Electronics is projected to grow at the fastest CAGR of 9.80% from 2026 to 2035. Strengthened cover glass for phones, tablets, laptops, and wearables, glass for displays and augmented reality optics, and glass substrates for chip packaging all raise demand, and values per unit are high. Automotive, solar, and aerospace and defense add large and steady demand. Solar module makers buy low-iron patterned glass in very large volumes, and aircraft and defense programs use laminated canopies, display covers, and transparent armor that command premium prices. Qualification cycles can be long.
Regional Insights
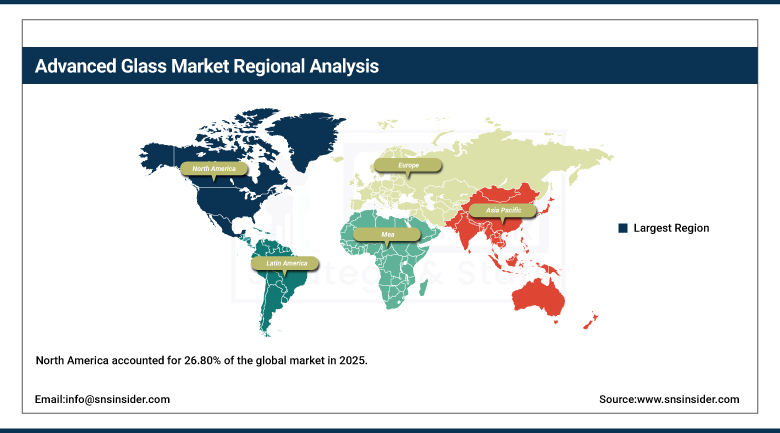
North America accounted for 26.80% of the global market in 2025. The region has large commercial construction and renovation activity, strong vehicle and aerospace production, and rising use of energy-efficient windows. Glass makers operate float lines and coating plants across the United States and Canada, while makers of smart glass and glass substrates are expanding. Canada adds demand through commercial building and vehicle assembly. Utilities and building owners also run programs that pay for window upgrades.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. Advanced Glass Market
The U.S. market was valued at USD 17.22 Billion in 2025 and is expected to register a CAGR of 5.80% from 2026 to 2035. Demand is led by commercial and residential construction, vehicle assembly, and aerospace programs, with growing use of coated windows and laminated safety glass. Float glass and coating plants operate in Ohio, Pennsylvania, Texas, and North Carolina, and glass substrate and display glass makers are adding capacity. Universities and national laboratories also work on smart coatings and glass substrates, and federal programs support related manufacturing.
The consumers consider price, energy efficiency, safety ratings, and timing of delivery. The fluctuations in the federal tax rebates for energy-efficient windows and commercial buildings create uncertainties, while the state-level energy standards and renovation programs increase the demand. The manufacturers develop coating and laminating facilities, and most fabricators cater to the local construction and glazing companies that need immediate services. Big glaziers and curtain wall contractors take up the big projects, and automobile manufacturers get their supplies of windshields and side glass through nearby plants, and distributors keep stocks of standard-sized glass for the residential builders.
Europe Advanced Glass Market
The European region had a share of 23.60% of the global advanced glass market in 2025. The biggest national markets of Europe include Germany, France, Italy, the UK, and Poland. The strict building energy regulations, high production of vehicles, and the presence of specialty glass manufacturers drive the demand, and the manufacturers invest in low-carbon furnaces and recycled glass production. The triple glazing and solar control coatings have wide applications in the construction of new buildings. The renovations of old buildings increase the demand for insulating glass units.
Asia Pacific Advanced Glass Market
Asia Pacific accounted for 40.20% of the market in 2025 and is anticipated to register the fastest regional CAGR of 7.30% from 2026 to 2035. China is the largest producer and user, followed by Japan, South Korea, India, and Southeast Asia, supported by large construction, vehicle, display, and solar module industries. Japan and South Korea lead in display and electronics glass, while India is adding capacity under quality control rules. Government programs also encourage investment in float lines, coating plants, and glass substrates.
Latin America Advanced Glass Market
Latin America accounted for 4.80% of the market in 2025, with Brazil as the leading country market followed by Mexico, Argentina, and Chile. Demand comes from commercial construction, vehicle assembly, and housing, and local float glass plants supply much of the flat glass. Imports serve specialty coated, laminated, and smart products, and Mexico is a large source of automotive glazing for export. Growth should follow wider use of energy-saving windows in commercial buildings and expansion of vehicle output over the forecast period.
Middle East & Africa Advanced Glass Market
Middle East & Africa accounted for 4.60% of the market in 2025, with Saudi Arabia, the United Arab Emirates, Turkey, Egypt, and South Africa as the main country markets. Large commercial towers, airports, and giga-projects in Gulf countries use solar control and laminated glass, and heat favors coated products. Turkey and Egypt produce flat glass, while many African markets depend on imports. Cooling costs and solar control standards are likely to raise demand over the forecast period.
Key Advanced Glass Market Company Insights
Companies in the advanced glass market are focusing on low-carbon production, coated and laminated glazing, display and glass substrate products for electronics, and portfolio reshaping toward higher-growth uses. Specialty glass makers and flat glass groups compete and cooperate across construction, vehicle, and technology markets.
Key Advanced Glass Companies:
-
Corning
-
AGC
-
Saint-Gobain
-
NSG
-
Schott
-
Nippon Electric Glass
-
Guardian Glass
-
Vitro
-
Fuyao Glass
-
Xinyi Glass
-
CSG Holding
Recent Developments
-
In September 2026, Gauzy received final approval from an Israeli court for a USD 61.00 Million settlement of legacy debt as part of its restructuring.
-
In July 2026, Saint-Gobain agreed to acquire a glass fiber plant in Lexington, North Carolina, with closing expected at the end of the month.
-
In May 2026, Corning upgraded and extended its Springboard plan to target annualized sales of USD 40.00 Billion by the end of 2030.
-
In March 2026, NSG announced a recapitalization with funds managed by Apollo, including a debt-to-equity swap and a plan to delist from the stock exchange.
-
In January 2026, Schott reported results for its 2024 and 2025 fiscal year and said serial production of augmented reality waveguide glass was under way in Malaysia.
-
In December 2025, AGC announced its exit from chemically strengthened specialty glass, with production at its Takasago plant to end by the third quarter of 2026.
Scope and Research Methodology
This report defines the advanced glass market as the revenue generated by engineered flat glass products that provide enhanced strength, safety, thermal, optical, or electronic performance, including tempered, laminated, coated and low-emissivity, smart, and specialty glass. Coverage includes building and construction, automotive, electronics, solar, aerospace and defense, and other end uses. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Container glass, glass fiber, and ordinary annealed float glass sold without further processing are outside the scope. Mirrors, decorative glass, and glass used only as a container material are excluded from the market definition.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, glass technologists, procurement managers, and other stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test the direction of demand in each region and application before any figure is finalized for the study. Every interview follows a structured guide so that responses are comparable across respondents and regions, and findings are logged against the assumptions they affect.
Market engineering follows a bottom-up build from float glass output, processing capacity, price bands by product, and supplier revenue, cross-checked top-down against construction activity, vehicle production, and electronics shipments. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate the drivers that shape demand, including regulation, technology maturity, and macroeconomic conditions. Senior analysts review every estimate, assumption, and narrative section for consistency before release, and figures are checked against the segment and regional totals so that the final model remains internally coherent. Where inputs differ, analysts revisit the underlying assumptions with sector experts and adjust the model only when the evidence supports a change, so that the published figures stay traceable to documented inputs.
Advanced Glass Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 75.60 Billion |
| Market Size by 2035 | USD 137.96 Billion |
| CAGR | CAGR of 6.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Tempered, Laminated, Coated and Low-E, Smart, and Others) • By Application (Safety and Security, Solar Control, Optics and Lighting, High Performance, and Others) • By End Use (Building and Construction, Automotive, Electronics, Solar, Aerospace and Defense, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Corning, AGC, Saint-Gobain, NSG, Schott, Nippon Electric Glass, Guardian Glass, Vitro, Fuyao Glass, Xinyi Glass, CSG Holding |

Frequently Asked Questions
The market was valued at USD 75.60 Billion in 2025 and is projected to reach USD 137.96 Billion by 2035.
The market is expected to register a CAGR of 6.20% from 2026 to 2035.
Asia Pacific led the market with a 40.20% share in 2025.
Tempered glass led the product segment with a 40.70% share in 2025, and safety and security led the application segment.
Key players include Corning, AGC, Saint-Gobain, NSG, and Schott.
