
Aerosol Propellant Market Report Scope & Overview:
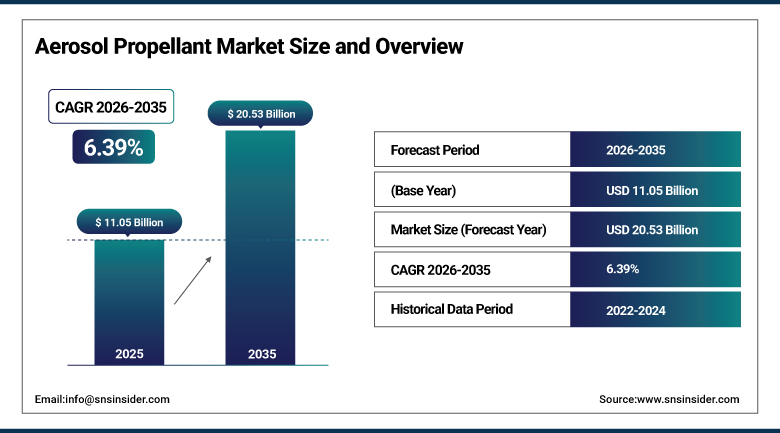
The Aerosol Propellant Market was valued at USD 11.05 Billion in 2025 and is expected to reach USD 20.53 Billion by 2035, growing at a CAGR of 6.39% from 2026-2035.
Aerosol propellants are the pressurised gases that expel the contents of an aerosol can, spanning hydrocarbons such as propane, isobutane, and butane, dimethyl ether, compressed gases such as nitrous oxide and carbon dioxide, and hydrofluorocarbon or hydrofluoroolefin blends. They serve deodorants, hair sprays, dry shampoos, insecticides, air fresheners, cleaning products, paints, and metered-dose inhalers. Demand tracks personal care and household consumption, rising disposable income, and growing use of convenient, easy-to-apply spray formats. Regulation is reshaping the competitive landscape, as tightening rules on high global-warming-potential gases push formulators toward hydrocarbons, dimethyl ether, and next-generation low-GWP hydrofluoroolefins. Suppliers are investing in capacity for these compliant molecules while continuing to serve mature hydrocarbon-based demand.
Effective January 1, 2025, the U.S. Environmental Protection Agency confirmed restrictions on higher global-warming-potential hydrofluorocarbons in aerosol products under the AIM Act. The rule accelerates the shift among consumer goods and pharmaceutical formulators toward low-GWP alternatives such as hydrofluoroolefins and compressed gases.
To Get more information Aerosol Propellant Market - Request Free Sample Report
Aerosol Propellant Market Trends
-
Rising reformulation toward low-GWP hydrofluoroolefins as HFC quotas tighten in major markets.
-
Growing adoption of dimethyl ether for its low toxicity and water miscibility in spray formulations.
-
Expanding use of compressed gas propellants in premium personal care and eco-labelled products.
-
Increasing capacity investment by fluorochemical producers in pharmaceutical-grade HFO propellants.
-
Rising demand for aerosol-based products in fast-growing Asia Pacific personal care and household markets.
-
Growing supplier collaboration with pharmaceutical companies on metered-dose inhaler reformulation.
U.S. Aerosol Propellant Market Overview
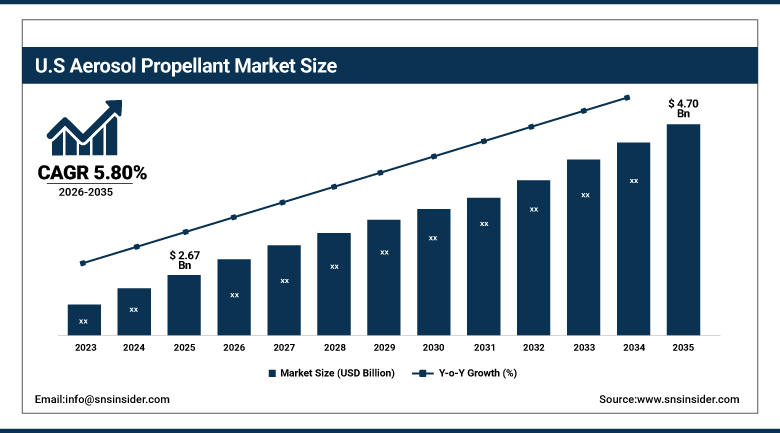
The U.S. Aerosol Propellant Market was valued at USD 2.67 Billion in 2025 and is expected to reach USD 4.70 Billion by 2035, growing at a CAGR of 5.80% from 2026-2035.
The United States Aerosol Propellant Market is influenced by government regulations on the AIM Act, which reduces the use of high-GWP hydrofluorocarbons and drives the industry toward compliance with other options. The personal care, household, and pharmaceutical companies represent the major proportion of the national market, and the reformulation of the metered-dose inhalers is gaining momentum as an important but gradually developing demand generator as manufacturers should prove bioequivalence before changing propellants. The sources of qualified low-GWP molecules are limited to only a few fluorochemical producers, resulting in duopolistic market of hydrofluoro-olefin propellants that might influence pricing and availability. Hydrocarbon propellants dominate the consumer goods sector due to their low price and well-developed supply chain.
In May 2025, Honeywell partnered with Lupin to develop inhalers using its Solstice Air HFO-1234ze(E) propellant, tying the company directly to the pharmaceutical reformulation cycle driven by the AIM Act phasedown.
Aerosol Propellant Market Segment Analysis
-
By Product Type, the Hydrocarbons segment dominated the market with a 46.30% share in 2025, while the Dimethyl Ether segment is the fastest growing with a CAGR of 8.70% during 2026-2035.
-
By Formulation, the Solvent-Based segment dominated the market with a 58.40% share in 2025, while the Water-Based segment is the fastest growing with a CAGR of 7.80% during 2026-2035.
-
By Application, the Personal Care & Cosmetics segment dominated the market with a 44.60% share in 2025, while the Household segment is the fastest growing with a CAGR of 7.70% during 2026-2035.
-
By Packaging, the Standard Aerosol Cans segment dominated the market with a 82.60% share in 2025, while the Bag-on-Valve segment is the fastest growing with a CAGR of 8.40% during 2026-2035.
By Product Type, Hydrocarbons Dominates the Market and Dimethyl Ether Grows Fastest
Hydrocarbons dominated the market in 2025. The propellants propane, isobutane, and butane are relatively cheap, abundant, and versatile with respect to their compatibility with consumer and industrial products and formulations, which makes them the preferred option in both personal care and household aerosols. Dimethyl ether, on the other hand, is predicted to exhibit the highest growth rate in the market during the forecast period.
Dimethyl ether is projected to be the fastest-growing product type over the forecast period. Dimethyl ether is highly soluble, stable chemically, non-toxic, and miscible in water, and these properties render it suitable for applications in paints and hair sprays in which hydrocarbons are not very effective. Formulators are increasingly looking for propellants that are safe and versatile with respect to functionality.
By Formulation, Solvent-Based Dominates the Market and Water-Based Grows Fastest
Solvent-based formulations dominated the market in 2025. They deliver strong performance for oil-based actives, fragrances, and coatings, and they remain the standard choice across many personal care and household aerosol categories where fast drying and even spray patterns are required. Established manufacturing processes and broad regulatory acceptance keep solvent-based systems in front.
Water-based formulations are expected to be the fastest-growing category over the forecast period. Rising consumer and regulatory preference for lower volatile organic compound content is pushing formulators toward water-based systems, particularly in personal care and household cleaning products marketed on environmental credentials. Continued improvement in propellant compatibility with water-based actives is widening the range of products that can adopt this formulation.
By Application, Personal Care & Cosmetics Dominates the Market and Household Grows Fastest
Personal care and cosmetics dominated the market in 2025. Deodorants, hair sprays, hair mousse, dry shampoos, and body sprays are produced in enormous volumes worldwide, and rising disposable income and a growing middle class continue to expand this consumer base. Frequent product launches and brand reformulation keep propellant demand steady within this application.
The household products segment is estimated to witness the highest growth rate during the forecast period. There will be an increase in disposable incomes, along with the increasing importance of aromatherapy and fragrances, that will benefit air fresheners, insecticides, and cleaning products. The increasing online sales channels will further drive their growth.
By Packaging, Standard Aerosol Cans Dominates the Market and Bag-on-Valve Grows Fastest
Standard aerosol cans dominated the market in 2025. This established packaging format is compatible with the overwhelming majority of propellant chemistries and filling lines, and its low cost and simplicity keep it the default choice across personal care, household, and industrial aerosol products worldwide.
Bag-on-valve packaging is expected to be the fastest-growing format over the forecast period. This design separates the product from the propellant, allowing 360-degree spraying, precise dosing, and compatibility with a wider range of active ingredients, including water-based and sensitive formulations. Growing use in premium personal care and pharmaceutical products is driving above-market growth for this packaging type.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Europe |
Germany |
27.60% |
|
North America |
United States |
90.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Aerosol Propellant Market Insights
North America holds a significant share of the global market, anchored by the United States, where regulation under the AIM Act is accelerating the transition toward low-GWP propellants. The region hosts several of the world's leading fluorochemical producers, giving it a central role in developing and supplying next-generation propellant chemistries.
Canada and Mexico add further regional demand through consumer goods and industrial manufacturing. Supply chain disruptions affecting the sourcing of ingredients and raw materials have created operational challenges in the United States in recent periods, though continued investment in domestic production capacity is expected to support steady regional growth through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Aerosol Propellant Market Insights
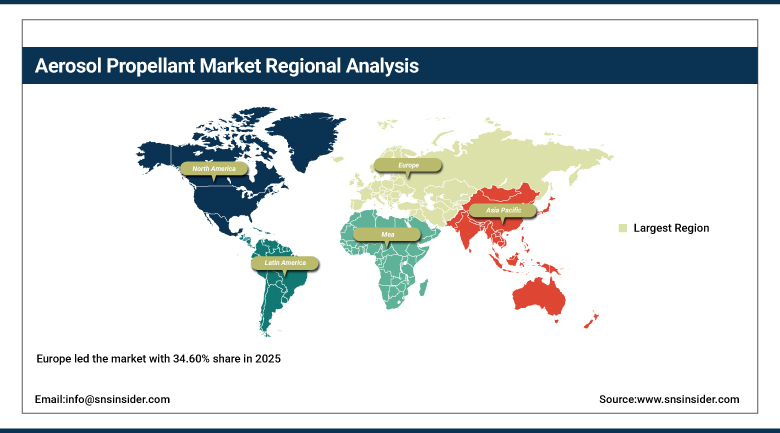
Europe led the market with 34.60% share in 2025. The strong demand for personal care, household, and medical products, along with the availability of fluorochemical and hydrocarbon propellant manufacturers in the region, is driving the leading market position of Europe. Pressure from regulations such as the EU F-Gas Regulation has also placed regional suppliers ahead in the race for low GWP propellants.
Germany is leading regional demand due to its robust personal care and industrial production facilities. Growth in Russia is projected to be especially high compared to other regions, whereas France, Italy, and the UK drive consistent demand from their consumer goods industry.
Asia Pacific Aerosol Propellant Market Insights
The Asia Pacific is anticipated to witness the highest growth at a CAGR of 8.20% from 2026 to 2035. The rising trend of urbanization, middle class population, industrialization, and increasing disposable income are some of the key factors that are contributing to the high consumption growth in the personal care and household aerosols segments.
China anchors regional demand through its large consumer goods manufacturing base and expanding domestic personal care industry. India contributes strong growth as household incomes rise and modern retail expands. Japan and South Korea add mature, technology-oriented demand, while government strategies supporting domestic manufacturing continue to broaden regional supply capacity.
MEA & Latin America Aerosol Propellant Market Insights
The Middle East & Africa region is supported by growing consumer goods manufacturing and rising personal care spending across the United Arab Emirates and Saudi Arabia. Regional governments are encouraging domestic manufacturing investment, which is gradually expanding local propellant demand.
Latin America is anchored by Brazil, where a sizeable consumer goods sector sustains steady propellant demand. Supply chain disruptions affecting ingredient sourcing have also created operational challenges in Brazil in recent periods. Mexico contributes further incremental growth as regional personal care and household product manufacturing continues to expand.
Growth Drivers: Personal Care Demand and Household Consumption
Rising utilisation of deodorants, hair sprays, hair mousse, dry shampoos, insecticides, air fresheners, and cleaning products stands as the primary growth driver. Economic growth, a growing middle-class population, and increasing per capita income continue to expand the consumer base for aerosol-based personal care and household products across both developed and emerging markets.
Growing significance of aromatherapy and home fragrance trends represents a second major driver, supported by rising disposable income that allows consumers to spend more on lifestyle and comfort products. Expanding e-commerce distribution continues to widen product availability and variety, reinforcing sustained propellant demand across personal care and household categories.
Restraints: Regulatory Pressure and Supply Chain Disruptions
Increased regulation over higher global warming potential propellants is a major constraint. The phasedown requirements of AIM Act in the U.S. and F-Gas Regulation in Europe necessitate the requalification of products with alternative formulations, causing expenses and complications, especially when used in pharmaceutical applications because of increased time required due to bioequivalence testing.
Disruptions in the supply chain are another constraint. The inability to source ingredients and raw materials from external sources has impacted the financial and operational performance of companies in some markets such as the United States, India, and Brazil; the reliance of companies on fewer suppliers of low GWP propellants increases their risk exposure.
Opportunities: Low-GWP Reformulation and Pharmaceutical Applications
The development of low-GWP hydrofluoroolefins and compressed gases presents a significant opportunity because companies looking to become certified environmentally friendly and in compliance are moving towards these propellants. Suppliers who have proven themselves capable of supplying reliable, qualified low-GWP molecules will be well placed to meet this growing premium demand.
Another potential opportunity is the reformulation of metered dose inhalers, where pharmaceutical manufacturers are looking to move away from their legacy HFC propellants. This long-term project provides a stable, specialty margin for the company able to produce pharmaceutical grade propellants and have the appropriate master files.
Recent Developments
-
2025: Honeywell completed the spin-off of its Advanced Materials business into Solstice Advanced Materials, focused on low-GWP propellants and fluorinated specialty materials.
-
2025: The Chemours Company reported that its low-GWP Opteon product line delivered more than 350 million tons of avoided carbon dioxide-equivalent emissions, supporting continued adoption of Opteon-branded propellants as EU and U.S. quota stepdowns advance.
Aerosol Propellant Companies are:
-
Honeywell International Inc.
-
The Chemours Company
-
Arkema S.A.
-
Nouryon Chemicals Holding B.V.
-
Shell plc
-
Diversified CPC International Inc.
-
National Gas Company
-
Aeropres Corporation
-
PureGas Inc.
-
Settala Gas S.r.l.
-
Linde plc
-
Air Products and Chemicals, Inc.
-
Daikin Industries, Ltd.
-
Gujarat Fluorochemicals Limited
-
A-Gas International Limited
-
BASF SE
-
Messer Group GmbH
-
Taiyo Nippon Sanso Corporation
Aerosol Propellant Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.05 Billion |
| Market Size by 2035 | USD 20.53 Billion |
| CAGR | CAGR of 6.39% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Hydrocarbons, Dimethyl Ether, Nitrous Oxide & Carbon Dioxide, HFC/HFO) • By Formulation (Solvent-Based, Water-Based) • By Application (Personal Care & Cosmetics, Household, Pharmaceutical, Automotive, Industrial, Others) • By Packaging (Standard Aerosol Cans, Bag-on-Valve, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., The Chemours Company, Arkema S.A., Nouryon Chemicals Holding B.V., Shell plc, SHV Energy N.V., Diversified CPC International Inc., National Gas Company, Aeropres Corporation, PureGas Inc., Settala Gas S.r.l., Linde plc, Air Products and Chemicals, Inc., Daikin Industries, Ltd., Solvay S.A., Gujarat Fluorochemicals Limited, A-Gas International Limited, BASF SE, Messer Group GmbH, Taiyo Nippon Sanso Corporation |
Frequently Asked Questions
Key players include Honeywell International Inc., The Chemours Company, Arkema S.A., Nouryon Chemicals Holding B.V., Shell plc, and Linde plc, among other chemical producers.
Continued reformulation toward low-GWP hydrofluoroolefins and compressed gases, and metered-dose inhaler reformulation, represent the primary opportunities.
Growth is primarily driven by rising utilisation of personal care and household aerosol products, supported by growing disposable income.
By Product Type, Hydrocarbons dominated the market with a 46.30% share in 2025, reflecting their low cost and broad formulation compatibility.
Europe dominated the market with a 34.60% share in 2025, supported by strong demand across personal care, household, and medical applications.
