
Aircraft Doors Market Report Scope & Overview:
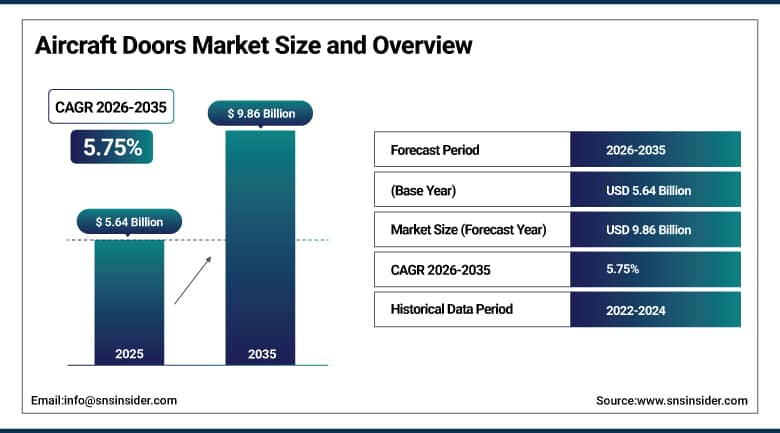
The Aircraft Doors Market was valued at USD 5.64 Billion in 2025 and is expected to reach USD 9.86 Billion by 2035, growing at a CAGR of 5.75% from 2026 to 2035.
The growth of the aircraft doors market is occurring at a fast pace due to high commercial backlog orders with Airbus and Boeing, global fleet expansion, and safety requirements that require airlines to replace old door systems. The aircraft door systems are structural devices that are designed to withstand pressure differences and facilitate secure entry and exit while operating under difficult cycles. These consist of passenger doors, cargo doors, emergency doors, and service doors on both commercial, military, and general aviation aircraft. The growth in the market is driven by increased safety requirements, developments in aircraft doors, higher production of commercial aircraft, and wide body/multi-deck aircraft programs that need passenger doors on upper decks.
Advanced door technology is being used in almost 65% of new airplanes, as there is a trend towards lightweight and robust materials for the doors which add to the performance of the airplanes in terms of safety and efficiency.
To Get More Information On Aircraft Doors Market - Request Free Sample Report
Aircraft Doors Market Trends
- Rising adoption of advanced composites is reducing aircraft door weight while improving fuel efficiency.
- Growing narrow-body aircraft production recovery is creating opportunities for aircraft door manufacturers and suppliers.
- Increasing new aircraft programs, including COMAC C919 and Irkut MC-21, are expanding opportunities for door system suppliers.
- Expanding eVTOL development is creating new demand for specialized door systems across next-generation electric aircraft.
- Strategic partnerships are accelerating development of lightweight, pressure-resistant, and advanced aircraft door designs.
The U.S. Aircraft Doors Market Outlook
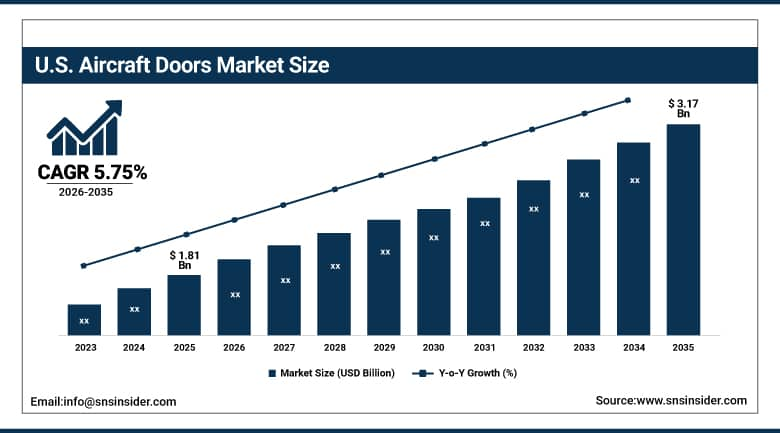
The U.S. aircraft doors market was valued at USD 1.81 Billion in 2025 and is projected to reach USD 3.17 Billion by 2035, growing at a CAGR of 5.75% during 2026–2035.
The top companies that manufacture aerospace equipment in the country are continuing to increase capacity in the manufacture of doors in aircraft because of the huge backlog orders and production of narrow body and wide body aircraft. The defense industry investments in the manufacture of doors for their military aircraft, along with the production of key commercial aircraft, have helped sustain the domestic demand for door technology.
The US aircraft doors sector is driven by robust aircraft production, sizeable OEM order backlog, and investments in military aircraft. Improvement in narrow body production along with growing demand for lightweight and modern door solutions is fueling growth prospects in domestic aircraft manufacturing, aftermarket, and military sectors.
Aircraft Doors Market Segment Analysis
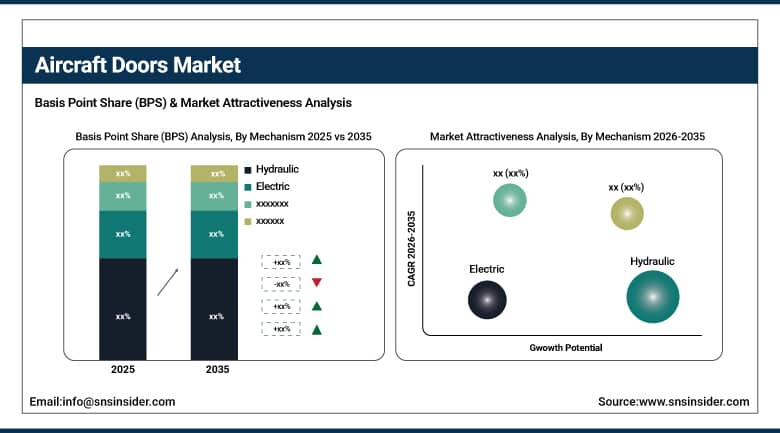
- By Mechanism, hydraulic dominated the aircraft doors market with a 52.15% share in 2025, while electric is the fastest-growing mechanism segment with a CAGR of 6.84% from 2026–2035.
- By Application, fixed-wing dominated the aircraft doors market with a 78.60% share in 2025, while eVTOL is the fastest-growing application segment with a CAGR of 8.06% from 2026–2035.
- By Door Type, passenger doors dominated the aircraft doors market with a 38.70% share in 2025, while cargo doors is the fastest-growing door type segment with a CAGR of 7.20% from 2026–2035.
- By End Use, OEM dominated the aircraft doors market with a 65.74% share in 2025, while aftermarket is the fastest-growing end use segment with a CAGR of 6.22% from 2026–2035.
By Mechanism, hydraulic dominated the aircraft doors market, while electric is the fastest-growing segment.
On the basis of mechanism, the market share of hydraulic systems stood at 52.15% in 2025. Hydraulic systems continue to dominate because of their proven reliability in most commercial and military aircraft doors as they offer the necessary power and accuracy needed for the efficient opening of the doors.
Electric mechanisms are forecasted to rise at a 6.84% CAGR through 2035. Growing manufacturer preference for electric door actuation systems offering reduced weight, improved reliability, and simplified maintenance compared to hydraulic alternatives is driving rapid segment growth, as next-generation aircraft programs increasingly adopt more-electric architecture across door and other subsystems.
By Application, fixed-wing dominated the aircraft doors market, while eVTOL is the fastest-growing segment.
The market for Aircraft Doors was led by the fixed-wing category due to the vast size of the world's fixed-wing fleets in commercial, military, and general aviation, which need door systems; this is the primary application type that forms the bedrock of the industry and has been around the longest.
CAGR at 8.06% of the eVTOL market segment has also resulted in the entry of several companies such as Eve Air Mobility, which has chosen to work with Latecoere as their door supplier for their electric vertical take-off and landing aircraft project. Investment in the area of urban air mobility and advanced air mobility systems has led to high growth of the eVTOL door segment.
By Door Type, passenger doors dominated the aircraft doors market, while cargo doors is the fastest-growing segment.
Passenger dominated the door type segment with a 38.70% share in the aircraft doors market. Passenger doors dominated the market due to high installation volumes in commercial narrowbody and widebody aircraft and strict safety regulations, representing the largest single door type category across the global commercial aviation fleet.
The cargo doors segment is expected to register the fastest CAGR of 7.20% during the forecast period 2026-2035. Cargo doors hold a significant and growing share, driven by growth in air freight and widebody fleets, as expanding global e-commerce and logistics demand continues driving strong investment in dedicated freighter aircraft and cargo door system upgrades.
By End Use, OEM dominated the aircraft doors market, while aftermarket is the fastest-growing segment.
In terms of end-use applications, the OEM vertical captured 65.74% of revenues in 2025. The OEM vertical continues to be the leading end-use category due to steady manufacturing of new planes on account of unprecedented order backlogs at Airbus and Boeing, which is the main source for door system purchases as the door system is integrated into new plane manufacturing.
The aftermarket is expected to expand at a 6.22% CAGR between 2026 and 2035. Increased age of the world’s fleet and safety demands which lead airlines to replace and improve their doors are some of the factors contributing to the growth of the aftermarket segment due to higher investment in door system replacements and upgrades.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Aircraft Doors Market Insights
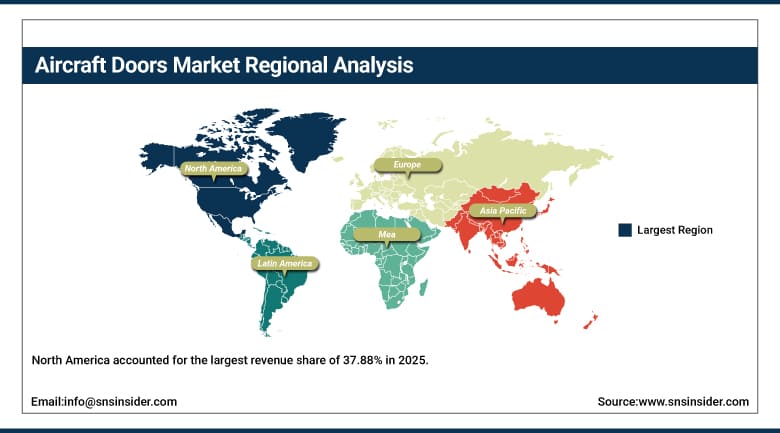
North America accounted for the largest revenue share of 37.88% in 2025. This was driven by early narrow-body aircraft recovery, the resumption of B737MAX production, and sustained demand for door systems across the region's substantial commercial and military aircraft manufacturing base.
The US was the leading country within the North America aircraft doors market in 2025, driven by record commercial backlogs and sustained narrow-body and wide-body aircraft production. Canada is contributing to regional growth through its own expanding aerospace manufacturing sector and growing Bombardier business jet door system production.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Aircraft Doors Market Insights
Europe contributed significantly in in the aircraft doors market 2025. This can be attributed to the fact that there is considerable manufacturing capacity of commercial aircraft in the region with Airbus, presence of key door system manufacturers, and the expected rise in production capacity of key aircraft programs like the A320 series.
Germany contributes at 6.7% CAGR, concentrating on materials and design of aircraft doors. Other nations like France and the UK, having major manufacturing capabilities for aerospace and being the primary manufacturer of the Airbus aircrafts and Latecoere door systems, respectively, contribute to the market as well.
Asia Pacific Aircraft Doors Market Insights
The Asia-Pacific region is projected to post the fastest growth, with a 6.63% CAGR through 2035. The market growth is driven by market entry of new aircraft programs including COMAC C919 and Irkut MC-21, alongside rapidly expanding domestic commercial and military aviation manufacturing capacity across the region.
In terms of CAGR, China ranks first with 7.8%, while it is propelled by the fast growth of the aviation industry along with rising needs for civilian and military aircraft production. On the other hand, India ranks second with 7.3% CAGR due to the fast development of its aviation industry along with an increase in the manufacture of aerospace products.
Middle East & Africa and Latin America Aircraft Doors Market Insights
Middle East & Africa and Latin American regions are gradually expanding aircraft door market participation as commercial and defense aviation investment grows across both regions, supported by increasing regional airline fleet expansion and aerospace manufacturing development.
Brazil is set to be a prominent Latin American market fueled by Embraer's substantial commercial and business jet manufacturing capacity and growing domestic aerospace supply chain investment. The Middle East & Africa region has UAE and Saudi Arabia investing in expanding national carrier fleets and aviation infrastructure requiring sophisticated door system maintenance and aftermarket support.
Market Dynamics
Growth Drivers: Rising commercial aircraft backlogs and safety compliance driving market growth
Record commercial backlogs at Airbus and Boeing, the expansion of global fleets, and stricter safety expectations that prompt airlines to upgrade their door systems are among the primary drivers of the Aircraft Doors Market. Growth in commercial aircraft production increasing demand for passenger and service doors, combined with rising safety requirements driving adoption of advanced pressure-resistant door designs, continues to support sustained demand across commercial, military, and general aviation door manufacturing.
Expansion of wide-body and multi-deck aircraft programs requiring specialized upper-deck passenger doors, increasing use of lightweight materials to improve door durability and reduce aircraft weight, and growing reliance on reliable access control systems for cargo, maintenance, and crew compartments continue to drive market expansion. Rising aircraft production fueling growth due to increasing demand for safe and compliant structural components, and strategic partnerships driving innovation in aircraft door technology, are further supporting demand across the forecast period.
Restraints: High certification costs and supply chain complexity limiting market expansion
Another major challenge for the growth of the market is that of the high costs and long times involved in the certification process of newly designed doors, which involves a lot of testing and regulation and can impede the speed at which door manufacturers develop light-weight and electrically operated doors.
Also, the complexity of incorporating new materials and technologies like composite materials and electric mechanisms into door designs, while ensuring the maintenance of certain performance standards, needs considerable research and development expenditures. Disruptions within the supply chain involving aerospace grade components can also pose production time risks for door manufacturers.
Opportunities: Expansion of eVTOL platforms and aftermarket modernization creating new growth avenues
Growing investment in urban air mobility and eVTOL aircraft development represents a significant market opportunity, as emerging aircraft manufacturers increasingly partner with specialized door suppliers for next-generation electric vertical takeoff and landing platforms requiring purpose-built door system engineering.
There is a considerable growth opportunity in the continued expansion of aftermarket door system modernization as aging global fleets require upgrades meeting stricter safety expectations. The expansion of new aircraft program manufacturing capacity, including COMAC C919 and Irkut MC-21, in emerging markets across Asia Pacific is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Eve Air Mobility selected Latecoere as its door supplier for its eVTOL aircraft program, marking a significant milestone in the expansion of specialized door system supply chains into the emerging urban air mobility sector.
- 2025: Boeing continued the resumption of 737 MAX production ramp-up, driving increased demand for narrow-body aircraft passenger and service door systems across its expanding commercial aircraft manufacturing operations.
- 2026: Airbus expanded its A320 family door system production capacity, strengthening its ability to support the program's expected production rate rebound amid strong commercial aircraft demand.
- 2026: Safran launched an updated lightweight composite passenger door system, offering aircraft manufacturers enhanced fuel efficiency through reduced door weight while maintaining stringent safety performance standards.
Aircraft Doors Market key players are:
- Latecoere S.A.
- Embraer S.A. (Eve Air Mobility)
- The Boeing Company
- Airbus SE
- Bombardier Inc.
- Lockheed Martin Corporation
- Safran S.A.
- GKN Aerospace (Melrose Industries)
- Triumph Group, Inc.
- Spirit AeroSystems Holdings, Inc.
- Moog Inc.
- Parker Hannifin Corporation
- Meggitt PLC (Parker Hannifin)
- Nordam Group LLC
- Aernnova Aerospace S.A.U.
- Senior Aerospace
- Collins Aerospace (RTX Corporation)
- Sonaca Group
- AAR Corp.
- Diehl Aviation
Aircraft Doors Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.64 Billion |
| Market Size by 2035 | USD 9.86 Billion |
| CAGR | CAGR of 5.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Mechanism (Hydraulic, Electric, Pneumatic) • By Application (Fixed-Wing, Rotary Wing, eVTOL Aircraft) • By Door Type (Passenger, Cargo, Emergency Exit, Service/Utility, Landing Bay, Cockpit) • By End Use (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Latecoere S.A., Embraer S.A. (Eve Air Mobility), The Boeing Company, Airbus SE, Bombardier Inc., Lockheed Martin Corporation, Safran S.A., GKN Aerospace (Melrose Industries), Triumph Group, Inc., Spirit AeroSystems Holdings, Inc., Moog Inc., Parker Hannifin Corporation, Meggitt PLC (Parker Hannifin), Nordam Group LLC, Aernnova Aerospace S.A.U., Senior Aerospace, Collins Aerospace (RTX Corporation), Sonaca Group, AAR Corp., Diehl Aviation. |
Frequently Asked Questions
The Aircraft Doors Market is expected to grow at a CAGR of 5.75% from 2026 to 2035.
The Aircraft Doors Market was valued at USD 5.64 Billion in 2025.
The market is driven by record commercial backlogs at Airbus and Boeing, expansion of global fleets, and stricter safety expectations prompting door system upgrades.
The OEM segment dominated the Aircraft Doors Market, accounting for approximately 65.74% market share.
The North America region dominated the Aircraft Doors Market in 2025, accounting for 37.88% of the market revenue.
