
Aircraft Nacelle and Thrust Reverser Market Report Scope & Overview:
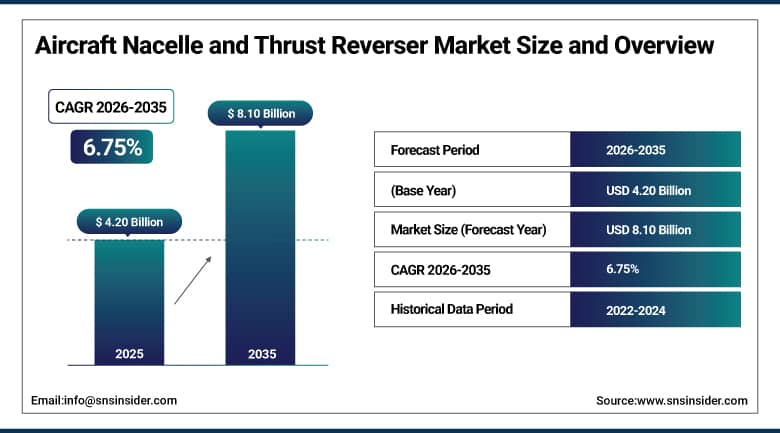
The Aircraft Nacelle and Thrust Reverser Market was valued at USD 4.20 Billion in 2025 and is expected to reach USD 8.10 Billion by 2035, growing at a CAGR of 6.75% from 2026-2035.
The Aircraft Nacelle and Thrust Reverser Market growth is being driven primarily by rising commercial aircraft delivery rates and sustained fleet modernization, as airlines continue replacing older, less efficient aircraft with new-generation platforms that demand advanced nacelle and thrust reverser systems engineered for lower fuel burn and reduced noise emissions. Growing maintenance, repair, and overhaul activity across an aging global fleet is adding a further layer of demand, since thrust reversers undergo among the highest levels of physical stress of any nacelle component and require periodic refurbishment even between major heavy maintenance checks.
Collins Aerospace, a subsidiary of RTX Corporation, completed the divestiture of its traditional hydraulic thrust reverser actuator business to Safran in 2025, with the European Commission clearing the transaction in early April 2025 and national regulators in Italy and the United Kingdom issuing final approvals by early June 2025.
To Get More Information On Aircraft Nacelle and Thrust Reverser Market - Request Free Sample Report
Aircraft Nacelle and Thrust Reverser Market Trends
-
Accelerating transition from hydraulic to electric thrust reverser actuation systems offering meaningful weight reduction.
-
Growing adoption of lightweight composite materials for nacelle structures supporting broader aircraft fuel efficiency goals.
-
Rising maintenance, repair, and overhaul activity supporting proactive thrust reverser refurbishment ahead of scheduled heavy checks.
-
Expanding next-generation narrowbody engine programs driving demand for advanced, low-drag nacelle inlet and fan cowl designs.
-
Increasing supplier investment in perforated acoustic liner technology improving noise attenuation without added weight.
-
Growing regional aircraft demand supporting sustained turboprop nacelle and thrust reverser procurement outside major commercial platforms.
U.S. Aircraft Nacelle and Thrust Reverser Market Outlook
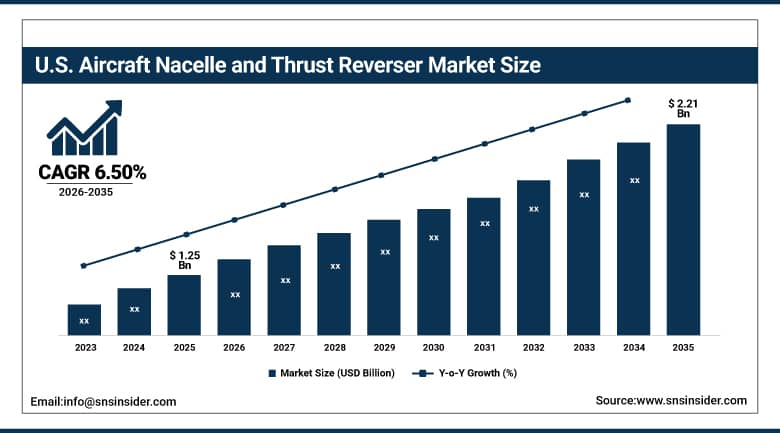
The U.S. Aircraft Nacelle and Thrust Reverser Market was valued at USD 1.25 Billion in 2025 and is expected to reach USD 2.21 Billion by 2035, growing at a CAGR of 6.50% from 2026-2035.
The U.S. Aircraft Nacelle and Thrust Reverser Market growth continues to be reinforced by a concentration of leading domestic nacelle system integrators, including Collins Aerospace and General Electric, both investing heavily in next-generation electric actuation and low-drag inlet technology. Sustained Boeing production rates, combined with growing domestic MRO capacity supporting an aging commercial fleet, continue to reinforce steady demand across both OEM and aftermarket channels.
Collins Aerospace, headquartered in Charlotte, North Carolina, and Air New Zealand entered a proactive nacelle and thrust reverser maintenance agreement in 2026 covering the carrier's fleet of 14 Boeing 787 Dreamliner aircraft, which average 9.3 years of age and are approaching the mid-life refresh phase typically occurring between 10 and 12 years of service.
Aircraft Nacelle and Thrust Reverser Market Segment Analysis
-
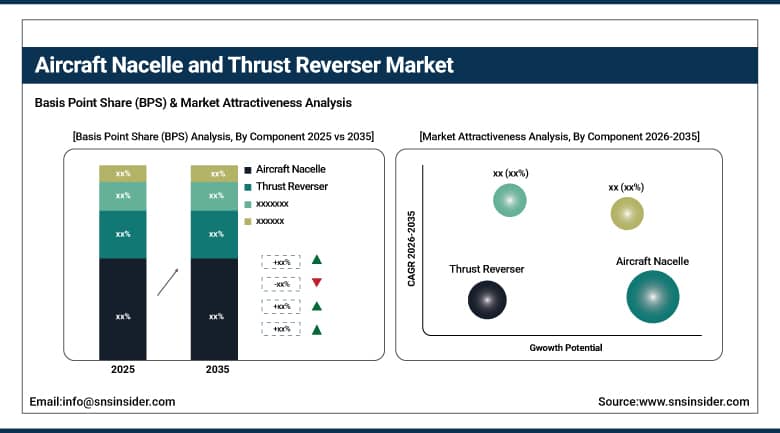
By Component, the Aircraft Nacelle segment dominated the Aircraft Nacelle and Thrust Reverser Market with approximately 58.60% share in 2025, while the Thrust Reverser segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Engine Type, the Turbofan segment dominated the Aircraft Nacelle and Thrust Reverser Market with approximately 78.10% share in 2025, while the Turboprop segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Material, the Aluminum Alloys segment dominated the Aircraft Nacelle and Thrust Reverser Market with approximately 42.60% share in 2025, while the Composites segment is the fastest growing with a CAGR of approximately 8.40%.
-
By Aircraft Type, the Commercial segment dominated the Aircraft Nacelle and Thrust Reverser Market with approximately 57.30% share in 2025, while the General Aviation segment is the fastest growing with a CAGR of approximately 6.90%.
By Component, Aircraft Nacelle Dominates the Aircraft Nacelle and Thrust Reverser Market and Thrust Reverser Grows Fastest
Aircraft nacelle structures continue to anchor the component segment, encompassing the inlet cowl, fan cowl, and inner fixed structure that collectively represent a larger share of total system value than the thrust reverser mechanism housed within them. Structural complexity across the inlet cowl, fan cowl, and inner fixed structure requires substantial engineering investment, giving established nacelle integrators a real technical advantage over newer entrants attempting to compete in this category.
Thrust reversers represent the fastest-growing component category, driven by the industry's accelerating shift toward electric actuation technology and rising demand for advanced translating sleeve and O-duct configurations across next-generation engine programs. Continued innovation in noise attenuation and weight reduction technology specific to thrust reverser deployment mechanisms is reinforcing this segment's above-average growth trajectory relative to the broader nacelle structure category. Growing OEM demand for fully integrated nacelle packages, rather than separately sourced components, continues to favor suppliers capable of delivering complete systems engineered as a single coordinated unit.
By Engine Type, Turbofan Dominates the Aircraft Nacelle and Thrust Reverser Market and Turboprop Grows Fastest
The engine-type of turbofan continues to dominate due to its wide use in commercial aviation in light of its high fuel efficiency and low noise emissions compared to the old turbojet engine type, which is used in a diminishing fraction of the global fleet. Years of experience and performance data gathered from worldwide commercial airlines further solidify the leading position of the turbofan engine type in terms of predictability of long-term maintenance costs.
The turboprop engine type is the fastest growing engine type market segment due to the increasing demand for regional flights and short-distance services that are handled better by turboprop planes compared to large turbofans. The expanding fleets of regional carriers in emerging markets will continue to drive this trend forward.
By Material, Aluminum Alloys Dominates the Aircraft Nacelle and Thrust Reverser Market and Composites Grows Fastest
Aluminum alloys still dominate the material category due to the benefit of having good strength-to-weight ratios, a proven manufacturing base and low cost production compared to the use of composite materials which is relatively expensive despite being more advanced. The infrastructure set up for stamping and forming of aluminum alloys in decades past has kept per-unit costs of aluminum alloy nacelles competitive against the higher capital costs associated with composite materials.
Composites are the fastest growing material category because carbon fiber and other composite materials are increasingly being used by manufacturers to reduce weight, beyond what aluminum can offer. Increasing demand for next generation narrow body nacelle structures makes this category even more attractive. Early adopters of composite manufacturing technology are set to benefit from high value as OEMs specify the use of composites in their next generation aircraft programs.
By Aircraft Type, Commercial Dominates the Aircraft Nacelle and Thrust Reverser Market and General Aviation Grows Fastest
Commercial aviation continues to dominate the aircraft-type segment, consistent with the sheer scale of global commercial fleet size relative to military and general aviation categories, and the correspondingly larger volume of nacelle and thrust reverser systems required across new aircraft deliveries and aftermarket support. Airlines and lessors also favor commercial aviation's established maintenance and parts supply infrastructure, which continues to make nacelle and thrust reverser procurement more predictable than in smaller aircraft categories with less standardized support networks.
General aviation represents the fastest-growing aircraft-type category, driven by rising business jet deliveries and growing demand for advanced nacelle systems on smaller, more fuel-efficient platforms. Continued expansion of the global business aviation fleet continues to reinforce this segment's above-average growth trajectory. Manufacturers specifically targeting business jet platforms continue to develop compact, lightweight nacelle designs suited to smaller engine diameters, a specialized engineering focus distinct from the requirements of larger commercial aircraft.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
77.80% |
|
Europe |
France |
24.60% |
|
Asia Pacific |
China |
37.40% |
|
Latin America |
Brazil |
29.20% |
|
Middle East & Africa |
UAE |
31.60% |
North America Aircraft Nacelle and Thrust Reverser Market Insights
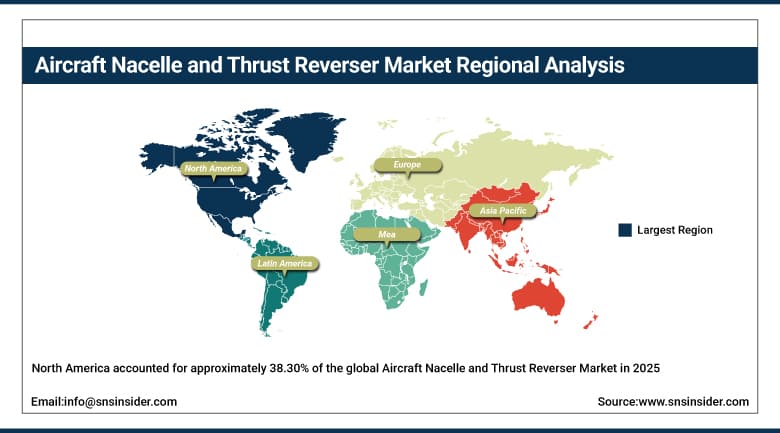
North America accounted for approximately 38.30% of the global Aircraft Nacelle and Thrust Reverser Market in 2025, making it the largest regional market, supported by a concentration of leading nacelle system integrators, including Collins Aerospace and General Electric, alongside sustained Boeing production rates across multiple commercial aircraft programs. Sustained venture and private capital investment in domestic aerospace manufacturing capacity further reinforces North America's leading position, even as international competitors continue narrowing the technology gap in select material and actuation categories.
Canada contributes additional regional demand through its participation in North American aerospace manufacturing supply chains. Continued domestic MRO capacity expansion supporting an aging commercial fleet further reinforces North America's leading position. Mexico's growing role in North American aerospace supply chains, tied to broader nearshoring-driven manufacturing investment, further ties regional demand together across all three countries.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Aircraft Nacelle and Thrust Reverser Market Insights
Asia Pacific is projected to expand at the fastest CAGR across the Aircraft Nacelle and Thrust Reverser Market during the 2026-2035 forecast period, driven by rising commercial aircraft deliveries and growing domestic aerospace manufacturing ambitions across the region's largest economies. China represents a significant contributor within the region, supported by continued development of the COMAC C919 program, which relies on Nexcelle's integrated nacelle and thrust reverser system supplied through Safran and General Electric's joint venture structure. India and Japan contribute additional regional demand, supported by expanding commercial fleet size and growing MRO capacity investment, while South Korea's aerospace manufacturing sector continues to attract new component supplier investment.
India and Japan contribute additional regional demand, supported by expanding commercial fleet size and growing MRO capacity investment. Rising regional aircraft orders continue to reinforce Asia Pacific's accelerating growth trajectory. Rising regional aircraft orders continue to reinforce Asia Pacific's accelerating growth trajectory, as domestic carriers across the region continue expanding fleet size to meet growing air travel demand.
Europe Aircraft Nacelle and Thrust Reverser Market Insights
Europe represents a significant regional market for aircraft nacelle and thrust reverser systems, anchored by France's substantial aerospace manufacturing base and its concentration of major developers, including Safran Nacelles, a global leader in aircraft nacelle systems. Germany's established aerostructures manufacturing base, home to several major component suppliers, further reinforces regional demand alongside France's leadership in complete nacelle system integration.
The United Kingdom and Germany contribute additional regional demand, supported by established aerostructures manufacturing capability and growing electric actuation technology investment. Continued Airbus production activity across the region reinforces steady demand for advanced nacelle systems. Continued Airbus production activity across the region reinforces steady demand for advanced nacelle systems, with the manufacturer's expanding delivery backlog supporting multi-year supplier commitments across the broader European supply chain.
MEA & Latin America Aircraft Nacelle and Thrust Reverser Market Insights
The Middle East and Africa region reflects growing strategic importance, with the UAE accounting for the largest regional contribution through its position as a major international aviation hub and growing MRO capacity investment supporting the region's expanding commercial fleet. Saudi Arabia is following a similar trajectory as it builds out domestic aviation infrastructure alongside broader economic diversification investment across the Gulf states.
Latin America is led by Brazil, home to Embraer, a leading regional jet manufacturer whose continued aircraft delivery programs support sustained demand for nacelle and thrust reverser systems. Mexico and Argentina contribute additional secondary demand tied to their respective aviation sectors. Mexico and Argentina contribute additional secondary demand tied to their respective aviation sectors, with both countries continuing to expand domestic MRO capacity supporting regional carrier fleets.
Market Dynamics
Growth Drivers: Fleet Modernization and Electric Actuation Adoption
Higher rates of commercial aircraft deliveries along with ongoing fleet modernization remain the key factors supporting market growth, since the airlines are continuously replacing old generation aircraft with new ones that need more sophisticated nacelle and thrust reversers with a capacity to save fuel and decrease emission. Increasing demand for the composite manufacturing technology is another factor supporting this underlying demand trend, since it becomes crucial for producers to provide lighter and more energy-efficient nacelles.
The ongoing shift from hydraulic to electric thrust reversers constitutes another important source of growth, since these products allow achieving significant weight reduction in comparison with hydraulic actuators. Increasing activities related to MRO of the existing aircraft fleet become another demand trend driver. Ongoing investments of private and venture capital into development of electric actuator technologies support the growing speed of their transition from prototype into commercial use.
Restraints: Raw Material Cost Volatility and Certification Complexity
Fluctuating input costs for aluminum, titanium, and composite raw materials represent a significant restraint, as nacelle manufacturers remain exposed to broader commodity market swings and trade policy changes that directly affect production costs across the supply chain. Suppliers without long-term material supply agreements are particularly exposed to these swings, which can compress margins even when finished-component demand remains steady across the broader commercial aviation supply chain.
The substantial certification complexity associated with new nacelle and thrust reverser designs adds a further restraint, as achieving airworthiness approval for novel materials or actuation technology requires years of testing and validation before commercial deployment becomes possible. Extended qualification timelines for new materials or actuation systems can meaningfully delay time-to-market, a particular challenge for smaller suppliers competing against established primes with deeper regulatory affairs capability.
Opportunities: Electric Actuation Technology and Next-Generation Engine Programs
Continued advancement of electric thrust reverser actuation technology presents a substantial growth opportunity, as suppliers that successfully commercialize lighter, more reliable electric systems are positioned to capture premium value from airlines and OEMs pursuing fuel efficiency improvements. Suppliers developing dedicated engineering capability specifically for narrowbody platforms are positioned to capture meaningful design-win volume as production rates for these programs continue climbing over the coming years.
Next-generation narrowbody engine programs represent a further opportunity, as manufacturers developing advanced, low-drag nacelle designs specifically engineered for these platforms are positioned to capture disproportionate share of new aircraft delivery volumes over the coming decade.
Recent Developments:
-
In July 2026, Collins Aerospace and Etihad Engineering announced a joint venture for nacelle and thrust reverser MRO services in Abu Dhabi. The facility will support Airbus A350 and Boeing 787 fleets, with operations expected to begin in the first quarter of 2027.
-
In July 2026, Collins Aerospace opened its Engineering Center of Excellence in Wolverhampton, UK, focused on developing and testing next-generation electric thrust reverser actuation systems. The center supports the company’s elecTRAS technology, which is designed to reduce aircraft system weight by 15–20% compared with conventional hydraulic actuation.
-
In 2025, Safran Nacelles recorded several production and program milestones, including entry into service of its nacelles for the Pearl 700 engine powering the Gulfstream G800, production of the 100th nacelle for COMAC’s C919, and delivery of its 4,000th thrust reverser for Honeywell HTF7000 engines.
Aircraft Nacelle and Thrust Reverser Market Key Players
-
General Electric Company
-
Safran S.A.
-
Rolls-Royce Holdings plc
-
Honeywell International Inc.
-
Pratt & Whitney (RTX Corporation)
-
MTU Aero Engines AG
-
Nexcelle
-
Liebherr-International AG
-
Aero Engine Controls
-
Bombardier Inc.
-
GKN Aerospace
-
Leonardo S.p.A.
-
Nordam Group
-
Spirit AeroSystems Holdings, Inc.
-
Triumph Group, Inc.
-
Collins Aerospace (RTX Corporation)
-
Woodward, Inc.
-
Meggitt PLC
-
FACC AG
-
The Boeing Company
Aircraft Nacelle and Thrust Reverser Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.20 Billion |
| Market Size by 2035 | USD 8.10 Billion |
| CAGR | CAGR of 6.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Aircraft Nacelle, Thrust Reverser) • by Engine Type (Turbofan, Turboprop, Turbojet/Gas Turbine) • by Material (Aluminum Alloys, Composites, Titanium Alloys, Nickel Chromium, Stainless Steel) • by End-User (OEM, MRO) • by Aircraft Type (Commercial, Military, General Aviation) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | General Electric Company, Safran S.A, Rolls-Royce Holdings plc, Honeywell International Inc., Pratt & Whitney (RTX Corporation), MTU Aero Engines AG, Nexcelle, Liebherr-International AG, Aero Engine Controls, Bombardier Inc., GKN Aerospace, Leonardo S.p.A., Nordam Group, Spirit AeroSystems Holdings, Inc., Triumph Group, Inc., CollinsAerospace (RTX Corporation), Woodward, Inc., Meggitt PLC, FACC AG, The Boeing Company |
Frequently Asked Questions
Key players include General Electric Company, Safran S.A., Rolls-Royce Holdings plc, Honeywell International Inc., and Collins Aerospace, among other leading aerospace manufacturers.
Continued advancement of electric thrust reverser actuation technology and next-generation narrowbody engine programs represent the primary opportunities.
Growth is primarily driven by rising commercial aircraft delivery rates and sustained fleet modernization combined with the industry's shift toward electric thrust reverser actuation.
By Component, Aircraft Nacelle dominated the market with approximately 58.60% share in 2025, reflecting the structure's larger share of total system value relative to the thrust reverser mechanism.
North America dominated the market with approximately 38.30% share in 2025, supported by leading nacelle system integrators and sustained Boeing production rates.
