
Anti-Counterfeit Packaging Market Report Scope & Overview:
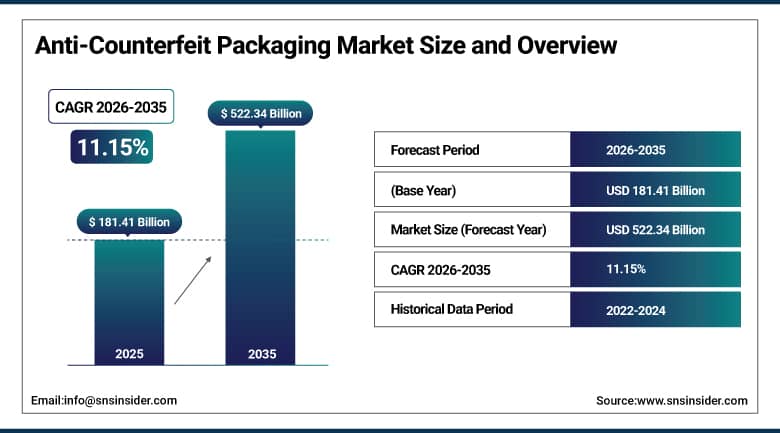
The Anti-Counterfeit Packaging Market was valued at USD 181.41 Billion in 2025 and is expected to reach USD 522.34 Billion by 2035, growing at a CAGR of 11.15% from 2026-2035.
The Anti-Counterfeit Packaging Market growth is being driven primarily by the digitization of anti-counterfeiting solutions, rising regulatory pressure across the consumer goods and pharmaceutical industries, and the rapid adoption of serialization and track-and-trace systems accelerating industry-wide growth. Anti-counterfeiting packaging is a solution developed to prevent the production and sale of counterfeit products, specially engineered to prevent various counterfeit practices by making it impossible to imitate the packaging of genuine products. Government mandates for serialization, traceability, and tamper evidence have transformed anti-counterfeit packaging from a value-added option into a mandatory compliance component in many markets, while rising sustainability expectations are simultaneously influencing material selection and design, pushing suppliers to integrate security features without compromising recyclability. As counterfeiters increasingly use AI-guided presses to mimic overt holograms, brands continue to pivot toward covert DNA inks and forensic taggants requiring lab-grade readers, pushing solution diversity and technical sophistication across the broader anti-counterfeit packaging industry.
In the third quarter of 2024, CCL Industries completed its acquisition of Systech International, a provider of digital brand protection and anti-counterfeit solutions, to strengthen its offerings for the pharmaceutical and cosmetics packaging markets. The acquisition reflects the broader industry pattern of established packaging and labeling suppliers acquiring specialized digital brand protection capability to deliver comprehensive, integrated anti-counterfeit packaging solutions, reinforcing the competitive position of scale players pursuing combined physical security features and digital serialization platforms as regulatory requirements and counterfeiting sophistication continue to increase across major global markets.
To Get More Information On Anti-Counterfeit Packaging Market - Request Free Sample Report
Anti-Counterfeit Packaging Market Trends
-
Rising adoption of forensic markers and DNA-based taggants requiring lab-grade readers to counter AI-replicated overt features.
-
Growing integration of blockchain-based digital product passports supporting end-to-end supply chain traceability.
-
Expanding use of RFID-enabled packaging extending real-time authentication and inventory visibility across supply chains.
-
Increasing sustainability-conscious security feature design that integrates authentication without compromising recyclability.
-
Rising consolidation among brand protection suppliers through acquisitions expanding combined digital and physical security portfolios.
-
Growing government mandates for mandatory serialization and track-and-trace systems across pharmaceutical and food sectors.
U.S. Anti-Counterfeit Packaging Market Outlook
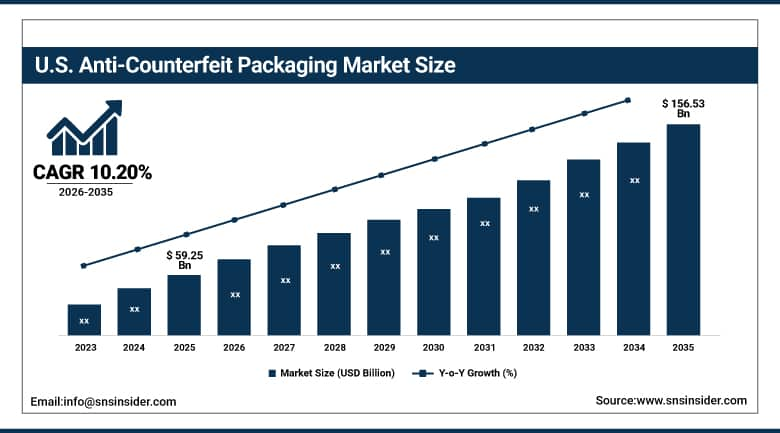
The U.S. Anti-Counterfeit Packaging Market was valued at USD 59.25 Billion in 2025 and is expected to reach USD 156.53 Billion by 2035, growing at a CAGR of 10.20% from 2026-2035.
The growth of the U.S. Anti-Counterfeit Packaging Market is also expected to be strengthened by increasing consumption of food and beverages, healthcare products, cosmetics, and electronic devices along with strict enforcement of regulation with regard to authenticity of products from regulated industries. In addition, the robust pharmaceutical production and distribution industry in the country will drive the demand for anti-counterfeit packaging as there are strict regulations under the Drug Supply Chain Security Act with respect to serialization of products for ensuring track and trace capabilities in the pharmaceutical industry. Increased usage of e-commerce and online retailing will drive the demand for anti-counterfeit packaging to ensure protection of brands through various distribution channels.
In the first quarter of 2025, Avery Dennison Corporation named a new Vice President to head its global anti-counterfeiting solutions business segment with the aim of driving innovation and growth in the space of secure packaging technology. This example demonstrates how the well-known American providers of labeling and packaging continue to place emphasis on assigning dedicated leadership and making investments in anti-counterfeit technology as a separate area of development, reflecting the significance of specialization in the context of competition for innovative technology among domestic brand protection suppliers.
Anti-Counterfeit Packaging Market Segment Analysis
-
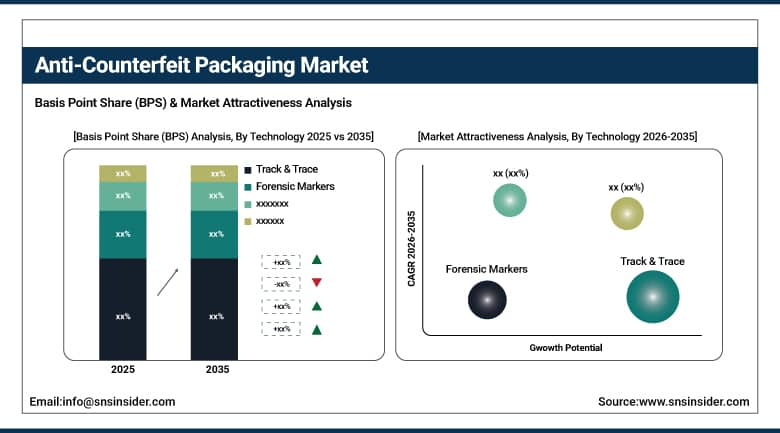
By Technology, the Track & Trace segment dominated the Anti-Counterfeit Packaging Market with approximately 44.60% share in 2025, while the Forensic Markers segment is the fastest growing with a CAGR of approximately 13.80%.
-
By Packaging Format, the Bottles & Jars segment dominated the Anti-Counterfeit Packaging Market with approximately 27.60% share in 2025, while the Pouches & Sachets segment is the fastest growing with a CAGR of approximately 12.40%.
-
By End-Use Industry, the Pharmaceutical/Healthcare segment dominated the Anti-Counterfeit Packaging Market with approximately 35.60% share in 2025, while the Personal Care & Cosmetics segment is the fastest growing with a CAGR of approximately 12.80%.
By Technology, Track & Trace Dominates the Anti-Counterfeit Packaging Market and Forensic Markers Grows Fastest
Track and Trace technology dominates in terms of market share because it has become an indispensable compliance requirement due to the compliance infrastructure based on the hardware for serialization, vision inspection, and cloud vaults in light of mandatory regulations concerning serialization in different regulatory jurisdictions. Regulatory mandates on serialization, track and trace, and tamper evident have made the technology a compliance requirement rather than value added technology for the pharmaceutical industry and increasingly for food and beverages sector too, maintaining the leadership of the Track and Trace category owing to its fundamental significance for meeting mandatory regulations.
Forensic markers, including DNA inks and taggants requiring lab-grade readers, are the fastest-growing technology as counterfeiters increasingly use generative AI-guided printing tools to replicate guilloché patterns and kinetic micro-text with startling fidelity, cutting the deterrent value of purely visible security marks. This growth is reinforced by brands' continued pivot toward covert authentication features that cannot be easily replicated even with sophisticated AI-assisted counterfeiting tools, positioning forensic markers as an increasingly essential layer within multi-tiered brand protection strategies that combine overt, covert, and forensic authentication technology.
By Packaging Format, Bottles & Jars Dominates the Anti-Counterfeit Packaging Market and Pouches & Sachets Grows Fastest
Bottles and jars are dominant in terms of the format as a result of the widespread use in pharmaceutical, food and beverage, as well as personal care applications, where the rigid containers offer a proven platform for incorporating security labels, tamper-evident seals, and other authentication elements. The versatility of the format in accommodating various technologies of authentication along with the format's well-established presence as the primary packaging format for numerous regulated pharmaceutical and premium consumer goods is continuing to fuel the dominance of bottles and jars in the packaging format category among anti-counterfeit packaging suppliers.
The pouches and sachets represent the fastest growing format segment due to the increase in the popularity of the flexible packaging format in food, beverage, and personal care applications, demanding a different approach to incorporating security elements, suitable specifically for the flexible film substrate rather than the rigid container surface. It is additionally fueled by the rising consumer preference for lightweight, material-efficient flexible packaging format, putting anti-counterfeit packaging suppliers offering security solutions for the flexible substrates in the advantageous position.
By End-Use Industry, Pharmaceutical/Healthcare Dominates the Anti-Counterfeit Packaging Market and Personal Care & Cosmetics Grows Fastest
The pharmaceutical and healthcare sector dominates end-use demand, driven by the rising demand for genuine pharma products and stringent regulations combined with increasing consumer safety concerns that continue to mandate comprehensive anti-counterfeit packaging adoption. The sector's exposure to potentially life-threatening consequences from counterfeit products continues to justify substantial per-unit investment in serialization, tamper evidence, and forensic authentication technology, sustaining pharmaceutical and healthcare's position as the largest end-use industry for anti-counterfeit packaging suppliers globally.
Personal care and cosmetics is the fastest-growing end-use industry as rising counterfeit activity targeting premium beauty and personal care brands continues to drive increased investment in authentication and brand protection technology. This growth is reinforced by growing e-commerce distribution of cosmetics and personal care products, which continues to create new counterfeiting opportunities that brands increasingly address through layered security packaging combining serialization, holographic features, and forensic markers to protect brand equity and consumer trust across increasingly complex online and offline distribution channels.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Anti-Counterfeit Packaging Market Insights
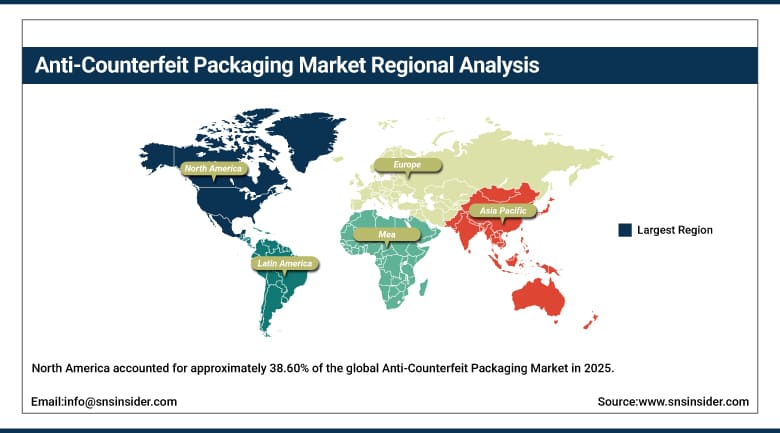
North America accounted for approximately 38.60% of the global Anti-Counterfeit Packaging Market in 2025, making it the largest regional market, due to growing consumer consumption of food and beverages, healthcare items, cosmetics, and electronics across the region. The United States anchors regional demand, home to a substantial concentration of established brand protection technology suppliers and a stringent regulatory environment governing pharmaceutical serialization and consumer product authentication requirements.
Canada is contributing incremental regional demand as its regulatory framework continues to align with domestic pharmaceutical and consumer goods authentication requirements. Continued regulatory enforcement, combined with rising e-commerce distribution complexity requiring enhanced brand protection capability, is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Anti-Counterfeit Packaging Market Insights
Asia Pacific represents the fastest-growing regional market, with a growth rate of around 12.60% during 2026-2035, led by the continued growth in the manufacturing base within the region and expansion of the middle class, increasing both counterfeiting activity and brand protection measures. The manufacturing industry in China along with regulatory initiatives within the pharmaceutical industry to ensure compliance within this market will continue to increase the need for anti-counterfeit packaging technology in the region.
India represents an important contributor to the increased demand due to the expanding pharma manufacturing sector in conjunction with the increased need for regulation within the domestic market. Both Japan and South Korea will contribute to the increased market size as consumer electronics and pharmaceutical manufacturing adopt more anti-counterfeit packaging technology.
Europe Anti-Counterfeit Packaging Market Insights
Europe holds an important share in the global Anti-Counterfeit Packaging Market due to the presence of Germany's large production base for pharmaceutical and consumer products and its stringent regulatory environment, which includes the Falsified Medicines Directive of the European Union that mandates complete pharmaceutical serialization. The European suppliers remain at the forefront in terms of developing the latest authentication technology, including holographic and forensic marker technology due to the presence of numerous brand protection technology suppliers in the region.
The demand from France, the United Kingdom, and Switzerland continues to grow steadily owing to the continuing investment made by regional brand protection technology suppliers in serving domestic and overseas pharmaceutical, luxury products, and consumer product segments.
MEA & Latin America Anti-Counterfeit Packaging Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing pharmaceutical and consumer goods sector investment across the United Arab Emirates and Saudi Arabia sustains demand for anti-counterfeit packaging technology addressing regional counterfeiting concerns. Regional governments continue to strengthen regulatory frameworks governing pharmaceutical and consumer product authenticity, supporting gradual anti-counterfeit packaging adoption across the broader region.
Latin American market is led by Brazil, which has a well-developed local base of pharmaceutical and consumer goods manufacturers, maintaining high levels of anti-counterfeiting packaging needs in many industries. Mexico is making an important contribution through increased investments in regional production capabilities driven by nearshoring. Adoption in the region is expanding with rising regulation and consumer awareness of counterfeit products' risks.
Market Dynamics
Growth Drivers: Regulatory Enforcement and Digital Authentication Technology Adoption Fuels Market Growth
Rising regulatory pressure across the consumer goods and pharmaceutical industries represents the primary driver of Anti-Counterfeit Packaging Market growth, as government mandates for serialization, traceability, and tamper evidence continue to transform anti-counterfeit packaging from a value-added option into a mandatory compliance component across an expanding range of regulated markets. The rapid adoption of serialization and track-and-trace systems continues to accelerate industry-wide growth, as pharmaceutical and increasingly food and beverage manufacturers must implement comprehensive authentication infrastructure to meet non-negotiable regulatory requirements.
The digitization of anti-counterfeiting solutions represents a second major growth driver, as brands increasingly integrate digital product authentication capability that works with existing barcodes and packaging to deliver immediate counterfeit detection alongside traditional physical security features. Rising consumer demand for transparency continues to reinforce this trend, resulting in substantial increased investment in the traceability of products across pharmaceutical, food and beverage, cosmetics, and electronics categories as brands seek to rebuild and maintain consumer trust amid growing counterfeit product prevalence.
Restraints: High Implementation Costs and Counterfeiter Technology Sophistication Hampers Market Growth
High implementation costs are an important constraint to the expansion of the market as the full-fledged anti-counterfeiting packaging technologies that integrate software-based serial numbers, vision inspection systems, and cloud infrastructure would require significant investment, which may prove to be prohibitive for small manufacturers who have budget constraints for compliance purposes. This factor remains an important driver behind the deployment of such technologies by bigger brands/ manufacturers only.
The increasing sophistication of counterfeiters represents a further restraint, as advances in technology make it easier than ever for bad actors to duplicate packaging or destroy anti-counterfeiting technologies, with generative AI-guided printing tools now capable of replicating even sophisticated overt security features including guilloché patterns and kinetic micro-text with startling fidelity. This escalating technological arms race requires continuous innovation and investment in increasingly sophisticated covert and forensic authentication technology to stay ahead of evolving counterfeiting capability.
Opportunities: Digital Product Passport Integration and Emerging Market Adoption Creates Growth Opportunities
Continued integration of digital product passports represents a substantial opportunity, as regulations including the European Sustainable Products Regulation continue to introduce requirements for comprehensive product transparency, accountability, and data integrity that combine end-to-end traceability with robust anti-counterfeiting measures to counter risks including greenwashing and data manipulation. Suppliers that can deliver integrated digital and physical authentication solutions are positioned to capture demand as this regulatory framework continues to expand across additional product categories and regions.
The continued expansion of anti-counterfeit packaging adoption across emerging markets offers a further avenue for growth, as globalization of trade and expansion of e-commerce platforms continue to make it increasingly challenging for manufacturers and consumers to distinguish between genuine and counterfeit products across rapidly growing developing economies. Suppliers that can establish cost-competitive regional manufacturing and distribution capability are well positioned to capture demand as emerging market brands increasingly invest in authentication technology to protect market share and consumer trust.
Recent Developments:
-
In the first quarter of 2025, SICPA launched a new security ink for pharmaceutical packaging, expanding its authentication technology portfolio for high-risk regulated industries.
-
In the fourth quarter of 2024, Systech and Kezzler announced a partnership to deliver end-to-end digital anti-counterfeit packaging solutions, integrating digital brand protection with serialization and traceability capability for global supply chains.
-
In the first quarter of 2025, SICPA opened a new research and development center focused on advancing anti-counterfeit packaging technologies, with a focus on integrating digital and physical security features.
-
In the second quarter of 2024, SICPA and IN Groupe announced a strategic partnership to co-develop advanced anti-counterfeit packaging technologies for high-risk industries including pharmaceuticals and luxury goods.
Anti-Counterfeit Packaging Market Key Players
-
CCL Industries Inc.
-
3M Company
-
SATO Holdings Corporation
-
Zebra Technologies Corporation
-
SICPA Holding SA
-
Avery Dennison Corporation
-
Authentix, Inc.
-
De La Rue plc
-
AlpVision SA
-
Applied DNA Sciences, Inc.
-
Systech International, LLC
-
OpSec Security Group plc
-
Impinj, Inc.
-
Honeywell International Inc.
-
Tesa SE
-
Schreiner Group GmbH & Co. KG
-
DuPont de Nemours, Inc.
-
Constantia Flexibles Group GmbH
-
Digimarc Corporation
-
Kezzler AS
Anti-Counterfeit Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 181.41 Billion |
| Market Size by 2035 | USD 522.34 Billion |
| CAGR | CAGR of 11.15% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Track & Trace, Holograms, RFID, Forensic Markers, Tamper Evidence, Mass Encoding) • By Packaging Format (Bottles & Jars, Blisters, Vials & Ampoules, Pouches & Sachets, Trays) • By End-Use Industry (Pharmaceutical/Healthcare, Food & Beverage, Personal Care & Cosmetics, Electronics, Automotive) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CCL Industries Inc., 3M Company, SATO Holdings Corporation, Zebra Technologies Corporation, SICPA Holding SA, Avery Dennison Corporation, Authentix, Inc., De La Rue plc, AlpVision SA, Applied DNA Sciences, Inc., Systech International, LLC, OpSec Security Group plc, Impinj, Inc., Honeywell International Inc., Tesa SE, Schreiner Group GmbH & Co. KG, DuPont de Nemours, Inc., Constantia Flexibles Group GmbH, Digimarc Corporation, Kezzler AS |
Frequently Asked Questions
Key players include CCL Industries Inc., 3M Company, SATO Holdings Corporation, Zebra Technologies Corporation, SICPA Holding SA, Avery Dennison Corporation, and Authentix, Inc., among other brand protection technology suppliers.
Continued integration of digital product passports and continued expansion of anti-counterfeit packaging adoption across emerging markets represent the primary opportunities.
Growth is primarily driven by rising regulatory pressure across the consumer goods and pharmaceutical industries combined with the digitization of anti-counterfeiting solutions.
By Technology, Track & Trace dominated the market with approximately 44.60% share in 2025, reflecting its foundational role as a mandatory compliance component across regulated pharmaceutical markets.
North America dominated the market with approximately 38.60% share in 2025, driven by growing consumer consumption of food and beverages, healthcare items, cosmetics, and electronics.
