
Automated Material Handling Equipment Market Report Scope & Overview:
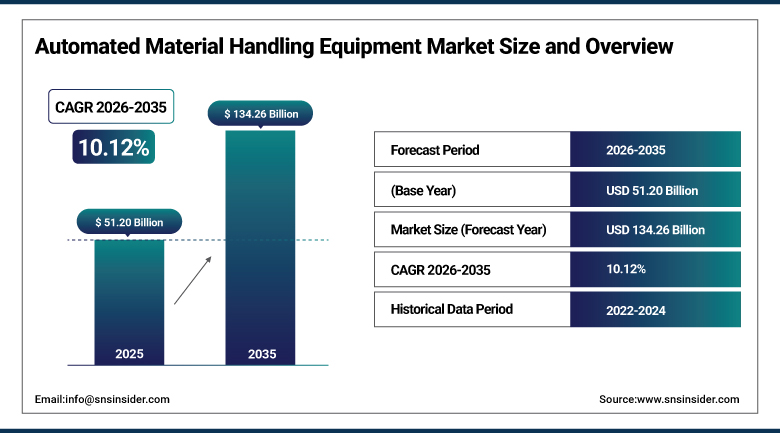
The Automated Material Handling Equipment Market was valued at USD 51.20 Billion in 2025 and is expected to reach USD 134.26 Billion by 2035, growing at a CAGR of 10.12% from 2026-2035.
The market for automated material handling equipment is growing consistently, fueled by the growing need for automation in the warehouse operations as well as efficient and optimal movements of materials in industries such as manufacturing, logistics, e-commerce, retail, and distribution sectors. The automated material handling equipment such as automated storage and retrieval systems, conveyors, automatic guided vehicles, autonomous mobile robots, and robotic handling systems ensures quick and precise movement, storage, and retrieval of the products. The fast growth in the area of e-commerce and fulfillment centers is fueling the growth in terms of the investments in automated warehouses, along with the shortage of labor and higher costs of operations, which is encouraging organizations to minimize manual handling operations.
In 2026, Honeywell introduced the Momentum Core warehouse software platform and IntelliSort Irregulars Sorter, designed to improve warehouse visibility, scalability, and automated parcel handling, with the sorter supporting throughput of up to 5,000 parcels per hour.
To Get more information Automated Material Handling Equipment Market - Request Free Sample Report
Automated Material Handling Equipment Market Trends
- Accelerating warehouse digitalization as e-commerce operators race to compress order fulfillment and delivery timelines
- Rising integration of autonomous mobile robots alongside traditional automated guided vehicles for flexible warehouse navigation
- Growing deployment of automated storage and retrieval systems addressing dense urban warehouse space constraints
- Increasing adoption of automation across semiconductor, electric vehicle, and healthcare manufacturing to meet stringent quality requirements
- Expanding large-scale infrastructure investment in bulk load material handling across mining, construction, and agricultural sectors
- Continued industry consolidation as established players acquire specialized robotics and automation startups to broaden technology portfolios
U.S. Automated Material Handling Equipment Market Outlook
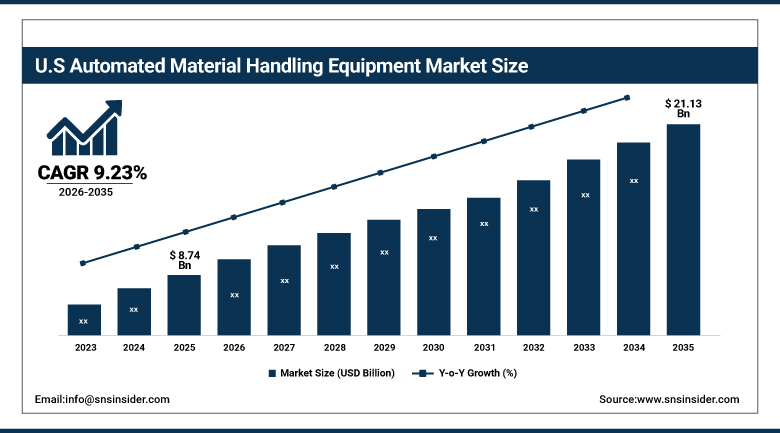
The U.S. Automated Material Handling Equipment Market was valued at approximately USD 8.74 Billion in 2025 and is expected to reach approximately USD 21.13 Billion by 2035, growing at a CAGR of approximately 9.23% from 2026-2035.
The U.S. Automated Material Handling Equipment Market enjoys robust growth on account of high demand for automated warehouses, e-commerce order fulfillment operations, manufacturing upgrades, and logistics. Adoption of automated storage and retrieval systems, conveyors, automatic guided vehicles, automatic mobile robots, and robotic handling equipment is assisting organizations in enhancing productivity and space utilization in the business operations. Tight labor conditions and requirement to keep the operating costs low have resulted in an increased investment in automation solutions, especially in warehouses and distribution centers. U.S. Bureau of Labor Statistics also indicates that automated guided vehicles, robotics, warehouse management systems, and artificial intelligence systems are being implemented by warehousing organizations.
Amazon continued its aggressive automated fulfillment center build-out throughout 2025, deploying additional generations of its Sequoia inventory storage system and expanding its fleet of autonomous mobile robots across U.S. distribution facilities. The company's continued capital investment in warehouse robotics reflects the broader competitive pressure American logistics operators face to match delivery speed expectations that automation alone can realistically satisfy at national scale.
Automated Material Handling Equipment Market Segment Analysis
- By Product, the conveyors & sortation systems segment dominated the automated material handling equipment market with approximately 28.60% share in 2025, while the autonomous mobile robots segment is the fastest growing with a CAGR of approximately 13.40%.
- By System Type, the unit load material handling segment dominated the automated material handling equipment market with approximately 64.20% share in 2025, while the bulk load material handling segment is the fastest growing with a CAGR of approximately 10.60%.
- By End-Use Industry, the E-commerce & retail segment dominated the automated material handling equipment market with approximately 32.40% share in 2025, while the semiconductor & electronics segment is the fastest growing with a CAGR of approximately 12.80%.
By Product, Conveyors & Sortation Systems dominates, Autonomous Mobile Robots grows fastest
Conveyors and sortation systems remain at the core of many fulfillment and manufacturing activities due to the ability of these systems to ensure continuous material handling, increase efficiency in order fulfillment, and improve productivity irrespective of the size or weight of the products involved. The scalability and ability to integrate conveyors and sortation systems with warehouse automation solutions give an edge to these technologies in high volume facilities.
Autonomous mobile robots have been gaining widespread acceptance because of the flexibility and sensor-based navigation which allow them to move around the facility without the need for fixed tracks associated with automated guided vehicles. The ability to adapt to changing conditions within the fulfillment center makes them a popular choice in scalable automation solutions.
By System Type, Unit Load dominates, Bulk Load grows fastest
Unit load material handling continues to dominate in a business-to-consumer, SKU-intensive environment, where individually packaged products moving through e-commerce fulfillment centers require the precision, flexibility, and controlled movement enabled by unit load systems.
Bulk load material handling is expanding at a faster pace as mining, construction, agriculture, and chemical industries increasingly automate the transportation of loose, granular, and liquid materials over long distances. This segment serves a distinct yet critical role in global raw material supply chains and is gaining investment, particularly across large-scale infrastructure, mining, and industrial projects in Asia-Pacific.
By End-Use Industry, E-commerce & Retail dominates, Semiconductor & Electronics grows fastest
E-commerce and retail fulfillment operations remain the largest end-use verticals because of increasing volume of online orders, variety of products being offered, and demand for quick order fulfillment. The automated material handling helps in the picking, sorting, storing, and transporting individual units through the fulfillment centers. Increasing consumer demands for quick deliveries and order fulfillment drive the companies toward automating their warehouses.
Semiconductor and electronics manufacturing is seeing the most rapid growth because of increased requirement for chip manufacturing, advanced packaging, and electronic products assembly, which demand controlled material handling environment. The automated material handling systems help in the precise transportation of wafers, components, and other sensitive units in order to reduce contamination, material handling errors, and disruption of the process.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
44.60% |
|
North America |
United States |
82.40% |
|
Europe |
Germany |
26.40% |
|
Latin America |
Brazil |
33.80% |
|
Middle East & Africa |
UAE |
30.60% |
Asia Pacific Automated Material Handling Equipment Market Insights
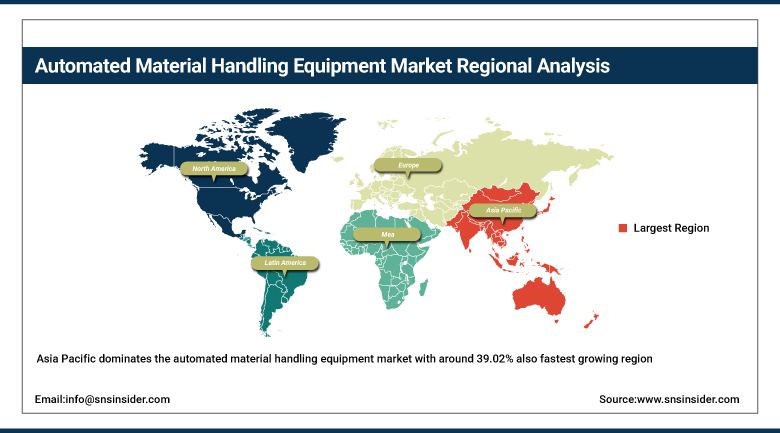
Asia Pacific dominates the automated material handling equipment market with around 39.02% also fastest growing region and is projected to register a CAGR of approximately 10.0% from 2026 to 2035. This is driven by rapid industrialization, large-scale expansion of manufacturing and logistics hubs, and increasing automation technology adoption across the region's largest economies. China, India, and Japan sit at the forefront of this growth, with government-backed Industry 4.0 initiatives and strong investments in modern warehousing and supply chain infrastructure continuing to fuel demand for AGVs, ASRS, conveyors, and industrial robotics.
China's e-commerce logistics giants, including JD.com and Cainiao, continue accelerating automated warehouse build-outs to meet compressed delivery commitments, while India's rapidly expanding manufacturing sector is drawing substantial new investment in automation infrastructure. Japan's mature robotics manufacturing base continues to supply advanced automation technology across the broader region.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automated Material Handling Equipment Market Insights
North America presents a large market for automated material handling equipment, with a well-developed logistics, manufacturing, and distribution network. This market is experiencing growth due to the development of e-commerce fulfillment facilities, improvements in warehousing facilities, difficulties recruiting skilled workers, and increased automation investments. Increased adoption of robotics, automated storage systems, conveyor systems, and autonomous mobile robots continues to boost demand across various industry sectors.
The largest market for automated material handling systems is found in the US, which is experiencing continued growth in terms of e-commerce fulfillment facilities and increased capacity of EV and semiconductors manufacturing facilities. While Canada's logistics and manufacturing industries are contributing to the market, the rising nearshoring manufacturing investments in Mexico contribute to automation infrastructure development.
Europe Automated Material Handling Equipment Market Insights
The market for automated material handling equipment in Europe is a mature one with high levels of technological advancement owing to the well-established manufacturing industry, logistics industry, automotive industry, and the e-commerce industry.
Germany leads demand in the region due to its extensive automotive and industrial manufacturing industry and a large number of automation equipment makers who have expertise in robotics and warehouse automation.
Both France and Italy provide significant demand due to their mature manufacturing industry, logistics industry, retail industry, and distribution industry. The two countries are investing in automated material handling facilities to increase productivity and deal with rising labor costs. Increased e-commerce activity and need for faster delivery are driving the use of robotic equipment, automated storage facilities, and conveyors.
MEA & Latin America Automated Material Handling Equipment Market Insights
The Middle East and Africa automated material handling equipment market is experiencing gradual development, supported by increasing investments in logistics, warehousing, manufacturing, and distribution infrastructure. The UAE represents a key regional market, driven by substantial investments in logistics and warehouse facilities as part of its broader strategy to strengthen its position as a regional trade and distribution hub. Growing e-commerce and supply-chain modernization are further encouraging automation adoption.
Latin America is led by Brazil, where expanding manufacturing, logistics, warehousing, and distribution investments are supporting gradual development of the automated material handling equipment market. Increasing focus on operational efficiency and supply-chain modernization is encouraging businesses to adopt automated systems. Mexico and Argentina contribute additional demand through their established manufacturing sectors, while growing industrial investments are creating further opportunities for warehouse and material handling automation.
Market Dynamics
Growth Drivers: Labor shortages and e-commerce growth fueling automation adoption
Use of robotics and automation to deal with the problem of skilled labor shortages is considered as one of the key factors driving the growth of automated materials handling equipment markets. The organizations use these systems for improving productivity, minimizing operational downtime, increasing efficiency, and maintaining throughput in the face of labor shortages. Continuous operations and efficient usage of resources are becoming additional factors that are encouraging companies to invest in automated handling systems.
Rapid growth of e-commerce and omnichannel retailing are some of the other important factors that are driving the market for automated handling systems, as the fulfillment providers are investing in automated conveyors, sorters, storage, picking, and retrieval systems. Increase in number of orders and the product variety are forcing the fulfillment centers to invest in automated warehouse systems.
Restraints: High capital costs and integration complexity limiting smaller-operator adoption
Substantial capital investment requirements for comprehensive automation deployment represent a key restraint, particularly for small and medium-sized warehouse and manufacturing operators. High upfront expenditure for automated storage systems, robotics, conveyors, software, integration, and supporting infrastructure can make adoption challenging where operational volumes remain relatively modest. Longer investment payback periods may further discourage organizations with limited capital availability from implementing large-scale automation projects.
Integration complexity across legacy facility infrastructure represents another significant restraint, as retrofitting older warehouses and manufacturing plants with modern automated systems can require extensive modifications. Existing layouts, storage configurations, electrical systems, and control architectures may need significant upgrades beyond equipment costs. These requirements can increase implementation timelines, project complexity, and overall deployment expenditure, particularly within aging facilities.
Opportunities: Semiconductor manufacturing precision and bulk-load infrastructure expansion opening new growth avenues
Growing automation across semiconductor and electronics manufacturing presents a significant opportunity for automated material handling equipment providers, as advanced chip fabrication and electronics assembly facilities require highly precise, contamination-controlled material movement. Increasing investments in semiconductor production capacity and advanced manufacturing infrastructure are creating demand for specialized handling systems capable of supporting stringent cleanliness, accuracy, and reliability requirements across increasingly complex production environments.
Large-scale bulk-load infrastructure expansion across mining, construction, and agricultural industries represents another growth opportunity, particularly across Asia-Pacific markets undertaking extensive infrastructure and industrial development programs. Increasing automation of raw-material transportation is driving demand for efficient systems capable of handling loose, granular, and bulk materials over long distances. Investments in mining capacity, construction projects, and agricultural infrastructure are further supporting deployment opportunities.
Recent Developments:
- 2026: Dematic expanded its flexible automation capabilities through a strategic partnership with GreyOrange, integrating the AI-powered GreyMatter platform into its software ecosystem to coordinate fixed automation, autonomous mobile robots, and human workflows across warehouse operations.
- 2025: Daifuku Co., Ltd. continued expanding its automated storage and retrieval system manufacturing capacity to serve growing e-commerce and semiconductor manufacturing demand across Asia.
- 2025: KION Group continued integrating additional autonomous mobile robot product lines into its material handling portfolio following prior acquisitions, broadening its flexible automation offering for warehouse customers.
Automated Material Handling Equipment Market Key Players are:
- Daifuku Co., Ltd.
- Dematic Corporation (KION Group)
- Swisslog Holding AG
- Honeywell Intelligrated
- Murata Machinery, Ltd.
- SSI Schaefer Group
- Vanderlande Industries B.V.
- Siemens AG
- Toyota Industries Corporation
- Beumer Group GmbH & Co. KG
- Jungheinrich AG
- KUKA AG
- Hanwha Corporation
- Hyster-Yale Materials Handling, Inc.
- TGW Logistics Group
- KNAPP AG
- Viastore Systems GmbH
- Fetch Robotics (Zebra Technologies)
- Locus Robotics Corp.
- GreyOrange Pte. Ltd.
Automated Material Handling Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 51.20 Billion |
| Market Size by 2035 | USD 134.26 Billion |
| CAGR | CAGR of 10.12% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Industrial Robots, Autonomous Mobile Robots, Automated Guided Vehicles, Automated Storage & Retrieval Systems, Cranes, Conveyors & Sortation Systems) • By System Type (Unit Load, Bulk Load) • By End-Use Industry (E-commerce & Retail, Automotive, Food & Beverage, Semiconductor & Electronics, Healthcare, Manufacturing, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Daifuku Co., Ltd.; Dematic Corporation (KION Group); Swisslog Holding AG; Honeywell Intelligrated; Murata Machinery, Ltd.; SSI Schaefer Group; Vanderlande Industries B.V.; Siemens AG; Toyota Industries Corporation; Beumer Group GmbH & Co. KG; Jungheinrich AG; KUKA AG; Hanwha Corporation; Hyster-Yale Materials Handling, Inc.; TGW Logistics Group; KNAPP AG; Viastore Systems GmbH; Fetch Robotics (Zebra Technologies); Locus Robotics Corp.; GreyOrange Pte. Ltd. |
Frequently Asked Questions
Leading companies include Daifuku Co., Ltd., Dematic Corporation, Swisslog Holding AG, Honeywell Intelligrated, and Murata Machinery, Ltd., among other major automation equipment manufacturers.
Opportunities include growing semiconductor and electronics manufacturing automation and large-scale bulk-load infrastructure expansion across mining, construction, and agricultural sectors.
Growth is driven by increasing reliance on robotics to address skilled labor shortages and strong e-commerce growth requiring compressed fulfillment timelines.
Conveyors & Sortation Systems dominates by product with approximately 28.60% share.
Asia Pacific is the largest and fastest-growing regional market, led by China, supported by rapid industrialization and large-scale manufacturing and logistics infrastructure expansion.
