
Automotive Brake Valve Market Report Scope & Overview:
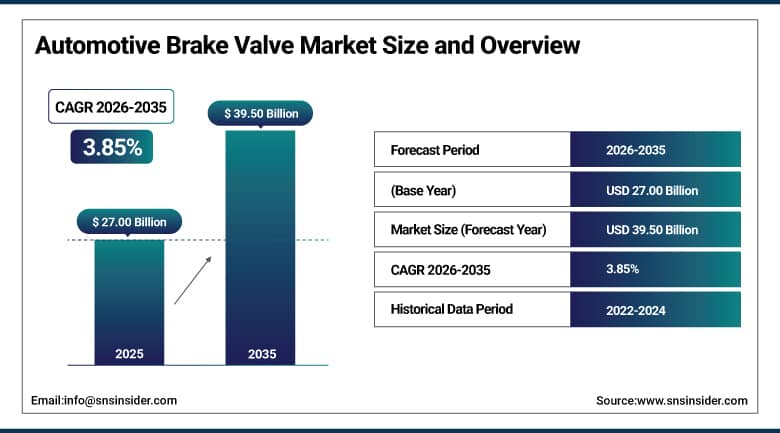
The Automotive Brake Valve Market was valued at USD 27.00 Billion in 2025 and is expected to reach USD 39.50 Billion by 2035, growing at a CAGR of 3.85% from 2026–2035.
Automotive brake valves regulate the hydraulic or pneumatic pressure within the braking system of a vehicle to ensure accurate actuation of brakes through proportioning valves, combination valves, ABS modulator valves, parking brake valves, and quick release valves that collectively ensure predictable braking behavior under any and all driving conditions. With the rising need for improved braking efficiency and safety features in modern automobiles, the increased use of braking systems like ABS, ESC, and regenerative braking has resulted in the rise of brake valve usage. The market will continue to grow on account of stringent safety regulations, the increasing electrification, and brake-by-wire systems that increase the average electronic content of each valve system.
Cummins Drivetrain and Braking Systems, a division of Cummins Inc., announced strategic investments exceeding $190 million in October 2024 to significantly boost production capacity for air disc brakes and rear axles, addressing surging demand for sophisticated braking and axle solutions in the commercial vehicle sector. That kind of capital commitment from an engine manufacturer diversifying into braking hardware reflects how much value has shifted toward the electronic and pneumatic control systems surrounding a truck's brakes, not just the brakes themselves, as commercial vehicle safety regulations and fleet efficiency demands both keep tightening.
To Get More Information On Automotive Brake Valve Market - Request Free Sample Report
Automotive Brake Valve Market Trends
-
Accelerating integration of electronic brake valves enabling individual wheel pressure control and predictive maintenance capability
-
Growing commercial vehicle demand for air disc brakes and associated valve components as fleets modernize aging braking hardware
-
Rising composite material penetration in brake valve construction, reshaping the competitive calculus alongside traditional steel and aluminum components
-
Deeper integration of brake-by-wire platforms replacing purely mechanical valve actuation with electronically controlled systems
-
Increasing development of electropneumatic parking brake valve assemblies enabling automated, software-integrated parking brake activation
-
Growing aftermarket demand driven by rising component complexity requiring specialized replacement and service expertise
U.S. Automotive Brake Valve Market Outlook
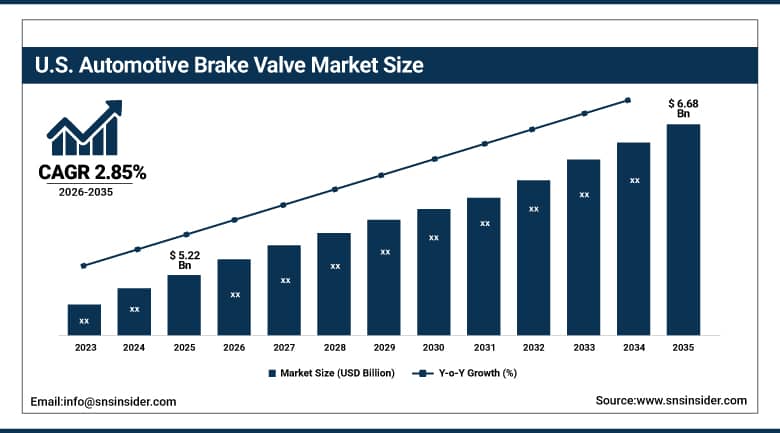
The U.S. Automotive Brake Valve Market was valued at approximately USD 5.22 Billion in 2025 and is expected to reach approximately USD 6.68 Billion by 2035, growing at a CAGR of approximately 2.85%.
The U.S. market benefits from a deep concentration of global brake system manufacturers, stringent federal vehicle safety regulations, and sustained commercial vehicle fleet investment in advanced air disc brake and electronic valve technology. Domestic engine and drivetrain manufacturers continue expanding into braking hardware production capacity to meet surging demand for sophisticated braking and axle solutions across the commercial trucking sector. Growing regulatory emphasis on stability control and automated emergency braking systems continues reinforcing steady replacement and upgrade demand across both passenger and commercial vehicle segments domestically.
ZF CV Systems Europe filed an international patent application in June 2025 for a new method of operating a valve assembly that activates an electropneumatic parking brake at a standstill, a filing that points to where brake valve engineering is actually headed: replacing purely mechanical parking brake actuation with electronically controlled valve systems that can be integrated into a vehicle's broader safety and driver-assistance software. That shift from mechanical to electronic control is exactly the kind of incremental engineering change that doesn't make headlines but steadily raises the average value and complexity of every brake valve a commercial vehicle ships with.
Automotive Brake Valve Market Segment Analysis
-
By Function Type, the Hydraulic segment dominated the Automotive Brake Valve Market with approximately 52.40% share in 2025, while the Electronic segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Material Type, the Steel segment dominated the Automotive Brake Valve Market with approximately 33.00% share in 2025, while the Composite Materials segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Brake Valve Market with approximately 64.60% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Technology, the Conventional Braking Systems segment dominated the Automotive Brake Valve Market with approximately 68.40% share in 2025, while the Brake-by-Wire/Electronic Systems segment is the fastest growing with a CAGR of approximately 9.20%.
-
By Sales Channel, the OEM segment dominated the Automotive Brake Valve Market with approximately 78.22% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 9.50%.
By Function Type, Hydraulic dominates, Electronic grows fastest
The hydraulic valves had the biggest market share in terms of function type in 2025 due to their proven, low-cost solution in the great majority of the global passenger car braking systems, where reliable and predictable brake activation through fluid pressure is provided. Due to such a reliable performance and relatively low cost of production, the hydraulic valves have been retaining their position as the most prominent function type in the general automotive brake valve market.
The electronic valves have been experiencing the fastest growth due to their capacity to ensure the functionality of such functions as wheel by wheel brake activation or predictive maintenance, which is worth a premium price tag and, thus, allows for better profit margins than ordinary hydraulic valves. The increasing adoption of brake-by-wire systems has been intensifying such a high rate of growth.
By Material Type, Steel dominates, Composite Materials grows fastest
Steel accounted for the biggest revenue share in the material type sub-segment in 2025 owing to its ability to resist wear due to scoring, galling, and ablation while retaining the property to resist thermal expansion at the broad temperature range of operation experienced by brake valve components. The large specific heat capacity and thermal conductivity of steel, considering the significant amount of waste heat generated through braking, make it the most used material for brake valves.
Composites are experiencing the fastest growth as the material of choice by manufacturers as they develop superior material types to cope with the dynamics of weight reduction and corrosion resistance without compromising on thermal requirements. The rising adoption rate of composite materials is continuing to alter the competitive landscape of the industry, as discussed above.
By Vehicle Type, Passenger Vehicles dominates, Commercial Vehicles grows fastest
Passenger vehicles dominated the vehicle type segment in 2025 due to the large scale of manufacturing of passenger vehicles compared to commercial vehicles annually, where brake valves were fitted on almost all of the cars manufactured globally. This makes passenger vehicles dominate the vehicle type segment of the entire automotive brake valves industry.
Commercial vehicles are experiencing high growth rates because of the increasing demands of commercial vehicles, where fleet owners keep upgrading their brakes and axles to meet various safety and efficiency standards. The increasing volume of freight transport and investments in modernizing the fleets make the commercial vehicle type segment grow at a higher rate than the other types of vehicles.
By Technology, Conventional Braking Systems dominates, Brake-by-Wire grows fastest
Conventional braking systems held the largest share of the technology segment in 2025, remaining the established, widely deployed standard across the current global vehicle parc that continues generating the majority of brake valve replacement and OEM installation demand. That existing installed base keeps conventional systems the dominant technology category across the broader automotive brake valve market.
Brake-by-wire and electronic systems are growing fastest as accelerating electrification and deeper integration of brake-by-wire platforms continue propelling growth, replacing purely mechanical valve actuation with electronically controlled systems integrated into broader vehicle safety software. That technology shift continues reinforcing this above-average growth trajectory relative to the broader, conventional-system-dominated technology mix.
By Sales Channel, OEM dominates, Aftermarket grows fastest
The OEM segment contributed the majority of automotive brake valve market revenue in 2025, reflecting how brake valves are overwhelmingly factory-installed components specified during vehicle design and assembly rather than purchased separately by consumers after the fact. That deep integration between valve design and overall vehicle braking system engineering keeps OEM channels the dominant sales channel across nearly every brake valve category.
The aftermarket is growing fastest due to rising component complexity, as increasingly sophisticated electronic and brake-by-wire valve systems require specialized replacement parts and service expertise beyond what basic conventional hydraulic valve maintenance once demanded. Growing vehicle parc size and aging vehicle fleets across both developed and emerging markets continue reinforcing this above-average growth trajectory relative to the broader, OEM-dominated sales-channel mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.60% |
|
North America |
United States |
80.60% |
|
Europe |
Germany |
25.00% |
|
Middle East & Africa |
Saudi Arabia |
29.80% |
|
Latin America |
Brazil |
34.60% |
Asia Pacific Automotive Brake Valve Market Insights
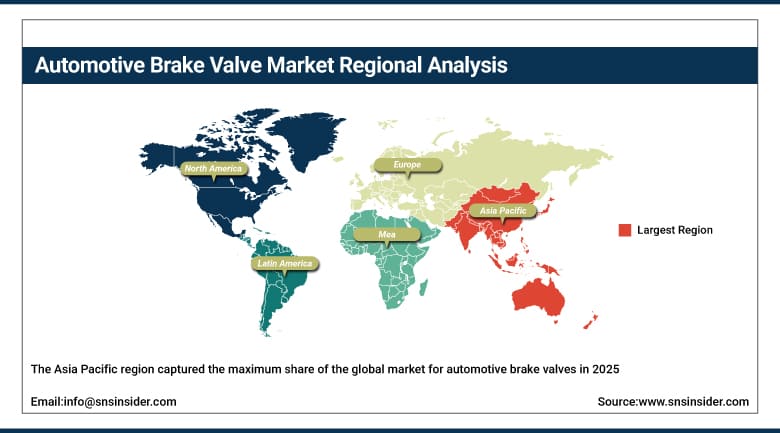
The Asia Pacific region captured the maximum share of the global market for automotive brake valves in 2025, with about 41.37% share and will also have the fastest regional CAGR over the next ten years until 2035. The large-scale production of vehicles in this region drives a strong base demand for automotive brake valves, which are fitted in over one-third of all the vehicles made in this region.
Brake valves manufacturing capacity is getting attracted to India due to its fast-growing automotive manufacturing sector, while Japan and South Korea can be considered technologically advanced and mature regions with electronic valves manufacturing standards already established in them. Southeast Asian countries are following a similar pattern of growth based on vehicle manufacturing activities.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Brake Valve Market Insights
North America represents a substantial automotive brake valve market, with the United States accounting for the large majority of regional demand through its deep concentration of global brake system manufacturers and stringent federal vehicle safety regulations. Sustained commercial vehicle fleet investment in advanced air disc brake and electronic valve technology continues reinforcing this leading position across the region.
Canada contributes additional demand through its own vehicle manufacturing and commercial trucking sector, while Mexico's market continues expanding alongside growing nearshoring-driven automotive manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major brake valve manufacturers typically serving all three markets through shared production networks.
Europe Automotive Brake Valve Market Insights
Europe can be considered an established and highly advanced automobile brake valve market, where Germany is the leader in the region, taking up about 25% of the revenues in the region on account of Germany’s highly advanced and mature automobile manufacturing industry, commercial vehicle manufacturing industry, and focus on vehicle safety and braking systems. The market in Germany keeps growing at a steady rate, owing to constant demand from the highly advanced automobile engineering industry in the country.
UK makes up a significant portion of the revenues in the European market owing to its domestic production of the Jaguar Land Rover and overall application of advanced braking systems. The other major countries making up the revenues in Europe include France and Italy.
MEA & Latin America Automotive Brake Valve Market Insights
The Middle East and Africa account for a relatively small but developing market for automotive brake valves in which Saudi Arabia takes a lead in the demand side due to the extensive investments in infrastructure and expansion of commercial vehicle fleets related to the economic diversification policy of the state. The growth of other countries of this region is highly correlated with the progress of automobile manufacturing and related infrastructure development.
Latin America represents an increasingly developing market where Brazil holds the leading position in the demand side due to the increasing production of automobiles and commercial vehicle fleets modernization. Other countries like Mexico and Argentina generate additional demand due to the growth of the automotive manufacturing sector.
Market Dynamics
Growth Drivers: Stricter safety regulations and vehicle electrification fueling adoption
Stricter safety regulations are one of the clearest forces behind rising automotive brake valve demand, as regulatory bodies worldwide continue tightening requirements around stability control, anti-lock braking, and automated emergency braking systems that all depend on sophisticated valve technology. That regulatory pressure gives the market a demand base that continues expanding regardless of broader vehicle production cycle fluctuations.
Accelerating electrification adds a second major driver, as deeper integration of brake-by-wire platforms and regenerative braking systems continues requiring more sophisticated electronic valve technology than conventional hydraulic systems alone provide. Growing vehicle parc size and demand for precise and reliable braking systems across both luxury cars and rugged commercial trucks continue reinforcing this demand base worldwide.
Restraints: Supply chain volatility and regulatory compliance costs limiting margin stability
Supply chain volatility remains a genuine restraint, since brake valve manufacturers depend on specialized steel, aluminum, and composite material inputs that remain exposed to broader commodity market swings affecting production costs and delivery timelines across the industry. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-valve demand remains steady.
Regulatory compliance costs add a further restraint, as manufacturers face genuine engineering and certification investment navigating varying vehicle safety standards across different jurisdictions simultaneously. That compliance burden falls disproportionately on smaller manufacturers without dedicated regulatory affairs and testing capability built into their operations.
Opportunities: Electronic valve premiumization and brake-by-wire platform expansion opening new growth avenues
Electronic valve premiumization offers manufacturers a genuine path to capturing higher-margin business, since electronic valves enabling individual wheel pressure control and predictive maintenance capability justify premium pricing relative to conventional hydraulic alternatives. Companies that build strong electronic valve engineering capability are positioned to capture disproportionate growth as vehicle electrification and brake-by-wire adoption continue accelerating.
Brake-by-wire platform expansion represents a second significant opportunity, as automakers increasingly replace purely mechanical valve actuation with electronically controlled systems integrated into broader vehicle safety and driver-assistance software. Manufacturers that build genuine brake-by-wire integration expertise are positioned to capture premium pricing from automakers seeking software-integrated braking systems across their expanding electric and autonomous-ready vehicle lineups.
Recent Developments:
-
In June 2025, ZF CV Systems Europe filed an international PCT patent application for a method of operating a valve assembly that activates an electropneumatic parking brake at a standstill.
-
In October 2024, Cummins Drivetrain and Braking Systems announced investments exceeding $190 million to boost production capacity for air disc brakes and rear axles.
-
In 2025, Knorr-Bremse continued expanding its commercial vehicle portfolio, including the SN7 air disc brake and EAC 2.5 electronic air control system, across its global manufacturing network spanning more than 30 countries.
-
In 2025, multiple major brake system manufacturers, including ZF Friedrichshafen through its WABCO brand, continued developing integrated air-management components combining valves, compressors, and electronic braking systems for commercial vehicle applications.
Automotive Brake Valve Market Key Players
-
Robert Bosch GmbH
-
Continental AG
-
ZF Friedrichshafen AG
-
Knorr-Bremse AG
-
Aisin Corporation
-
Akebono Brake Industry Co., Ltd.
-
BorgWarner Inc.
-
Tenneco Inc. (DRiV Motorparts)
-
Brembo S.p.A.
-
Cummins Inc.
-
Hitachi Astemo, Ltd.
-
HL Mando Corporation
-
Nissin Kogyo Co., Ltd.
-
Advics Co., Ltd.
-
Haldex AB
-
Meritor, Inc. (Cummins)
-
Delphi Technologies (BorgWarner)
-
Federal-Mogul (Tenneco)
-
Wabtec Corporation
-
WABCO (ZF)
Automotive Brake Valve Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 27.00 Billion |
| Market Size by 2035 | USD 39.50 Billion |
| CAGR | CAGR of 3.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Function Type (Hydraulic, Pneumatic, Electronic) • by Material Type (Steel, Aluminum, Brass, Composite Materials) • by Vehicle Type (Passenger Vehicles, Commercial Vehicles) • by Technology (Conventional Braking Systems, Brake-by-Wire/Electronic Systems) • by Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Knorr-Bremse AG, Aisin Corporation, Akebono Brake Industry Co., Ltd., BorgWarner Inc., Tenneco Inc. (DRiV Motorparts), Brembo S.p.A., Cummins Inc., Hitachi Astemo, Ltd., HL Mando Corporation, Nissin Kogyo Co., Ltd., Advics Co., Ltd., Haldex AB, Meritor, Inc. (Cummins), Delphi Technologies (BorgWarner), Federal-Mogul (Tenneco), Wabtec Corporation, WABCO (ZF) |
Frequently Asked Questions
Leading companies include Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Knorr-Bremse AG, and Aisin Corporation, among other major braking system and valve technology manufacturers.
Opportunities include electronic valve premiumization enabling individual wheel pressure control and predictive maintenance, and brake-by-wire platform expansion integrated with vehicle safety and driver-assistance software.
Growth is driven by stricter safety regulations requiring sophisticated valve technology, accelerating vehicle electrification, and deeper integration of brake-by-wire platforms.
Hydraulic dominates by function type with approximately 52.40% share, Steel dominates by material type with roughly 33.00% share, Passenger Vehicles dominates by vehicle type with about 64.60% share, and OEM dominates by sales channel with approximately 78.22% share; Electronic, Composite Materials, Commercial Vehicles, and Aftermarket are the fastest-growing segments within their respective categories.
Asia Pacific is the largest regional market with approximately 41.37% share, led by China, and is also the fastest-growing region through 2035.
