
Automotive Data Management Market Report Scope & Overview:
The Automotive Data Management market is witnessing continuous growth owing to the increasing shift toward software-defined vehicle architectures and the constant stream of data modern vehicles generate from GPS location, driver behavior, battery performance, and sensor readings. Moreover, the growth can be attributed to the rising need among OEMs to power over-the-air updates and predictive maintenance, fleet operators to track vehicle utilization and driver safety, and autonomous-vehicle developers to feed enormous training datasets. The automotive data management is the software and services layer that collects, cleans, stores, and routes that data to wherever it is actually useful. Growing adoption of connected fleet technology and expanding electric vehicle production further drive market expansion globally.
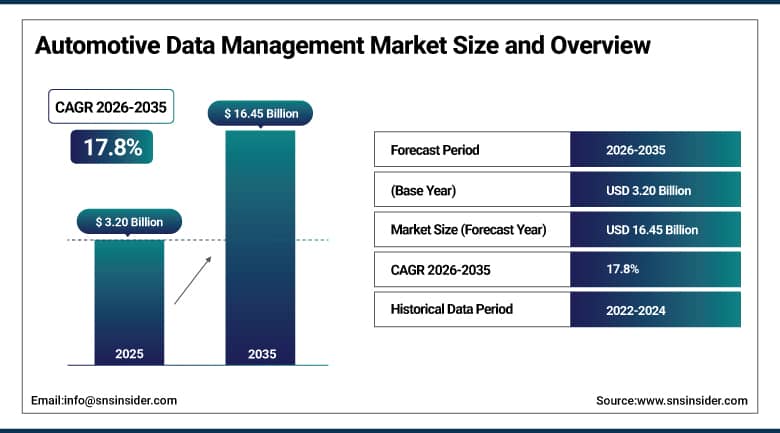
The Automotive Data Management Market was valued at USD 3.20 Billion in 2025 and is expected to reach USD 16.45 Billion by 2035, growing at a CAGR of 17.8% from 2026 to 2035.
In June 2025, Volkswagen, BMW, Bosch, and Continental announced a joint alliance to develop a shared, cross-manufacturer basic software platform, an unusually direct acknowledgment from four major automotive players that the cost and complexity of managing vehicle data and software has outgrown what any single company can efficiently build alone.
To Get More Information On Automotive Data Management Market - Request Free Sample Report
Automotive Data Management Market Trends
-
Software-defined vehicle architectures are pushing more OEMs toward cloud-native data platforms that can support continuous over-the-air updates rather than the fixed, hardware-locked software of older vehicle generations.
-
Unstructured data from cameras, radar, and LiDAR is growing faster than traditional structured telematics data, driven largely by the enormous training datasets autonomous-driving development requires.
-
Fleet operators are consolidating multiple point solutions, telematics, driver scoring, maintenance scheduling, into single integrated data platforms rather than managing several disconnected vendor tools.
-
Automotive cybersecurity requirements are increasingly shaping how data management platforms are built, since regulators in major markets now tie market access to demonstrated cyber-resilience across a vehicle's full data pipeline.
-
Cross-manufacturer software alliances are emerging as OEMs recognize that building and maintaining a full data management stack independently is becoming too costly to justify for all but the very largest players.
Key Market Highlights
|
Market Parameter |
Market Highlight / Data |
Key Growth Driver |
|---|---|---|
|
Largest Component |
Software – 56.4% share in 2025 |
Data management fundamentally runs on platforms that OEMs build competitive advantage on. |
|
Fastest-Growing Component |
Services – 19.6% CAGR |
Smaller OEMs lack in-house data engineering talent and turn to managed services. |
|
Largest Data Type |
Structured – 48.7% share in 2025 |
Mature telematics, GPS, and diagnostic datasets well-integrated into existing enterprise systems. |
|
Fastest-Growing Data Type |
Unstructured – 21.3% CAGR |
Enormous sensor data volumes from cameras, radar, and LiDAR for autonomous training. |
|
Largest Deployment Mode |
Cloud – 61.2% share in 2025 |
Scalability to handle unpredictable and rapidly growing data volumes without own infrastructure. |
|
Fastest-Growing Deployment Mode |
Hybrid – 20.4% CAGR |
Balancing cloud scalability against latency, security, and regulatory requirements near the vehicle. |
|
Largest Solution Type |
Vehicle Telematics – 38.4% share in 2025 |
Foundational connectivity layer that most other automotive data applications build on top of. |
|
Fastest-Growing Solution Type |
Predictive Maintenance & Diagnostics – 21.8% CAGR |
Shift from reactive repair models toward predicting failures before they happen. |
|
Largest Vehicle Type |
Passenger Vehicles – 64.3% share in 2025 |
Overwhelming share of total vehicles on the road and in production relative to others. |
|
Fastest-Growing Vehicle Type |
Electric Vehicles – 24.6% CAGR |
EV-specific data requirements like battery performance monitoring and charging history. |
|
Largest Application |
Automotive Manufacturing – 44.2% share in 2025 |
Broad application across nearly every stage of vehicle development, production, and support. |
|
Fastest-Growing Application |
Autonomous & Self-Driving Development – 26.1% CAGR |
Enormous, carefully managed datasets required to train and validate self-driving models. |
|
Largest Region |
North America – 82.0% share in 2025 (United States) |
Concentration of major OEMs, Tier-1 suppliers, and cloud technology providers. |
|
Fastest-Growing Region |
Asia Pacific – Fastest regional growth |
China's massive scale in electric vehicle production and expanding connected-vehicle ecosystem. |
U.S. Automotive Data Management Market Outlook
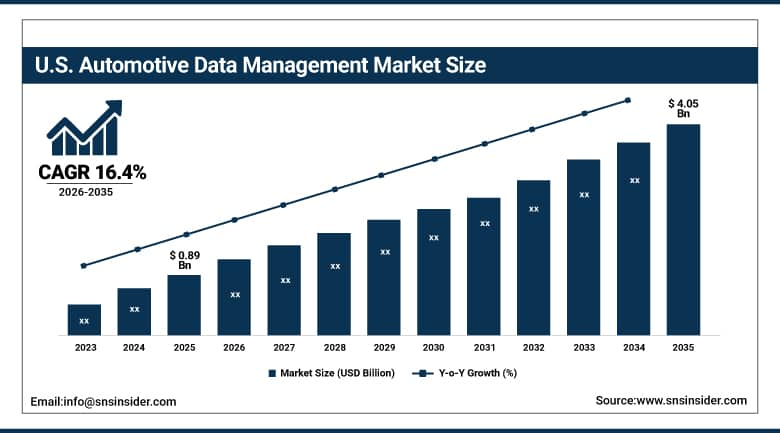
The U.S. Automotive Data Management Market was valued at approximately USD 0.89 Billion in 2025 and is expected to reach approximately USD 4.05 Billion by 2035, growing at a CAGR of approximately 16.4%.
Demand in the United States is driven by a concentration of major OEMs, Tier-1 suppliers, and technology companies that are all racing to build out software-defined vehicle capabilities. Fleet operators and logistics companies add a further layer of steady demand, using data management platforms to optimize routing, monitor driver behavior, and manage vehicle uptime across large commercial fleets. The presence of major cloud providers headquartered in the U.S. also gives domestic automakers a deep bench of infrastructure partners to build on rather than develop equivalent capability in-house.
Amazon Web Services updated its Connected Mobility Solution in 2025, integrating more tightly with AWS IoT FleetWise to simplify intelligent vehicle data collection for automakers building out connected-vehicle programs, part of a broader effort to make automotive-grade cloud infrastructure more accessible to manufacturers who don't want to build it from scratch.
Automotive Data Management Market Segment Analysis
-
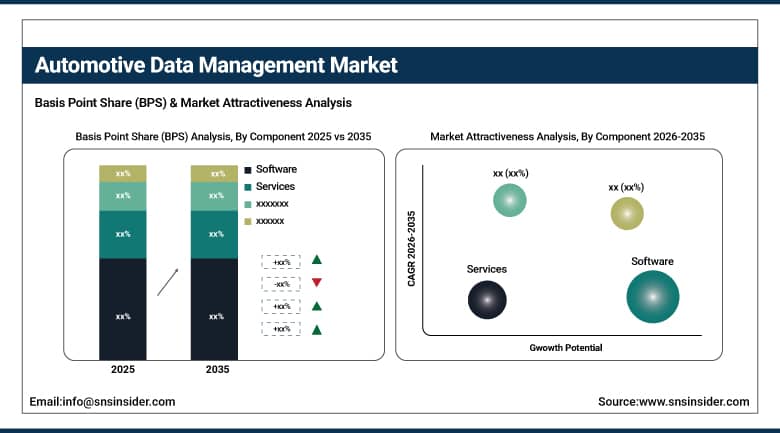
By Component, the Software segment dominated the Automotive Data Management Market with approximately 56.4% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 19.6%.
-
By Data Type, the Structured segment dominated the Automotive Data Management Market with approximately 48.7% share in 2025, while the Unstructured segment is the fastest growing with a CAGR of approximately 21.3%.
-
By Deployment Mode, the Cloud segment dominated the Automotive Data Management Market with approximately 61.2% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 20.4%.
-
By Solution Type, the Vehicle Telematics segment dominated the Automotive Data Management Market with approximately 38.4% share in 2025, while the Predictive Maintenance & Diagnostics segment is the fastest growing with a CAGR of approximately 21.8%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Data Management Market with approximately 64.3% share in 2025, while the Electric Vehicles segment is the fastest growing with a CAGR of approximately 24.6%.
-
By Application, the Automotive Manufacturing segment dominated the Automotive Data Management Market with approximately 44.2% share in 2025, while the Autonomous & Self-Driving Development segment is the fastest growing with a CAGR of approximately 26.1%.
By Component, software dominates, services grows fastest
Software held the largest share of the component segment in 2025, since data management fundamentally runs on platforms, not people, and OEMs increasingly want licensed or proprietary software they can build competitive advantage on top of. Cloud-native data management applications, connected-vehicle platforms, and over-the-air update systems all fall into this category, and their central role in nearly every modern vehicle program keeps software the anchor spending category.
Services are growing fastest as automakers, especially those without large in-house data engineering teams, turn to managed data services, consulting, and system integration to actually stand up and run these platforms. Smaller and mid-size OEMs in particular often lack the specialized talent to build data infrastructure themselves, and that gap is pulling a growing share of spending toward services rather than software licenses alone.
By Data Type, structured dominates, unstructured grows fastest
Structured data accounted for the largest share of the data-type segment in 2025, generated primarily by telematics systems, GPS trackers, and diagnostic tools that produce organized, easily queryable datasets. This data is mature and well-integrated into existing automotive enterprise systems, and established data standards make it comparatively straightforward to collect, store, and analyze compared to newer data types.
Unstructured data is growing fastest as camera, radar, and LiDAR sensors generate enormous volumes of imagery and raw sensor data that autonomous-driving and advanced driver-assistance systems depend on for training and validation. Managing this data is considerably more complex than structured telematics data, requiring specialized storage and processing infrastructure, but the volume it represents is expanding quickly as vehicles ship with more sensors and higher-resolution systems.
By Deployment Mode, cloud dominates, hybrid grows fastest
Cloud deployment led the deployment-mode segment in 2025, offering OEMs and fleet operators the scalability to handle unpredictable and rapidly growing data volumes without building and maintaining their own data center infrastructure. Major cloud providers have built automotive-specific tools and partnerships that make cloud deployment the practical default for most new data management programs.
Hybrid deployment is growing fastest as automakers balance cloud scalability against the latency, security, and regulatory requirements that push certain data processing tasks closer to the vehicle or into on-premise infrastructure. Real-time functions like predictive maintenance alerts or safety-critical processing often need faster response times than a pure cloud round-trip can reliably deliver, pushing more OEMs toward hybrid architectures that combine both approaches.
By Solution Type, vehicle telematics dominates, predictive maintenance & diagnostics grows fastest
Vehicle telematics accounted for the largest solution-type share in 2025, providing the foundational connectivity layer, location tracking, driver behavior monitoring, remote diagnostics, that most other automotive data applications build on top of. Fleet operators in particular rely heavily on telematics platforms to monitor vehicle utilization and improve route efficiency across their operations.
Predictive maintenance and diagnostics are the fastest-growing solution type as OEMs and fleet operators move from reactive repair models toward predicting failures before they happen. This shift can meaningfully reduce vehicle downtime and repair costs, which makes the technology an easier financial case to justify even for fleet operators working with tighter technology budgets than the largest logistics companies.
By Vehicle Type, passenger vehicles dominate, electric vehicles grow fastest
Passenger vehicles held the largest share of the vehicle-type segment in 2025, simply reflecting their overwhelming share of total vehicles on the road and in production relative to commercial and electric vehicles specifically. Every major OEM building consumer passenger vehicles now needs some form of data management capability to support connected services, over-the-air updates, and increasingly expected digital features.
Electric vehicles are growing fastest as EV-specific data requirements, battery performance monitoring, charging history, range prediction, add an entirely new data layer that traditional internal-combustion vehicles never generated. As EV production continues to scale globally, the data management demands specific to battery and charging systems are growing considerably faster than the broader vehicle data management market overall.
By Application, automotive manufacturing dominates, autonomous & self-driving development grows fastest
Automotive manufacturing accounted for the largest application share in 2025, as OEMs use data management platforms across nearly every stage of vehicle development, production, and post-sale support. This broad application across the entire vehicle lifecycle, rather than a single narrow use case, gives manufacturing the largest overall footprint among application categories.
Autonomous and self-driving development is the fastest-growing application as companies working on advanced driver-assistance and full self-driving systems require enormous, carefully managed datasets to train and validate their models. The sheer scale of sensor data these programs generate, combined with the safety-critical need for rigorous data quality and traceability, is pulling significant investment into this application even though it remains a smaller share of total spending than manufacturing overall.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.0% |
|
Europe |
Germany |
26.0% |
|
Asia Pacific |
China |
44.0% |
|
Latin America |
Brazil |
38.0% |
|
Middle East & Africa |
UAE |
31.0% |
North America Automotive Data Management Market Insights
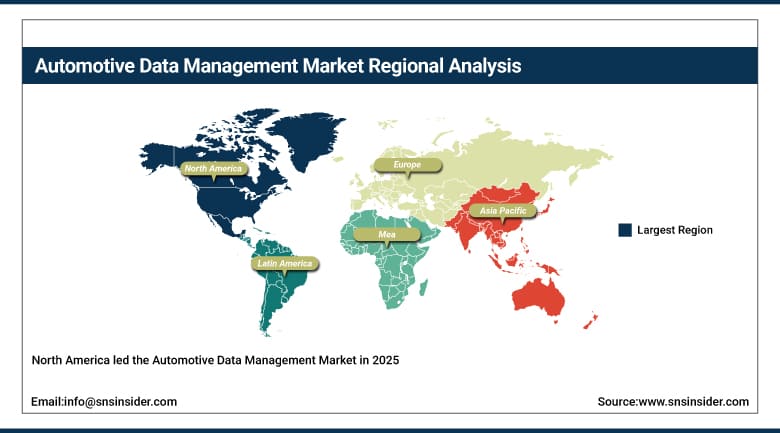
North America led the Automotive Data Management Market in 2025, anchored by the United States' concentration of major OEMs, Tier-1 suppliers, and cloud technology providers all working to build out software-defined vehicle capabilities. The region's deep bench of automotive technology and cloud infrastructure companies gives it a level of ecosystem maturity that most other regions haven't yet matched.
Canada contributes additional demand through its own automotive manufacturing base and growing fleet-technology sector, while Mexico's market is expanding gradually alongside its role as a manufacturing hub for North American vehicle production. Cross-border automotive supply chains tie much of North American demand together, with major suppliers typically serving all three markets through shared technology platforms.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Data Management Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, driven by China's massive scale in electric vehicle production and a rapidly expanding connected-vehicle ecosystem. Rising domestic EV adoption is generating enormous volumes of battery and charging data that Chinese automakers and technology partners are racing to manage effectively.
Japan and South Korea contribute a smaller but more mature segment centered on established automotive technology suppliers, while India's growing automotive manufacturing base is drawing increasing investment in connected-vehicle infrastructure. Southeast Asian markets are following a similar trajectory as regional vehicle production and connectivity infrastructure continue to expand.
Europe Automotive Data Management Market Insights
Europe represents a mature, technology-forward automotive data management market, supported by strict data privacy regulation and a strong base of premium OEMs investing heavily in connected and software-defined vehicle capabilities. Germany anchors regional demand, home to several major automakers and Tier-1 suppliers building out proprietary and shared data management platforms.
The United Kingdom, France, and Sweden contribute meaningful volume as well, each with established automotive technology sectors. EU data protection standards shape how data management platforms are architected across the region more directly than in most other markets, often requiring more rigorous consent, storage, and processing frameworks than automakers need to build elsewhere.
MEA & Latin America Automotive Data Management Market Insights
The Middle East and Africa represent a smaller but developing automotive data management market, with the UAE and Saudi Arabia driving demand through growing fleet and logistics technology adoption tied to broader digital infrastructure investment. South Africa anchors demand across the rest of the continent, supported by a more established automotive assembly and fleet management base than most of its neighbors.
Latin America is seeing steady growth led by Brazil, where expanding vehicle production and a growing logistics and fleet management sector are driving demand for connected-vehicle and telematics platforms. Mexico contributes a meaningful secondary share of regional demand, tied closely to its role as a manufacturing base for North American automotive supply chains.
Growth Drivers: Software-defined vehicle adoption and connected fleet expansion fueling demand
The industry-wide shift toward software-defined vehicles is one of the clearest forces behind rising automotive data management demand, as OEMs need robust data platforms to support continuous over-the-air updates, personalized in-vehicle experiences, and remote diagnostics that older, hardware-locked vehicle architectures never required. That shift is reshaping how automakers budget for technology, moving data management from a supporting function toward a core competitive capability.
Growing adoption of connected fleet management technology adds a second major driver, as logistics and transportation companies increasingly depend on real-time vehicle data to optimize routing, monitor driver safety, and reduce operating costs. Regulatory requirements around emissions monitoring and safety compliance are reinforcing this trend, since accurate reporting increasingly depends on the same data infrastructure fleet operators use for operational optimization.
Restraints: Data privacy regulation and integration complexity limiting deployment speed
Data privacy regulations across major markets, particularly in Europe, add real complexity and cost to building compliant automotive data management platforms, since vehicle data increasingly touches personally identifiable information about drivers and passengers. Navigating different regulatory frameworks across regions can slow deployment timelines for automakers trying to build a single global data architecture.
Integration complexity is a further restraint, since most vehicles generate data from dozens of different sensors and systems built by different suppliers, and unifying that data into a coherent, usable platform is technically difficult even for well-resourced OEMs. Smaller manufacturers without large in-house data engineering teams face a particularly steep climb in building integration capability that larger competitors have already invested years developing.
Opportunities: Autonomous vehicle development and electric vehicle data expansion opening new growth avenues
Continued investment in autonomous vehicle development gives data management providers a large and rapidly growing application, since training and validating self-driving systems depends entirely on carefully managed, high-quality sensor data at a scale most other automotive applications don't require. Companies that build genuine expertise in unstructured data management are positioned to capture a disproportionate share of this growth.
Expanding electric vehicle production offers a second significant opportunity, as battery performance monitoring, charging history, and range prediction create an entirely new category of data management demand that didn't exist for traditional internal-combustion vehicles. Providers that build EV-specific data management expertise now are positioned well as global EV production continues to scale over the next decade.
Recent Developments
-
March 2025: HARMAN International showcased "Ready Connect," the industry's first telematics control unit with built-in satellite communication, developed with NTN provider Skylo, at Mobile World Congress in Barcelona.
-
April 2025: DENSO and Horizon Robotics partnered to co-develop assisted-driving solutions combining Horizon's Journey processing hardware with DENSO's ADAS engineering and vehicle integration capabilities.
-
May 2025: LG Electronics introduced its IoT Non-Terrestrial Networks technology at a 5G automotive event, aimed at extending connected-vehicle data links beyond conventional cellular coverage.
-
2025: Aptiv secured more than USD 4 billion in new automotive business awards focused on expanding data, power, and connectivity architectures, part of a record USD 27 billion in total new business bookings for the year.
Automotive Data Management Companies are:
-
Robert Bosch GmbH
-
Continental AG
-
Denso Corporation
-
Aptiv PLC
-
Harman International Industries
-
SAP SE
-
Oracle Corporation
-
Microsoft Corporation
-
Amazon Web Services, Inc.
-
NetApp, Inc.
-
HERE Technologies
-
LG Electronics Inc.
-
Acerta Analytics Solutions Inc.
Automotive Data Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.20 Billion |
| Market Size by 2035 | USD 16.45 Billion |
| CAGR | CAGR of 17.8% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Software, Services, Hardware) • by Data Type (Structured, Semi-Structured, Unstructured) • by Deployment Mode (Cloud, On-Premise, Hybrid) • by Solution Type (Vehicle Telematics, Fleet Management, Predictive Maintenance & Diagnostics, Data Integration & Migration, Others) • by Vehicle Type (Passenger Vehicles, Commercial Vehicles, Electric Vehicles) • by Application (Automotive Manufacturing, Fleet & Logistics Operators, Aftermarket & Insurance, Autonomous & Self-Driving Development, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Robert Bosch GmbH, Continental AG, Denso Corporation, Aptiv PLC, Harman International Industries, IBM Corporation, SAP SE, Oracle Corporation, Microsoft Corporation, Amazon Web Services, Inc., NetApp, Inc., Teradata Corporation, HERE Technologies, LG Electronics Inc., Acerta Analytics Solutions Inc. |
Frequently Asked Questions
The Automotive Data Management Market is expected to grow at a CAGR of 17.8% from 2026 to 2035.
The Automotive Data Management Market was valued at USD 3.20 Billion in 2025.
The industry-wide shift toward software-defined vehicles and growing adoption of connected fleet management technology across logistics and transportation operators.
Automotive Manufacturing dominated with approximately 44.2% share in 2025, while Autonomous & Self-Driving Development is the fastest growing segment with a CAGR of approximately 26.1%.
North America dominated the Automotive Data Management Market in 2025, while Asia Pacific is the fastest-growing region.
