
Automotive Brake Fluid Market Report Scope & Overview:
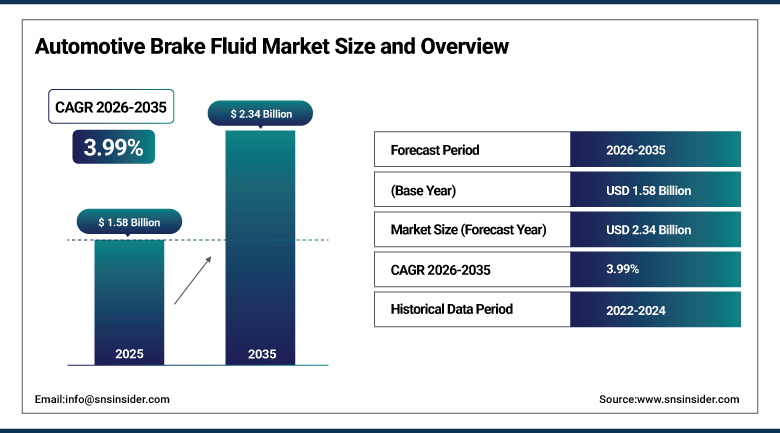
The Automotive Brake Fluid Market was valued at USD 1.58 Billion in 2025 and is expected to reach USD 2.34 Billion by 2035, growing at a CAGR of 3.99% from 2026-2035.
Automotive brake fluid is in high demand owing to rising number of cars, since they act as the vital hydraulic liquid in which the force applied on the brake pedals is transmitted to the brakes at every wheel. The advantages of using brake fluid oils include good lubrication and high boiling points; these are characteristics of a liquid that makes it suitable for usage in brakes when there are very high pressures and temperatures. While structural changes are taking place, the strong growth of vehicle parc in Asia Pacific, coupled with the implementation of antilock braking systems in two-wheelers. Increased registration of new-energy vehicles ensures continued health of original-equipment fills as many electric cars still have hydraulic braking system backups.
In June 2025, India's nationwide anti-lock braking system mandate for all two-wheelers, a regulatory milestone that continues to further widen brake fluid demand across one of the world's largest motorcycle and scooter markets. This mandate reflects a broader global regulatory pattern of extending advanced braking system requirements from passenger vehicles to two-wheelers, a vehicle category that has historically relied on simpler braking technology, and the resulting shift toward hydraulic disc brake systems requiring proper brake fluid specification continues to represent a genuinely significant incremental demand driver for fluid manufacturers serving the region's enormous motorcycle fleet.
To Get more information Automotive Brake Fluid Market - Request Free Sample Report
Automotive Brake Fluid Market Trends
- Rising specification of higher-boiling-point DOT 4 and DOT 5.1 fluids driven by advanced driver-assistance system integration.
- Growing adoption of hydraulic braking systems across two-wheelers amid tightening regional safety regulations.
- Expanding demand for silicone-based DOT 5 fluids in niche applications prioritizing paint protection and moisture resistance.
- Increasing brake fluid fill requirements sustained by electric vehicles retaining hydraulic backup braking systems.
- Rising investment by key market players in technological innovation enhancing braking fluid quality and performance.
U.S. Automotive Brake Fluid Market Outlook
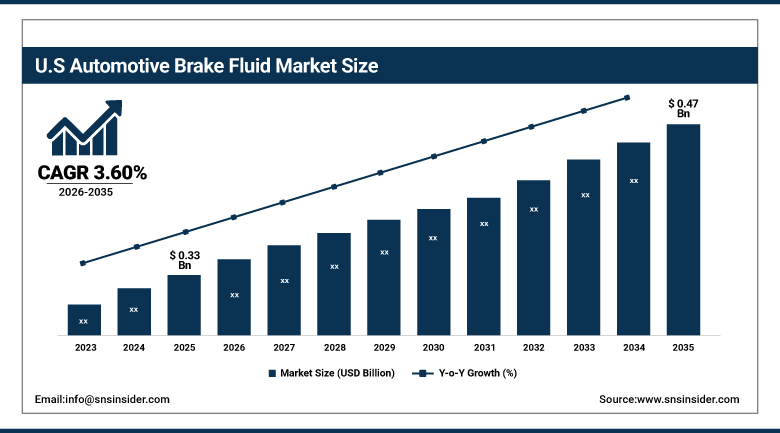
The U.S. Automotive Brake Fluid Market was valued at USD 0.33 Billion in 2025 and is expected to reach USD 0.47 Billion by 2035, growing at a CAGR of 3.60% from 2026-2035.
The U.S. Automotive Brake Fluid Market remains affected by the ongoing push towards better vehicle safety standards, which has resulted in the manufacturing of quality brake fluid meeting certain specifications due to improved domestic braking systems. Road safety government campaigns aimed at making roads safer have been driving both consumers and companies to think about better braking systems; consequently, there is an ongoing need for brake fluids meeting high standards. Increased popularity of advanced driver assistance systems among the domestic new vehicle fleet leads to the development of the DOT 4 and DOT 5.1 brake fluids featuring increased boiling point, thus further boosting the market value, despite the lower growth in terms of volumes compared to other emerging countries.
In April 2026, General Motors reported a recall involving certain ACDelco GMW DOT 3 brake and clutch fluid containers after the product failed to meet Federal Motor Vehicle Safety Standard No. 116 due to visible sediment. This recall involved roughly 40,440 bottles, which received reimbursement from GM for their remaining inventory of these bottles with dealerships and end users. This event underscores the need for strict controls on the quality of brake fluid, especially since the brake fluids must be able to perform under the guidelines set forth by the U.S. government.
Automotive Brake Fluid Market Segment Analysis
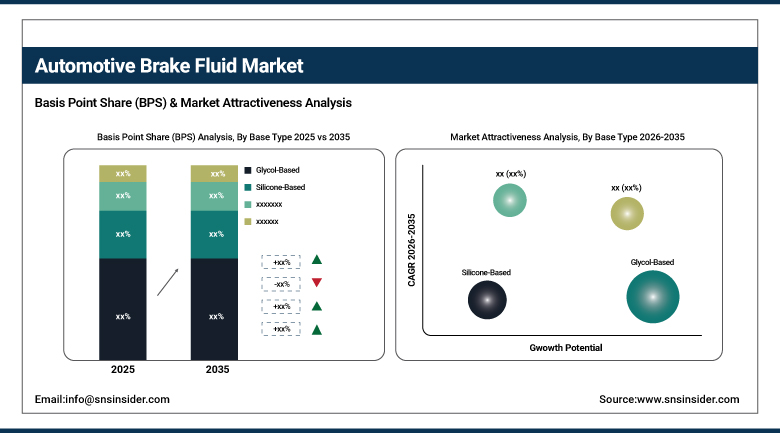
- By Base Type, the Glycol-Based segment dominated the Automotive Brake Fluid Market with approximately 72.60% share in 2025, while the Silicone-Based segment is the fastest growing with a CAGR of approximately 7.60%.
- By Product Type, the DOT 3 segment dominated the Automotive Brake Fluid Market with approximately 54.60% share in 2025, while the DOT 5.1 segment is the fastest growing with a CAGR of approximately 7.40%.
- By Vehicle Type, the Passenger Cars segment dominated the Automotive Brake Fluid Market with approximately 46.60% share in 2025, while the Motorcycles segment is the fastest growing with a CAGR of approximately 6.80%.
- By Sales Channel, the OEM segment dominated the Automotive Brake Fluid Market with approximately 58.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.60%.
By Base Type, Glycol-Based Dominates the Automotive Brake Fluid Market and Silicone-Based Grows Fastest
The glycol-based fluids were the leading segment of demand due to the combination of cost effectiveness, moisture handling properties, and their compatibility with most of the braking parts used in all types of vehicles in the world. Since brake systems have different chemical and thermal requirements, the glycol-based fluids will continue to be the engineering standard in both OEM production requirements and aftermarket servicing requirements, with demand patterns which will continue to resemble those of vehicle manufacturing and maintenance schedules in maintaining the lead of the base type.
Silicone-based fluids represent the fastest-growing base type, serving niche applications where paint protection and moisture resistance are prioritized, particularly across specialty and performance vehicle applications where these specific properties deliver genuine functional advantages over conventional glycol-based alternatives. As margin profiles continue diverging between commodity glycol fluids that compete primarily on scale efficiency and specialty variants that command premium positioning tied to performance certification, silicone-based fluids continue capturing an increasing share of the specialty and performance-oriented segment of overall brake fluid demand.
By Product Type, DOT 3 Dominates the Automotive Brake Fluid Market and DOT 5.1 Grows Fastest
DOT 3 Brake Fluid emerged as the largest product type in terms of market share due to the fact that it forms the base specification among the vast majority of traditional cars and commercial cars which do not demand higher boiling point capabilities. The wide use of DOT 3 Brake Fluid as original equipment manufacture specification in traditional cars as well as the availability of the same in the aftermarket sector makes this product type the largest segment of the overall brake fluids industry.
DOT 5.1 is projected to rise fastest among product type categories, as growing adoption of advanced driver-assistance systems continues pushing automakers to specify this higher-boiling-point formulation across an increasing share of new vehicle production. DOT 5.1's glycol ether base, combined with a boiling point performance that approaches silicone-based DOT 5 specifications while remaining fully compatible with conventional DOT 3 and DOT 4 systems, continues to make this formulation an increasingly attractive specification choice for automakers seeking enhanced braking system performance without requiring a fundamentally different fluid chemistry across their broader vehicle lineup.
By Vehicle Type, Passenger Cars Dominates the Automotive Brake Fluid Market and Motorcycles Grows Fastest
Passenger cars commanded the largest vehicle type share, reflecting the sheer scale of global passenger vehicle production and the consistent brake fluid fill and replacement requirements this vast vehicle population generates across both new vehicle manufacturing and ongoing maintenance service intervals. The scale of passenger vehicles sold globally in the year period of 2020-2023, amounting to approximately 92.72 million, continues to provide the foundation for baseline brake fluid requirements that continue to be relatively resilient to changes in propulsion technologies elsewhere in the automotive parts market space.
Motorcycles remain the fastest-growing segment of vehicles due to the steady introduction of anti-lock braking systems in two-wheelers, driven not only by India’s country-wide adoption of an ABS requirement for all two-wheelers from April 2026 but also resulting in an increasingly wider need for brake fluid from the vehicle category which traditionally used a less complex non-hydraulic system of brakes. Due to global manufacturers’ transition from a non-hydraulic brake system towards a hydraulic disc brake system due to strict regional safety standards, motorcycles are becoming responsible for more and more growth in brake fluid demand despite a smaller share of this market.
By Sales Channel, OEM Dominates the Automotive Brake Fluid Market and Aftermarket Grows Fastest
The OEM sales channel commands the largest share of the market, benefiting from strategic alliances and long-term contracts between brake fluid manufacturers and vehicle producers that continue to ensure steady revenue streams and streamlined integration into new vehicle production across the global automotive manufacturing supply chain. Rising global vehicle production and sales, spanning major manufacturing centers including China, the United States, Japan, and India, continue to sustain substantial OEM channel demand as automakers require reliable, certified brake fluid supply for every vehicle rolling off their production lines.
Aftermarket sales have been identified as the fastest-growing sales channel due to increased consumer awareness and importance of vehicle maintenance, as well as the realization that replacing brake fluid periodically is a vital and affordable process that impacts the efficiency of the braking system. E-commerce sales are also growing at a fast pace as customers and service centers alike purchase brake fluid online; therefore, the increase in visibility, competitive prices, and worldwide presence are contributing significantly to the impressive growth in this sales channel and are placing it in a position of outperforming other sales channels in terms of growth potential.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Automotive Brake Fluid Market Insights
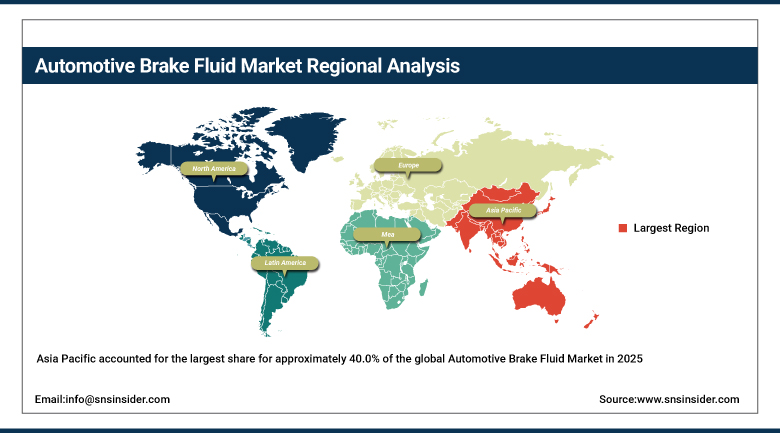
Asia Pacific accounted for the largest share for approximately 40.0% of the global Automotive Brake Fluid Market in 2025, and the region is also expected to post the fastest growth rate with a CAGR of approximately 4.8% from 2026 to 2035. This is driven by robust vehicle-parc expansion and the ongoing rollout of anti-lock braking systems across two-wheelers that continue supporting near-term growth across the region's enormous motorcycle and passenger vehicle fleet. China, Japan, and India continued registering strong vehicle production growth in recent years, with China and Japan production posting particularly strong year-over-year gains, continuing to anchor regional brake fluid demand across both established and emerging vehicle manufacturing hubs.
The increasing number of registrations of new-energy vehicles in China, which went up to 11.25 million units in 2024, ensures continued high levels of OE filling volumes owing to the fact that most of the battery electric vehicles use hydraulic brakes as redundant options despite the trend of using electrified drivetrains. The countrywide ABS regulation for all two wheelers in India, which is to come into effect from April 2026, continues to further expand demand in the region on account of the transition towards hydraulic disc brakes in the country's huge motor cycle and scooter fleet.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Brake Fluid Market Insights
North America represents a significant share of the global Automotive Brake Fluid Market, anchored by the United States' substantial vehicle production base and increasing emphasis on vehicle safety standards and regulations that continue prompting manufacturers to produce high-quality brake fluids meeting specific performance criteria. The region's mature vehicle fleet and well-established maintenance culture continue to sustain steady aftermarket brake fluid demand alongside OEM fill requirements across new vehicle production.
Canada and Mexico contribute additional regional demand as their own vehicle manufacturing and consumer markets continue to develop. Continued domestic investment in higher-performance fluid formulations, driven by growing ADAS adoption across the region's new vehicle fleet, is expected to sustain steady regional growth through the forecast period, even as the region trails Asia Pacific in both absolute market size and growth pace.
Europe Automotive Brake Fluid Market Insights
Europe represents a significant share of the global Automotive Brake Fluid Market, anchored by Germany's substantial automotive manufacturing base and the region's stringent vehicle safety regulatory framework. The region's well-established premium and performance vehicle segments continue sustaining demand for higher-specification DOT 4 and DOT 5.1 fluid formulations that meet the exacting performance requirements these vehicle categories typically specify.
France, Italy, and other major European automotive markets contribute steady regional demand as national vehicle manufacturers continue extending advanced braking system adoption across their vehicle lineups. Global automotive regulations tightening, particularly around emissions and sustainability, continue reinforcing the region's brake fluid market outlook, with continuous innovation and growth expected as manufacturers balance environmental compliance requirements alongside braking performance specifications.
MEA & Latin America Automotive Brake Fluid Market Insights
The Middle East & Africa market is supported by growing vehicle ownership and increasing automotive safety awareness across the United Arab Emirates and Saudi Arabia, where regional governments continue investing in broader automotive safety infrastructure and regulatory frameworks. Regional vehicle fleets continue gradually adopting more sophisticated braking system technology as consumer safety expectations continue rising alongside broader economic development.
Latin America's market is led by Brazil, where a substantial domestic vehicle manufacturing and consumer sector sustains steady demand for automotive brake fluid. Mexico is contributing growth as regional vehicle manufacturing continues to expand, with adoption across the broader region concentrated among both OEM fitment and a growing aftermarket maintenance sector serving the region's expanding vehicle fleet.
Growth Drivers: Rising Vehicle Production and Advanced Braking System Adoption
The rising cases of road accidents and stringent government regulations aimed toward bolstering safety on roads represent the primary driver of Automotive Brake Fluid Market growth, as regulatory bodies worldwide continue mandating advanced braking system technology across an expanding range of vehicle categories, from passenger cars through commercial vehicles and increasingly two-wheelers. Rising traffic congestion and rising demand for automobiles with smooth braking systems continue reinforcing sustained baseline market demand as global vehicle production and ownership continue expanding across both established and emerging automotive markets.
Growing adoption of advanced driver-assistance systems represents a second major growth driver, as increasing ADAS integration continues pushing automakers toward higher-boiling-point DOT 4 and DOT 5.1 fluid specification across an expanding share of new vehicle production. Technological innovations and rising investments by key automotive market players to enhance the braking quality of automobiles continue serving as key trends guiding sustained industry growth, as manufacturers race to meet increasingly sophisticated performance and safety certification requirements.
Restraints: Extended Fluid Service Intervals and Electric Vehicle Propulsion Shift
Extended fluid service intervals represent a meaningful restraint on market growth, as continued improvements in brake fluid formulation quality and moisture resistance continue extending the recommended replacement interval for many modern vehicles, potentially reducing the frequency of aftermarket fluid replacement purchases relative to older vehicle generations requiring more frequent maintenance.
The broader shift toward electric vehicle propulsion represents a further restraint, as continued advancement in regenerative braking technology across battery electric vehicles could eventually reduce reliance on conventional hydraulic friction braking for routine deceleration, even though most current-generation battery electric vehicles continue retaining hydraulic backup braking systems for redundancy and emergency stopping performance.
Opportunities: Two-Wheeler Hydraulic Braking Expansion and Premium Formulation Development
Continued expansion of hydraulic braking systems across two-wheelers represents a substantial opportunity, as manufacturers that can successfully position their brake fluid formulations to serve this rapidly expanding vehicle category, particularly across markets implementing new ABS mandates, are positioned to capture significant incremental demand from a vehicle segment that has historically represented minimal brake fluid consumption.
The continued development of premium, higher-performance fluid formulations offers a further substantial avenue for growth, as manufacturers that can deliver genuinely improved boiling point performance and moisture resistance are positioned to capture demand from automakers increasingly specifying DOT 4 and DOT 5.1 fluids to support advanced driver-assistance system integration across their broader vehicle lineups.
Recent Developments
- 2026: Castrol continued supplying DOT 4 brake fluids designed for high-temperature performance, moisture resistance, corrosion protection, and reliable operation across modern passenger-vehicle braking systems.
- 2026: Valvoline expanded its automotive-service business during 2026, while its broader lubricant portfolio and growing service-center network strengthened aftermarket distribution opportunities for automotive maintenance fluids.
- 2026: ExxonMobil continued developing advanced synthetic fluid technologies for electrified vehicles, emphasizing low-temperature fluidity, thermal stability, and long-drain performance relevant to next-generation automotive fluid applications.
Automotive Brake Fluid Companies are:
- BASF SE
- Exxon Mobil Corporation
- BP plc (Castrol)
- Valvoline Inc.
- Motul S.A.
- Prestone Products Corporation
- Shell plc
- TotalEnergies SE
- CRC Industries, Inc.
- ATE (Continental AG)
- ENEOS Corporation
- Idemitsu Kosan Co., Ltd.
- Fuchs Petrolub SE
- Chevron Corporation
- Phillips 66 Company
- Amsoil Inc.
- Liqui Moly GmbH
- Wagner Brake (Tenneco)
- ZF Friedrichshafen AG (TRW)
- Zecol Inc.
Automotive Brake Fluid Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.58 Billion |
| Market Size by 2035 | USD 2.34 Billion |
| CAGR | CAGR of 3.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Base Type (Glycol-Based, Silicone-Based, Mineral Oil-Based, Others) • By Product Type/DOT Classification (DOT 3, DOT 4, DOT 5, DOT 5.1) • By Vehicle Type (Passenger Cars, Commercial Vehicles, Motorcycles) • By Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Exxon Mobil Corporation, BP plc (Castrol), Valvoline Inc., Motul S.A., Prestone Products Corporation, Shell plc, TotalEnergies SE, CRC Industries, Inc., ATE (Continental AG), ENEOS Corporation, Idemitsu Kosan Co., Ltd., Fuchs Petrolub SE, Chevron Corporation, Phillips 66 Company, Amsoil Inc., Liqui Moly GmbH, Wagner Brake (Tenneco), ZF Friedrichshafen AG (TRW), Zecol Inc. |
Frequently Asked Questions
Key players include BASF SE, Exxon Mobil Corporation, BP plc, Valvoline Inc., Motul S.A., Shell plc, and TotalEnergies SE, among other lubricant and fluid manufacturers.
Continued expansion of hydraulic braking systems across two-wheelers and continued development of premium, higher-performance fluid formulations represent the primary opportunities.
Growth is primarily driven by rising cases of road accidents and stringent government regulations combined with growing adoption of advanced driver-assistance systems.
By Base Type, Glycol-Based dominated the market with approximately 72.60% share in 2025, reflecting its balance of cost efficiency, moisture management, and component compatibility.
Asia Pacific dominated the market in 2025, driven by robust vehicle-parc expansion and the ongoing rollout of anti-lock braking systems across two-wheelers.
