
Automotive Electronics Sensor Aftermarket Market Report Scope & Overview:
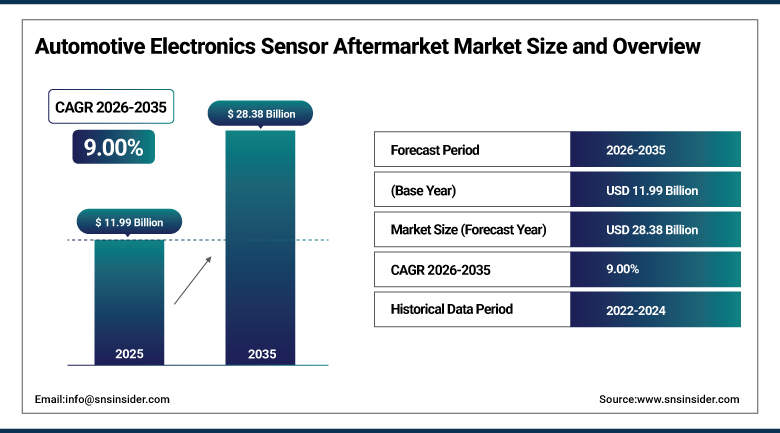
The Automotive Electronics Sensor Aftermarket Market was valued at USD 11.99 Billion in 2025 and is expected to reach USD 28.38 Billion by 2035, growing at a CAGR of 9.00% from 2026-2035.
The automotive electronics sensor aftermarket covers the replacement sensors, wholesalers, retailers, and service centers that keep vehicles already on the road running safely once original components wear out or fail. As vehicles carry more electronic sensors than ever, spanning oxygen sensors, wheel speed sensors for anti-lock braking, tire pressure monitoring sensors, and a growing range of ADAS-related cameras and radar units, the pool of components eventually needing replacement continues to expand alongside vehicle electronic content itself. Growth is supported by a rising global vehicle parc, increasing average vehicle age in mature markets, and regulatory mandates such as mandatory tire pressure monitoring that create predictable, recurring replacement cycles. Distribution is shifting as online retail and direct-to-consumer channels compete with traditional auto parts stores, while independent repair shops and dealership service centers both rely on a steady supply of replacement sensors.
In 2026, Niterra expanded its automotive sensor portfolio and aftermarket application coverage, strengthening its position in engine-management and emissions-control replacement components. The company’s sensing technologies address applications including oxygen, exhaust-gas temperature, pressure, and other parameters required for accurate engine operation and emissions monitoring. The expanded coverage supports repair and maintenance requirements for modern passenger and commercial vehicles, where sensor replacement is increasingly important as vehicles age. Niterra’s aftermarket strategy also strengthens availability of electronically controlled components through distributors and automotive service channels across international replacement markets.
To Get more information Automotive Electronics Sensor Aftermarket Market - Request Free Sample Report
Automotive Electronics Sensor Aftermarket Market Trends
- Rising replacement demand for tire pressure monitoring sensors as mandated systems age across the vehicle parc.
- Growing availability of dual-frequency, multi-fit programmable sensors covering a wider range of vehicle applications.
- Expanding online distribution disrupting traditional auto parts store and wholesale distributor channels.
- Increasing average vehicle age in mature markets extending the population of vehicles needing sensor replacement.
- Rising complexity of ADAS-related sensor replacement requiring recalibration alongside physical part swaps.
U.S. Automotive Electronics Sensor Aftermarket Market Overview
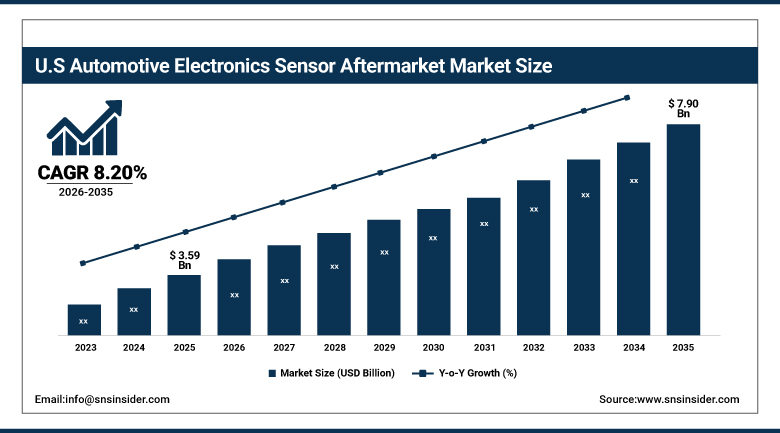
The U.S. Automotive Electronics Sensor Aftermarket Market was valued at USD 3.59 Billion in 2025 and is expected to reach USD 7.90 Billion by 2035, growing at a CAGR of 8.20% from 2026-2035.
The U.S. Automotive Electronics Sensor Aftermarket Market benefits from the presence of the world’s biggest car parc, an increase in the average age of cars, which keep extending far past a decade for a large proportion of registered cars, and a well-established distribution channel of nationwide and regional auto spare parts stores, wholesale distributors, and independent repair facilities. The tire pressure monitoring system regulations will continue to provide a consistent replacement business as the initial sensors will start running out of batteries, which last between seven and ten years. Leading manufacturers are continuing to develop their products and production capacity for this business, while increasing complexity of ADAS sensors will require not only replacement but electronic calibration as well.
In 2025, Standard Motor Products, headquartered in Long Island City, New York, operated five U.S. manufacturing facilities supplying vehicle control sensors, actuators, and ignition components to major U.S. aftermarket retailers and wholesale distributors, while reporting adjusted EBITDA growth from USD 140.1 million in 2024 to USD 200.9 million in 2025.
Automotive Electronics Sensor Aftermarket Market Segment Analysis
- By Sensor Type, the Oxygen/O2 Sensors segment dominated the market with a 28.60% share in 2025, while the TPMS Sensors segment is the fastest growing with a CAGR of 10.60% during 2026-2035.
- By Vehicle Type, the Passenger Cars segment dominated the market with a 64.60% share in 2025, while the Heavy Commercial Vehicles segment is the fastest growing with a CAGR of 9.80% during 2026-2035.
- By Application, the Powertrain & Engine Management segment dominated the Automotive Electronics Sensor Aftermarket Market with approximately 34.10% share in 2025, while the Safety & ADAS segment is the fastest growing with an estimated CAGR of 11.20% during 2026–2035.
- By Vehicle Age, the Above 10 Years segment dominated the market with a 42.60% share in 2025, while the 5-10 Years segment is the fastest growing with a CAGR of 9.60% during 2026-2035.
- By Distribution Channel, the Retail/Auto Parts Stores segment dominated the market with a 48.60% share in 2025, while the Online segment is the fastest growing with a CAGR of 10.80% during 2026-2035.
By Sensor Type, Oxygen/O2 Sensors Dominates the Market and TPMS Sensors Grows Fastest
Oxygen / O2 Sensors had the dominating share of the market in 2025 due to the vital importance of this type of sensor for engine control and fuel-air mixture regulation. Gradual degradation of this type of sensor occurs during long-term driving of the car and results in the regular necessity to change them. The wide application of this type of sensor in gasoline and diesel cars along with emissions regulations and necessity of fuel economy ensures constant demand on the aftermarket.
TPMS sensors are projected to be the fastest-growing sensor type over the forecast period, supported by increasing adoption of tire pressure monitoring systems across passenger and commercial vehicles. Regulatory requirements in major automotive markets have expanded the installed base of TPMS-equipped vehicles, creating a growing replacement opportunity as sensors age. Internal batteries typically have a service life of approximately seven to ten years, resulting in periodic replacement requirements. Increasing consumer awareness of tire safety, vehicle maintenance, and fuel efficiency is further supporting demand for TPMS sensors across the automotive electronics aftermarket.
By Vehicle Type, Passenger Cars Dominates the Market and Heavy Commercial Vehicles Grows Fastest
Passenger Cars continued to lead the segment in 2025, mainly because they have a considerably larger installed base of vehicles globally than commercial vehicles. Modern passenger vehicles also contain many electronic sensors for managing operations such as engine operation, braking systems, safety, driver assistance, emissions management, and other connectivity functionalities. In old age, there is always a need for replacement due to the wear and tear of these sensors, system failures, and also because of accidents. The increased average age of vehicles in some of the mature economies has resulted in even more opportunities for replacement.
Heavy commercial vehicles are projected to be the fastest-growing vehicle type over the forecast period, supported by increasing integration of electronic safety, braking, emissions, and telematics systems. Regulatory requirements for advanced safety technologies, including electronic stability control and automatic emergency braking, are increasing sensor content in newer heavy-duty vehicles. At the same time, expanding freight transportation and e-commerce activity are increasing vehicle utilization and operating mileage. Higher utilization contributes to component wear and replacement requirements, while growing adoption of electronically controlled vehicle systems creates additional demand for replacement sensors across the heavy commercial vehicle aftermarket.
By Application, Above 10 Years Dominates the Market and 5-10 Years Grows Fastest
The Powertrain & Engine Management category had the largest revenue share of the Automotive Electronics Sensors Aftermarket Market in 2025, driven by the already existing fleet of cars, which needs replacement sensors in order to maintain engine performance, fuel efficiency, emissions management, and monitoring of the drive train. Oxygen sensors, temperature sensors, pressure sensors, position sensors, and speed sensors are commonly found in both regular vehicles and hybrids and create ongoing aftermarket replacement demand as cars age. Aging car fleets, emission standards, and maintenance of fuel efficiency are contributing to the continuing replacement trend.
The safety & ADAS category is projected to witness the highest growth rate in the automotive electronics sensor aftermarket market from 2026 to 2035, owing to the growing number of vehicles fitted with advanced driver assistance systems. Sensors based on radar technology, ultrasonic technology, camera technology, wheel speed sensor, and others may need replacement or recalibration after accidents, windshield replacement, bumper repair, and other reasons. Rising preference for adaptive cruise control, automatic emergency braking system, lane assist, blind spot detection, and parking assistance systems is creating opportunities for after sales services.
By Vehicle Age, Above 10 Years Dominates the Market and 5-10 Years Grows Fastest
Vehicles above 10 years old dominated the market in 2025, reflecting the higher probability of electronic sensor replacement as vehicles accumulate mileage and components approach the end of their service lives. Older vehicles commonly require replacement of oxygen, wheel-speed, temperature, pressure, position, and other sensors affected by prolonged exposure to heat, vibration, contaminants, and operating cycles. Increasing vehicle retention periods are also expanding the older vehicle parc in several markets. Consequently, the substantial installed base of aging vehicles continues to generate recurring maintenance and replacement requirements for automotive electronic sensors.
The 5–10 year vehicle age category is projected to be the fastest-growing segment over the forecast period, supported by the increasing number of vehicles transitioning into the stage where electronic sensor replacements become more frequent. Due to increased owner ship tenure and better vehicle quality, older vehicles are remaining on the roads for longer periods, leading to growth in this age group. At this stage of vehicle life, there is potential for parts like TPMS sensors, oxygen sensors, wheel speed sensors, and other kinds of pressure/temperature sensors to be ready for replacement.
By Distribution Channel, Retail/Auto Parts Stores Dominates the Market and Online Grows Fastest
Retail and auto parts stores had an edge in the market owing to their large network coverage, instant product availability, and their existing ties with repair shops as well as private vehicle owners. Consumers tend to use them for the purchase of sensors due to the fact that sensors need precise fitment in accordance with the vehicle they will be used in. Both national and regional auto parts retailers keep a large range of commonly available types of sensors as well as various vehicle types in stock.
Online distribution channel is expected to witness the fastest growth during the forecast period due to greater consumer acceptance towards online automotive parts buying and advancements in automotive part identification for individual vehicles. With more online sellers offering fitment database, VIN checker, compatibility filters, specifications and reviews for the product, it makes it easier for the buyer to choose the right replacement sensor. Convenience offered through comparisons of different products along with home deliveries and wide availability of products is driving online sales of these components. These advantages are supporting continued migration of automotive electronics sensor aftermarket transactions toward online channels.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
86.60% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
38.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Automotive Electronics Sensor Aftermarket Market Insights
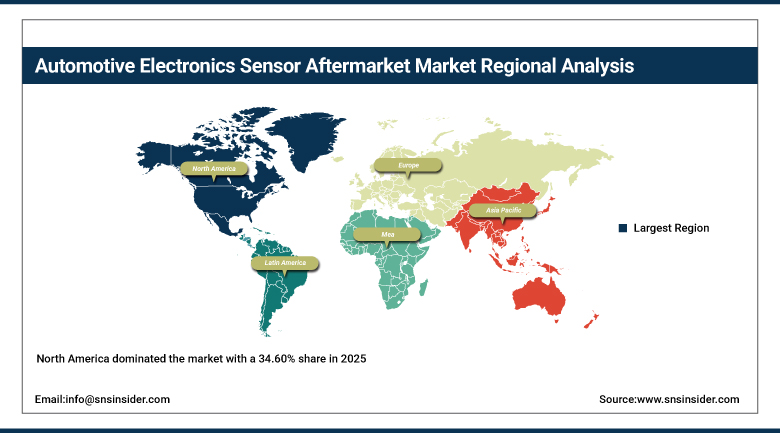
North America dominated the market with a 34.60% share in 2025. A large, ageing vehicle parc, well-established national auto parts retail and wholesale distribution networks, and mandatory tire pressure monitoring requirements continue to anchor this leadership position. The United States in particular sustains substantial recurring demand given its combination of vehicle volume and average fleet age.
Canada contributes additional regional demand through its own vehicle parc and cold-climate conditions that can accelerate certain sensor wear. Continued growth in e-commerce parts distribution and rising average vehicle age are expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Electronics Sensor Aftermarket Market Insights
Asia Pacific is projected to be the fastest-growing region at a CAGR of approximately 8.89% over the forecast period. A rapidly expanding vehicle parc, growing vehicle electronic content across newer models, and an increasingly ageing population of vehicles in more mature regional markets continue to accelerate demand for aftermarket sensor replacement across the region.
China anchors regional demand through its position as the world's largest vehicle market, with a growing share of vehicles now old enough to require sensor replacement. India's rapidly expanding vehicle parc contributes meaningful additional regional growth, while Japan and South Korea add mature, technology-oriented aftermarket demand as vehicle electronic content continues to rise.
Europe Automotive Electronics Sensor Aftermarket Market Insights
Europe holds a meaningful share of the global market, supported by a large, well-maintained vehicle parc and stringent vehicle inspection requirements that often identify failed or degraded sensors requiring replacement. Germany anchors regional demand through its substantial vehicle fleet and strong aftermarket parts distribution network.
Demand from the UK, France, and Italy is expected to be more consistent due to the impact that national vehicle inspection requirements have had on sensor replacement activities. Regional environmental regulations will continue to strengthen demand for operational emissions-related sensors, which include oxygen sensors.
MEA & Latin America Automotive Electronics Sensor Aftermarket Market Insights
The Middle East & Africa region is supported by a growing vehicle parc and expanding automotive aftermarket infrastructure across the United Arab Emirates and Saudi Arabia, where rising vehicle ownership continues to widen the base of vehicles eventually requiring sensor replacement.
Latin America is anchored by Brazil, where a substantial domestic vehicle parc sustains steady aftermarket sensor demand. Mexico contributes further incremental growth as regional vehicle ownership continues to expand alongside its integration into North American automotive supply chains.
Market Dynamics
Growth Drivers: Ageing Vehicle Parc and Rising Sensor Content
The combination of an increase in the worldwide vehicle parc along with a rise in the average age of vehicles constitutes the major factor driving growth. With vehicles being used for longer periods, especially in developed countries, whereby the lifespan is continually increasing, there is an increase in the number of cars whose original sensors have worn out and need replacement.
Rising sensor content per vehicle represents a second major driver, as modern vehicles carry substantially more electronic sensors than older models, from basic engine management sensors through increasingly common ADAS-related cameras and radar units. Regulatory mandates such as mandatory tire pressure monitoring further reinforce this trend by creating predictable, recurring replacement cycles tied to sensor battery life.
Restraints: Counterfeit Parts and Recalibration Complexity
Counterfeit and substandard replacement sensors remain a genuine restraint, as lower-cost, non-qualified components entering the aftermarket can deliver inconsistent performance or premature failure, undermining consumer confidence and creating warranty and liability exposure for both installers and legitimate parts suppliers.
Growing recalibration complexity for ADAS-related sensors presents a further restraint, as replacing certain cameras and radar units increasingly requires specialised calibration equipment and trained technicians, adding cost and complexity relative to straightforward mechanical sensor swaps that independent repair shops have historically performed without specialised tooling.
Opportunities: E-Commerce Expansion and ADAS Sensor Growth
Continued expansion of e-commerce distribution represents a substantial opportunity, as suppliers that can provide reliable fitment data, competitive pricing, and fast delivery are positioned to capture demand from both professional installers and increasingly confident do-it-yourself consumers purchasing parts online.
The opportunities provided by the increasing demand for replacements of the sensors used in ADAS are additional ways that companies can grow, considering that cars with ADAS will have to be serviced due to collisions and need replacements of their cameras, radars, and ultrasonic sensors as they become older and enter the aftermarket stage.
Recent Developments:
- 2026: Bosch expanded its commercial-vehicle aftermarket portfolio at Automechanika, adding new products and program extensions while strengthening diagnostic and workshop solutions for current vehicle generations.
- 2026: DENSO expanded its aftermarket engine-management range with new exhaust-gas-temperature sensor applications, alongside additional diesel injectors and repair components for its service network.
- 2026: Continental developed sensing technology that directly measures rotor temperature in permanent-magnet synchronous motors, supporting improved monitoring of electric-vehicle powertrain operating conditions.
Automotive Electronics Sensor Aftermarket Market Key Players are:
- Robert Bosch GmbH
- Denso Corporation
- Continental AG
- Delphi Technologies (BorgWarner)
- NGK Spark Plug Co., Ltd. (NITERA)
- Standard Motor Products, Inc.
- Sensata Technologies Holding plc
- Hella GmbH & Co. KGaA (Forvia)
- Valeo SE
- Dorman Products, Inc.
- ACDelco (General Motors)
- ZF Friedrichshafen AG
- Walker Products, Inc.
- MotoRad
- Autel Intelligent Technology Corp.
- Schrader (Sensata)
- Pacific Industrial Co., Ltd.
- Huf Hulsbeck & Furst GmbH & Co. KG
- Alligator Ventilfabrik GmbH
- Nissens A/S
Automotive Electronics Sensor Aftermarket Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.99 Billion |
| Market Size by 2035 | USD 28.38 Billion |
| CAGR | CAGR of 9.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Sensor Type (Oxygen/O2 Sensors, ABS/Wheel Speed Sensors, TPMS Sensors, Temperature Sensors, Pressure Sensors, Position Sensors, Inertial Sensors, Others) • By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles) • By Application (Powertrain & Engine Management, Safety & ADAS, Chassis & Braking, Exhaust & Emission Control, Telematics & Connectivity, Battery Management & Thermal Management, Others) • By Vehicle Age (Above 10 Years, 5-10 Years, Below 5 Years) • By Distribution Channel (Retail/Auto Parts Stores, Online, Authorized Service Centers, Independent Repair & Service Shops, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Denso Corporation, Continental AG, Delphi Technologies (BorgWarner), NGK Spark Plug Co., Ltd. (NITERA), Standard Motor Products, Inc., Sensata Technologies Holding plc, Hella GmbH & Co. KGaA (Forvia), Valeo SE, Dorman Products, Inc., ACDelco (General Motors), ZF Friedrichshafen AG, Walker Products, Inc., MotoRad, Autel Intelligent Technology Corp., Schrader (Sensata), Pacific Industrial Co., Ltd., Huf Hulsbeck & Furst GmbH & Co. KG, Alligator Ventilfabrik GmbH, Nissens A/S |
Frequently Asked Questions
Key players include Robert Bosch GmbH, Denso Corporation, Continental AG, Standard Motor Products, Inc., Sensata Technologies Holding plc, and Valeo SE, among other aftermarket parts suppliers.
Continued expansion of e-commerce distribution and growth in ADAS-related sensor replacement represent the primary opportunities for suppliers.
Growth is primarily driven by a rising global vehicle parc combined with increasing average vehicle age, alongside rising sensor content per vehicle.
By Sensor Type, Oxygen/O2 Sensors dominated the market with a 28.60% share in 2025, reflecting their predictable wear cycle and requirement for emissions compliance.
North America dominated the market with a 34.60% share in 2025, supported by a large, ageing vehicle parc and established aftermarket distribution networks.
