
Automotive Exhaust Emission Control Device Market Report Scope & Overview:
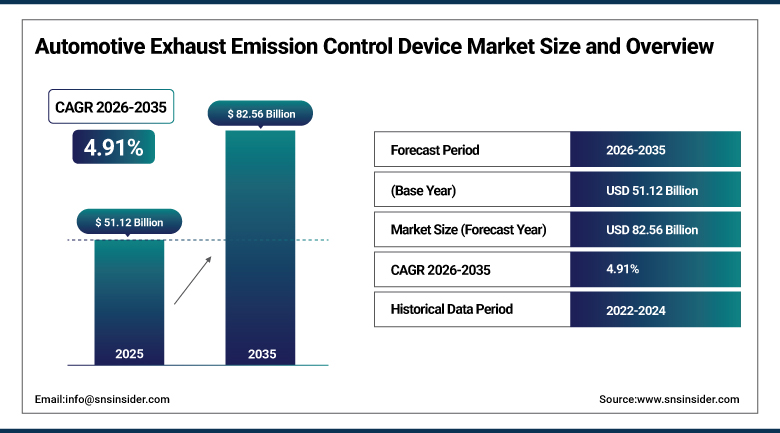
The Automotive Exhaust Emission Control Device Market was valued at USD 51.12 Billion in 2025 and is expected to reach USD 82.56 Billion by 2035, growing at a CAGR of 4.91% from 2026-2035.
The Automotive Exhaust Emission Control Device Market growth is attributed to the increasing number of cars, the need for government control over vehicle emissions, and increasing consciousness regarding the effects of inhaling air pollutants. Without a doubt, the automotive exhaust emission control devices are critical in reducing the negative effects of vehicles on the environment by reducing harmful emissions like nitrogen oxides, carbon monoxide, and hydrocarbons, such as catalytic converters, diesel particulate filters, and exhaust gas recirculation systems, which are all extremely critical in light of the strict governmental regulations aimed at addressing the problem of air pollution and climate change.
In October 2023, Bosal acquired the Clean Air division of Tenneco, which greatly broadened its product range for emission control devices along with manufacturing capabilities of catalytic converters, diesel particulate filters, and exhaust gas recirculation systems used by OEMs and aftermarket customers globally. This deal is just one of many examples of consolidation of this industry that is currently taking place in the market for automotive exhaust emission control devices, where major manufacturers consolidate manufacturing capacities and geographical presence in the face of growing global emission regulations.
To Get more information Automotive Exhaust Emission Control Device Market - Request Free Sample Report
Automotive Exhaust Emission Control Device Market Trends
-
Rising adoption of selective catalytic reduction technology to meet increasingly stringent NOx emission standards.
-
Growing demand for gasoline particulate filters as gasoline direct injection engine adoption continues to expand.
-
Expanding platinum group metal recycling initiatives addressing raw material cost volatility and supply security.
-
Increasing regulatory focus on commercial truck and heavy-duty vehicle after-treatment system compliance.
-
Rising consolidation among emission control suppliers through acquisitions expanding combined product portfolios.
U.S. Automotive Exhaust Emission Control Device Market Outlook
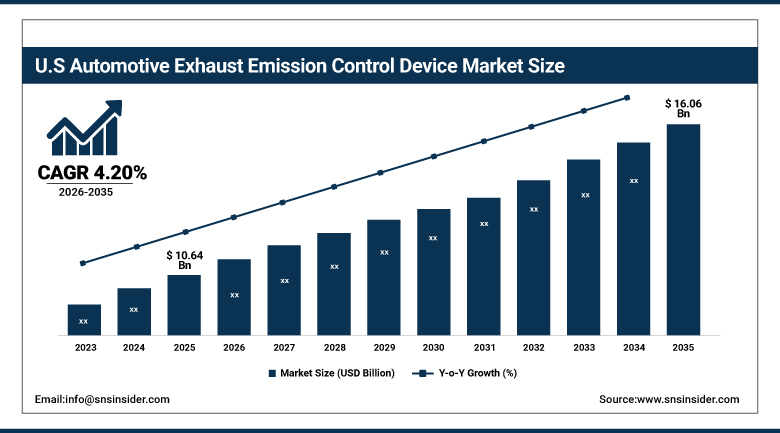
The U.S. Automotive Exhaust Emission Control Device Market was valued at USD 10.64 Billion in 2025 and is expected to reach USD 16.06 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The U.S. Automotive Exhaust Emission Control Device Market growth continues to be reinforced by robust regulatory frameworks governing vehicular emissions, alongside sustained domestic vehicle production and a substantial installed base requiring ongoing aftermarket replacement of catalytic converters, particulate filters, and related after-treatment hardware. Domestic suppliers continue to invest in advanced emission control technology to meet Environmental Protection Agency standards while managing the transition period in which tighter emission rules sustain demand for advanced after-treatment hardware even as battery-electric vehicle growth gradually erodes volumes tied to conventional internal combustion engines. The increasing fleet modernization of commercial trucks, owing to the increasingly strict heavy duty vehicle emissions standards, is continuing to support strong demand for SCR and DPF systems in the local trucking industry.
In March 2023, Tenneco announced the acquisition of Clean Diesel Technologies, Inc., a leading U.S.-based provider of emissions control systems for heavy-duty diesel engines, expanding the company's after-treatment technology portfolio for commercial vehicle and industrial applications. The acquisition illustrates how established domestic emission control suppliers continue to pursue targeted acquisitions to strengthen their heavy-duty diesel after-treatment capability, reflecting the broader industry trend of consolidation among suppliers seeking to expand combined technology portfolios as commercial vehicle emission standards continue to tighten across major domestic and international markets.
Automotive Exhaust Emission Control Device Market Segment Analysis
-
By Device Type, the Three-Way Catalytic Converter segment dominated the Automotive Exhaust Emission Control Device Market with approximately 34.60% share in 2025, while the Selective Catalytic Reduction segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Exhaust Emission Control Device Market with approximately 62.60% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Engine Type, the Gasoline segment dominated the Automotive Exhaust Emission Control Device Market with approximately 54.60% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Material Type, the Platinum segment dominated the Automotive Exhaust Emission Control Device Market with approximately 42.60% share in 2025, while the Palladium segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Sales Channel, the OEM segment dominated the Automotive Exhaust Emission Control Device Market with approximately 68.60% share in 2025, and is also the fastest growing with a CAGR of approximately 5.60%.
By Device Type, Three-Way Catalytic Converter Dominates the Automotive Exhaust Emission Control Device Market and Selective Catalytic Reduction Grows Fastest
Three-way catalytic converters hold a major market share because these devices represent the core emission control technology found in gasoline engines around the world, which reduce carbon monoxide, hydrocarbons, and nitrogen oxides in one piece. The lengthy history, reliability, and mandatory nature of this technology in developed as well as developing nations ensure that these converters maintain their status as the leading device type in terms of revenues, which are forecasted to reach a significant portion of the overall device type market value by the end of the forecast period as more gasoline automobiles are manufactured around the globe.
Selective catalytic reduction is the fastest-growing device type as increasingly stringent NOx emission standards, particularly across heavy-duty diesel and commercial vehicle segments, continue to drive adoption of urea-based after-treatment technology capable of achieving the deep NOx reduction that simpler catalyst designs cannot deliver. This growth is reinforced by tightening regulatory standards including Euro 7 and China VI, which continue to extend selective catalytic reduction requirements into a broader range of diesel vehicle categories previously reliant on simpler oxidation catalyst technology, positioning selective catalytic reduction as the technology of choice for manufacturers seeking to meet the most demanding NOx compliance thresholds across global commercial vehicle markets.
By Vehicle Type, Passenger Vehicles Dominates the Automotive Exhaust Emission Control Device Market and Commercial Vehicles Grows Fastest
Passenger vehicles are the most prevalent type of vehicle due to the huge volume of production of passenger cars worldwide and the almost complete installation of emission control devices in passenger car systems to meet regulation concerning the emissions of carbon monoxide, hydrocarbons, and nitrogen oxides. The increasing disposable incomes in emerging markets fuel the rise in auto ownership, especially in emerging nations with serious problems of pollution-related breathing difficulties. This has helped make passenger cars the biggest vehicle type category as emission control devices are mandated in those markets.
Commercial vehicles represent the fastest-growing vehicle type due to the increasing pressure for fleets to invest in upgrading to meet the new emissions criteria set for heavy duty vehicles, with their demand centering on automotive manufacturing hubs in both India and Mexico where commercial vehicle production has been growing fast. This has been made possible by increased stringent requirements regarding emission regulations in particular to heavy duty trucks and buses, requiring the implementation of complex after-treatment systems comprising diesel particulate filters, selective catalytic reduction and diesel oxidation catalysts.
By Engine Type, Gasoline Dominates the Automotive Exhaust Emission Control Device Market and Hybrid Grows Fastest
Gasoline engines dominate the market because gasoline-powered vehicles continue to represent the majority of global light vehicle production and sales, sustaining substantial demand for three-way catalytic converters and increasingly gasoline particulate filters as gasoline direct injection technology continues to expand across mainstream vehicle platforms. The scale of the global gasoline vehicle fleet, combined with continued new gasoline vehicle production across both developed and emerging markets, continues to sustain gasoline engines' position as the largest engine type category for emission control device suppliers, even as the broader industry gradually transitions toward electrified powertrain alternatives.
Hybrid engines are the fastest-growing engine type as automakers increasingly position hybrid powertrains as a transitional technology bridging conventional internal combustion engines and full battery-electric vehicles, requiring specialized emission control solutions optimized for the unique operating characteristics of hybrid combustion cycles. The expansion will be further facilitated by an increase in sales of hybrid vehicles in major automotive markets, where the after-treatment system that is still required on hybrid platforms must be designed to cater for the constant starting and stopping of engines as well as fluctuating loads associated with the hybrid engine.
By Material Type, Platinum Dominates the Automotive Exhaust Emission Control Device Market and Palladium Grows Fastest
Platinum dominates the market because this platinum group metal continues to offer superior catalytic performance and durability across a broad range of emission control applications, particularly within diesel oxidation catalysts and diesel particulate filters where platinum's oxidation catalytic properties remain difficult to substitute cost-effectively. The metal's established supply chain and extensive qualification history across diesel after-treatment applications continue to sustain platinum's position as the largest material type category, even as suppliers continue to explore material substitution strategies to manage raw material cost volatility across the broader platinum group metal supply chain.
Palladium is the fastest-growing material type as rising gasoline vehicle production and increasing gasoline particulate filter adoption continue to favor palladium's superior performance characteristics within gasoline-specific catalytic converter applications relative to platinum. This growth is reinforced by continued gasoline direct injection engine adoption, which increasingly requires palladium-based catalytic formulations optimized for gasoline combustion chemistry, positioning palladium demand growth ahead of the broader material type category as gasoline vehicle production continues to expand across both developed and emerging automotive markets.
By Sales Channel, OEM Dominates the Automotive Exhaust Emission Control Device Market and Also Grows Fastest
The OEM channel dominates the market because emission control devices are integrated during original vehicle assembly under long-term supply agreements between automakers and established tier-one after-treatment suppliers, requiring precise calibration with vehicle-specific engine management and exhaust system architecture. This integration complexity, combined with the safety-critical and regulatory-mandated nature of emission control device installation, continues to favor established OEM supplier relationships with extensive vehicle-specific validation and certification testing across global regulatory jurisdictions.
The OEM channel is also the fastest-growing sales channel as rising global vehicle production continues to outpace aftermarket replacement demand growth, with original equipment manufacturer partnerships increasingly tilting toward integrated exhaust system supply arrangements that bundle emission control devices with broader exhaust system components. This growth is reinforced by tightening emission regulations requiring increasingly sophisticated, factory-calibrated after-treatment systems that are more difficult to replicate through generic aftermarket replacement parts, reinforcing OEM channel growth relative to traditional aftermarket replacement demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
44.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Automotive Exhaust Emission Control Device Market Insights
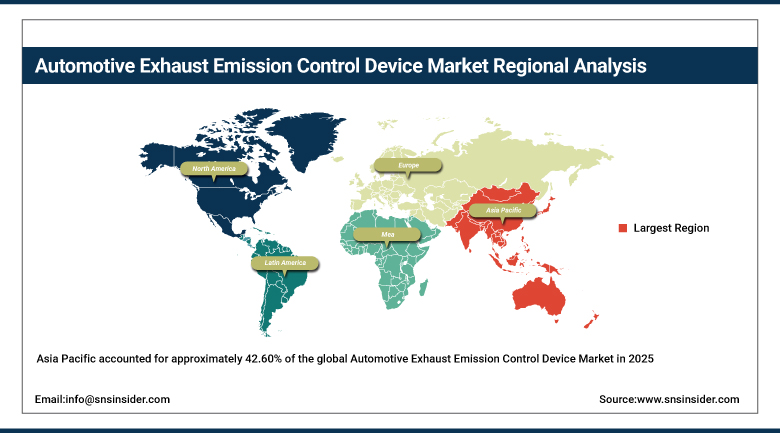
Asia Pacific accounted for approximately 42.60% of the global Automotive Exhaust Emission Control Device Market in 2025, making it both the largest and fastest-growing regional market, expanding at a CAGR of approximately 5.80% from 2026 to 2035. The major automobile manufacturers have used the region to manufacture cars in large numbers, and there has been an increase in the number of automobiles in the region owing to the rise in disposable income, hence the need for emission control systems on a very large number of automobiles. In addition, the nations within the region are the most polluted nations, with very high levels of respiratory illnesses caused by pollution.
China's large domestic vehicle production base continues to anchor regional demand, supported by China VI emission standards that continue to extend regulatory stringency across both passenger and commercial vehicle segments. India is contributing significant incremental growth as its automotive manufacturing sector continues to expand rapidly, with demand for emission control hardware concentrating in manufacturing clusters as fleet operators upgrade to comply with new regulations. Japan and South Korea contribute additional scale through established automotive component manufacturing sectors, reinforcing Asia Pacific's position as the largest and fastest-growing market through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Exhaust Emission Control Device Market Insights
North America represents a significant share of the global Automotive Exhaust Emission Control Device Market, anchored by the United States' robust regulatory frameworks governing vehicular emissions and sustained domestic vehicle production requiring comprehensive emission control device installation. The region's substantial installed vehicle base continues to sustain steady aftermarket replacement demand, as catalytic converters and particulate filters require periodic replacement throughout each vehicle's extended service life amid stringent Environmental Protection Agency compliance standards.
Canada and Mexico are contributing incremental demand as regional automotive manufacturing supply chains continue to integrate emission control device production capacity, with Mexico increasingly serving as a manufacturing cluster for commercial vehicle after-treatment systems. Continued domestic investment in platinum group metal recycling capability, combined with rising commercial truck fleet modernization driven by stricter heavy-duty vehicle emission standards, is expected to sustain steady regional growth through the forecast period even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Europe Automotive Exhaust Emission Control Device Market Insights
Europe represents a significant share of the global Automotive Exhaust Emission Control Device Market, anchored by Germany's large automotive manufacturing base and the region's stringent regulatory framework, including the implementation of Euro 7 emission standards that continue to raise compliance requirements across both passenger and commercial vehicle segments. European suppliers continue to lead in developing advanced after-treatment technology, including selective catalytic reduction and gasoline particulate filter systems, supported by the region's concentration of established emission control technology suppliers and automotive engineering expertise.
France, the United Kingdom, and Italy are contributing steady demand growth as regional automakers extend advanced emission control technology from premium vehicle segments into broader mass-market platforms to meet evolving Euro 7 compliance requirements. Regional suppliers continue to invest in platinum group metal recycling and material substitution strategies to manage raw material cost volatility while maintaining compliance with the region's stringent environmental regulatory framework, supporting continued steady regional demand through the forecast period.
MEA & Latin America Automotive Exhaust Emission Control Device Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing vehicle ownership across the United Arab Emirates and Saudi Arabia sustains demand for emission control hardware suited to regional regulatory requirements. Regional vehicle assembly remains limited, with much of the region's emission control device supply continuing to be imported from Asian, European, and North American manufacturers as governments increasingly align domestic emission standards with international regulatory frameworks.
The market for Latin America is dominated by Brazil, which benefits from a large manufacturing base for vehicles that ensures steady demand for emissions control products through both OEM and after-market applications. Mexico, on the other hand, is becoming a major source of growth due to increased investment into the automotive components manufacturing industry in the region, with the demand for emission control products coming from its commercial vehicles manufacturing industry.
Market Dynamics
Growth Drivers: Stringent Emission Regulations and Rising Vehicle Production
Government mandates to control vehicular emissions represent the primary driver of Automotive Exhaust Emission Control Device Market growth, as regulatory bodies across major automotive markets continue to implement and tighten emission standards including Euro 7, China VI, and evolving Environmental Protection Agency requirements. Rising levels of air pollution and surging awareness of the health effects of breathing polluted air continue to reinforce sustained government and consumer pressure for comprehensive emission control device adoption, sustaining demand for advanced after-treatment hardware even during the ongoing transition toward electrified vehicle powertrains.
The increasing number of vehicles worldwide represents a second major growth driver, as rising disposable income in developing economies including China, Japan, Germany, and India continues to expand vehicle production and ownership, directly translating into proportionally higher demand for compliant emission control hardware across both original equipment and aftermarket channels. Growing concern over environmental safety from both public and private sectors continues to reinforce this trend, extending emission control device adoption into a broadening range of vehicle segments and geographic markets previously reliant on less stringent emission control technology.
Restraints: Platinum Group Metal Cost Volatility and Electric Vehicle Transition
The fluctuation in the prices of the metals used in the fabrication of emission control devices such as platinum, palladium, and rhodium is another notable challenge facing the development of the market. This arises from the fact that suppliers face difficulties dealing with fluctuating raw material prices owing to the global commodity market while at the same time trying to deal with customers whose price demands can be very competitive.
The trend toward battery-electric cars, in addition to that, is another restriction, since growing popularity of electric vehicles will slowly decrease the market size for internal combustion engine exhaust emission management products in the long run. This trend implies a challenge for the existing players to move through a transition period, where tougher emission standards around the globe will still drive the demand in the short run despite the growing difficulties in the long run.
Opportunities: Platinum Group Metal Recycling and Heavy-Duty Vehicle Standards Expansion
Expanding platinum group metal recycling initiatives represent a substantial opportunity, as suppliers increasingly develop closed-loop recycling capability to address raw material cost volatility and supply security concerns tied to global platinum group metal markets. Suppliers that can establish reliable, cost-competitive recycling infrastructure are positioned to reduce raw material cost exposure while strengthening supply chain resilience relative to competitors reliant solely on primary platinum group metal mining and refining sources.
The continued expansion of heavy-duty vehicle emission standards offers a further avenue for growth, as increasing regulatory focus on commercial truck and heavy-duty vehicle after-treatment system compliance continues to extend demand for selective catalytic reduction and diesel particulate filter technology into previously underserved commercial vehicle segments and geographic markets. Suppliers that can develop cost-competitive, compliant after-treatment systems suited to heavy-duty commercial vehicle applications are well positioned to capture demand as regulatory stringency continues to expand across global commercial vehicle markets.
Recent Developments:
-
2023: Johnson Matthey partnered with FAW Group to develop and supply emission control catalysts for heavy-duty trucks, supporting stricter emissions standards and cleaner commercial transportation in China.
-
2023: CDTi announced a partnership with a major trucking company to pilot its emissions reduction technology, evaluating its effectiveness in improving heavy-duty vehicle emissions performance.
-
2023: Eberspächer launched a new exhaust gas recirculation system for gasoline engines, designed to reduce CO₂ emissions while supporting improved engine efficiency and compliance with emissions regulations.
-
2023: Johnson Matthey partnered with Umicore to develop and commercialize new catalytic converter technologies, supporting evolving vehicle emission-control requirements and technological advancements in automotive catalyst applications.
Automotive Exhaust Emission Control Device Market Key Players are:
-
BorgWarner Inc.
-
Faurecia SE (Forvia)
-
Tenneco Inc.
-
Eberspächer Gruppe GmbH & Co. KG
-
Continental AG
-
Magna International Inc.
-
DENSO Corporation
-
Johnson Matthey Plc
-
Bosal International N.V.
-
CDTi Advanced Materials, Inc.
-
Robert Bosch GmbH
-
Albonair GmbH
-
Umicore N.V.
-
Cummins Inc.
-
Katcon Global
-
Yutaka Giken Co., Ltd.
-
Sango Co., Ltd.
-
Jetex Exhaust Ltd.
-
Friedrich Boysen GmbH & Co. KG
-
BASF SE
Automotive Exhaust Emission Control Device Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 51.12 Billion |
| Market Size by 2035 | USD 82.56 Billion |
| CAGR | CAGR of 4.91% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Three-Way Catalytic Converter, Diesel Particulate Filter, Selective Catalytic Reduction, Diesel Oxidation Catalyst, Gasoline Particulate Filter, Lean NOx Trap) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles) • By Engine Type (Gasoline, Diesel, Hybrid, Natural Gas/Alternative Fuels) • By Material Type (Platinum, Palladium, Rhodium) • By Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BorgWarner Inc., Faurecia SE (Forvia), Tenneco Inc., Eberspächer Gruppe GmbH & Co. KG, Continental AG, Magna International Inc., DENSO Corporation, Johnson Matthey Plc, Bosal International N.V., CDTi Advanced Materials, Inc., Robert Bosch GmbH, Albonair GmbH, Umicore N.V., Cummins Inc., Katcon Global, Yutaka Giken Co., Ltd., Sango Co., Ltd., Jetex Exhaust Ltd., Friedrich Boysen GmbH & Co. KG, BASF SE |
Frequently Asked Questions
Key players include BorgWarner Inc., Faurecia SE (Forvia), Tenneco Inc., Eberspächer Gruppe GmbH & Co. KG, Continental AG, Johnson Matthey Plc, and Umicore N.V., among other global after-treatment technology suppliers.
