
Automotive Aftermarket Industry Report Scope & Overview:
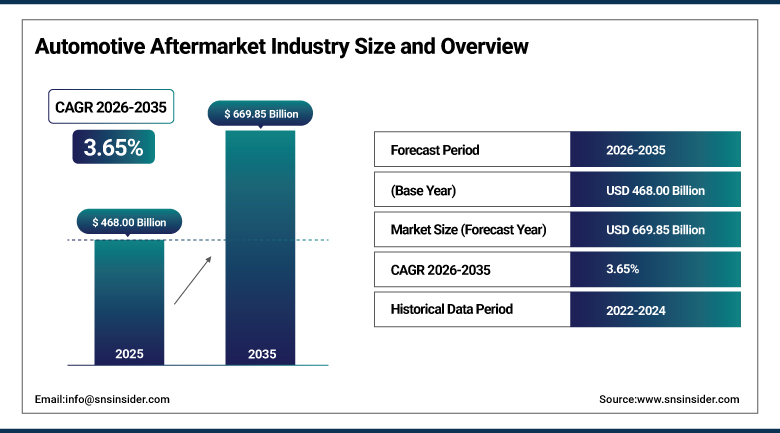
The Automotive Aftermarket Industry was valued at USD 468.00 Billion in 2025 and is expected to reach USD 669.85 Billion by 2035, growing at a CAGR of 3.65% from 2026-2035.
The Automotive Aftermarket Industry is experiencing growth mainly due to aging of the global vehicle parc, currently over 1.5 billion vehicles, which is creating a persistent demand for replacement parts, maintenance, and repairs well after the original OEM warranty period expires. Both consumers and fleet operators are retaining their vehicles for longer due to higher new-vehicle prices, creating maintenance demands which support aftermarket parts and services on a regular basis. The demand is also driven by the digitalization of parts sourcing and adoption of connected car telematics and diagnostics that allow for more accurate prediction of maintenance needs. Higher levels of electric vehicle penetration will also start transforming the product mix of the industry by adding aftermarket services and parts for EV batteries, charging stations, and software updates to the existing portfolio of mostly mechanical parts.
In March 2024, Auto1 Group SE enhanced its cross-border digital wholesale marketplace infrastructure across European markets to optimize dealer-to-dealer inventory redistribution and balance regional supply imbalances. The initiative illustrates how leading automotive marketplace operators are investing in digital infrastructure to accelerate vehicle and parts turnover cycles across an increasingly interconnected European aftermarket ecosystem.
To Get more information Automotive Aftermarket Industry - Request Free Sample Report
Automotive Aftermarket Industry Trends
-
Continued digital transformation of parts procurement through online marketplaces and e-commerce platforms.
-
Growing adoption of connected-vehicle telematics enabling predictive maintenance and diagnostics.
-
Rising demand for electronics and ADAS sensor replacement as vehicle technology content increases.
-
Expanding electric vehicle aftermarket ecosystem covering battery service, charging, and software updates.
-
Continued industry consolidation as national parts retailers acquire independent operators and buying groups.
U.S. Automotive Aftermarket Industry Outlook
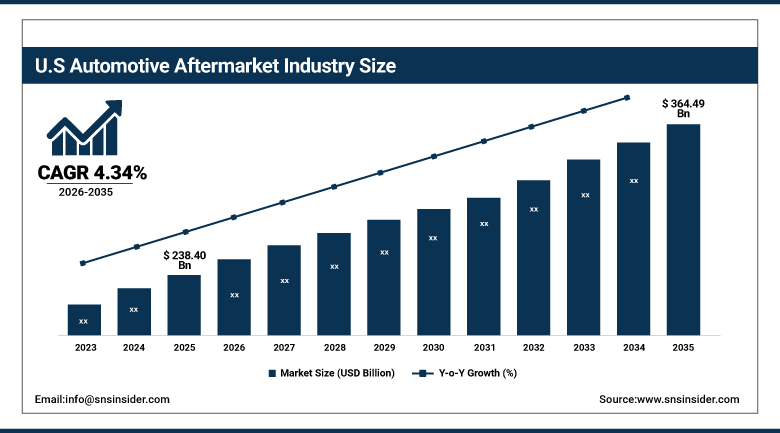
The U.S. Automotive Aftermarket Industry was valued at USD 238.40 Billion in 2025 and is expected to reach USD 364.49 Billion by 2035, growing at a CAGR of 4.34% from 2026-2035.
The development of the U.S. Automotive Aftermarket Industry is further fueled by the longer average vehicle holding period, the presence of a healthy demand for parts and services thanks to light trucks and SUVs, and the ongoing favorability of professional Do-It-For-Me services over Do-It-Yourself repairs by consumers. Domestic demand is further supported by efficient e-commerce infrastructure which is used by online parts stores, as well as by a large amount of national and independent repair shops. The increase of electric vehicles in the United States starts to demand dedicated aftermarket products and services.
In January 2025, Cars.com Inc., a U.S.-based automotive technology company, acquired DealerClub, a digital wholesale auction platform, for USD 25 million. The acquisition enables Cars.com to expand into the wholesale used-parts and vehicle market and enhance its platform with dealer-to-dealer digital auction capabilities, reflecting continued domestic consolidation of digital marketplace infrastructure serving the broader automotive aftermarket ecosystem.
Automotive Aftermarket Industry Segment Analysis
-
By Replacement Part, the Tire segment dominated the Automotive Aftermarket Industry with approximately 23.20% share in 2025, while the Electronics segment is the fastest growing with a CAGR of approximately 4.05%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Aftermarket Industry with approximately 63.76% share in 2025, while the Light Commercial Vehicles segment is the fastest growing with a CAGR of approximately 4.60%.
-
By Distribution Channel, the Retailers segment dominated the Automotive Aftermarket Industry with approximately 48.50% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Service Channel, the DIFM segment dominated the Automotive Aftermarket Industry with approximately 54.50% share in 2025, while the DIY segment is the fastest growing with a CAGR of approximately 4.80%.
-
By Certification, the Genuine segment dominated the Automotive Aftermarket Industry with approximately 51.00% share in 2025, while the Non-Genuine segment is the fastest growing with a CAGR of approximately 4.90%.
-
By Propulsion Type, the ICE segment dominated the Automotive Aftermarket Industry with approximately 85.50% share in 2025, while the Electric Vehicle segment is the fastest growing with a CAGR of approximately 7.20%.
By Replacement Part, Tire dominates and Electronics grows fastest
Tires continue to account for the largest replacement part category in the Automotive Aftermarket Industry due to the frequent wear and tear associated with tires irrespective of the type of vehicles, whether new, old, brand-specific or otherwise. The replacement category enjoys the advantage of being a highly recurrent process, which is determined by the number of miles traveled by the vehicle, and the wear out of the tire treads, thus offering consistent demand independent of the economic cycles governing vehicle expenditures.
The electronics components category is the fastest growing replacement part category, due to the high-tech nature of the automobiles being produced today with many parts, such as the ADAS sensors, infotainment and other connectivity technologies. Thus, the replacement and recalibration of electronic components in these cars is becoming increasingly complex, as the vehicle technology usage increases in the global vehicle parc.
By Vehicle Type, Passenger Cars dominates and Light Commercial Vehicles grows fastest
Passenger Cars remain the dominant vehicle type segment within the Automotive Aftermarket Industry, reflecting the sheer scale of the global passenger vehicle parc relative to commercial vehicle segments. This segment benefits from consistent, high-volume replacement part and service demand across a vast installed base of aging passenger vehicles spanning multiple ownership cycles.
Light Commercial Vehicles are emerging as the fastest-growing vehicle type segment, driven by rapid growth in e-commerce-driven last-mile delivery fleets that accumulate higher mileage and require more frequent maintenance than typical passenger vehicles. This segment focuses on durable, higher-capacity replacement parts suited to the demanding duty cycles of delivery and light commercial applications, positioning light commercial vehicles to capture disproportionate aftermarket revenue growth relative to their smaller share of the overall vehicle parc.
By Distribution Channel, Retailers dominates and Online grows fastest
Retail remains the prevailing channel of distribution in the Automotive Aftermarket Industry due to the persistence of physical parts store outlets that cater to professional installers and Do-it-yourself consumers who need parts right away. The segment leverages the extensive network of retail establishments across the country maintained by major parts chain companies with large assortments of products and same-day or on-site pick up facilities.
The Online distribution channel is fast becoming the fastest-growing segment owing to increased comfort of consumers and professional installers with e-commerce websites that offer wider selection of parts, competitive prices, and home delivery facilities. The segment emphasizes developing extensive digital catalogs, fitment verification tools, and efficient logistics for swift delivery.
By Service Channel, DIFM dominates and DIY grows fastest
Do-It-For-Me service service channel continues to be the largest service channel in the Automotive Aftermarket Industry owing to growing technical complexity in vehicles that need special diagnostic tools and skills which are not available to most of the vehicle owners. This service channel is gaining benefit from the increasing tendency of customers towards professional services in the context of both independent repair shops and franchised dealerships.
DIY service channel is gaining rapid momentum in selected markets because of the increased availability of tutorials, easy packaging of parts, and the presence of online retailers who sell DIY kits. This service channel concentrates on low-budget vehicle owners carrying out routine maintenance activities including fluids changes, filters replacements, and simple component replacement. DIY is thus a robust channel especially during hard times economically speaking.
By Certification, Genuine dominates and Non-Genuine grows fastest
Original Genuine remains the largest certification category in the Automotive Aftermarket Industry owing to the preference of consumers and fleets for OEM-certified parts, which ensure continued vehicle warranty coverage while providing a consistent fit and performance. This certification category is well established due to the high level of brand credibility and quality assurance that OEM parts provide especially for safety-critical components like brakes and steering mechanisms.
The Non-Genuine category is shaping up to be the fastest-growing certification category based on consumers looking for value-for-money parts in order to repair aged-out-of-warranty vehicles as well as shops that have to work with budget constraints when repairing older cars. This certification category aims to widen the scope of quality-certified aftermarket parts, whose performance is close to genuine parts but at a significantly lower price point.
By Propulsion Type, ICE dominates and Electric Vehicle grows fastest
IC vehicles continue to account for the vast majority of propulsion segments within the Automotive Aftermarket Industry as they continue to have the largest share of ICEs in the current global vehicle parc despite a fast-rising number of electric vehicles sold. The development of the aftermarket services in this segment is supported by a large number of years of experience and infrastructure that has been specifically created for ICE repair.
The Electric Vehicle segment emerges as the fastest-growing propulsion segment. It is caused by the first generation of electric vehicles entering their first cycle of service of various parts such as tires, brakes, and batteries. Special attention needs to be paid to the creation of training programs for technicians and diagnostic equipment designed for high voltage electric vehicles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
India |
55.60% |
|
North America |
United States |
82.50% |
|
Europe |
Germany |
37.56% |
|
Latin America |
Brazil |
48.60% |
|
Middle East & Africa |
United Arab Emirates |
27.80% |
Asia Pacific Automotive Aftermarket Industry Insights
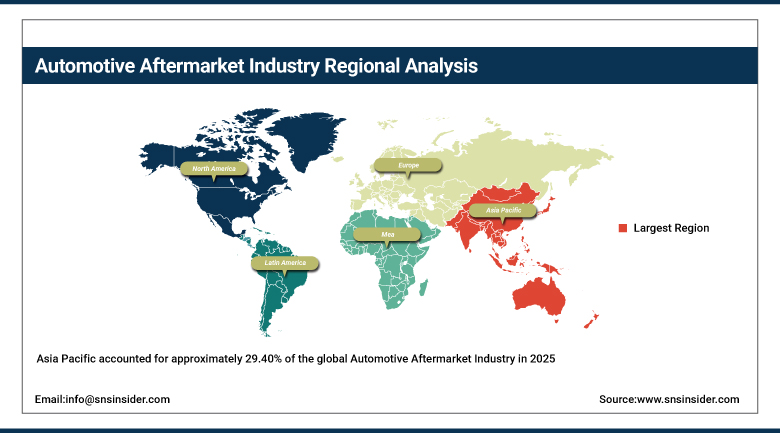
Asia Pacific accounted for approximately 29.40% of the global Automotive Aftermarket Industry in 2025 and is also projected to expand at the fastest pace during the 2026-2035 forecast period, driven by rapid growth in vehicles aging out of warranty coverage and expanding internet penetration supporting digital aftermarket platforms. India represents a particularly significant contributor within the region, holding the largest country-level market share globally according to recent industry analysis, supported by its large and rapidly aging domestic vehicle fleet.
China's aftermarket is transforming rapidly, with tens of millions of vehicles expected to move out of warranty coverage in the near term, creating substantial demand for parts and repair services. Growing internet penetration continues to support digital aftermarket platforms such as Tuhu.cn in China and GoMechanic in India, making parts and services increasingly accessible and further reinforcing Asia Pacific's position as both the largest and fastest-growing global aftermarket region.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Aftermarket Industry Insights
The North American region offers a large regional market potential for the automotive aftermarket due to the size of the vehicle fleet in the United States and its well-developed network of national distributors of automobile spare parts and independent repair shops.
The United States makes up the bulk of the regional demand due to its large vehicle parc as well as being home to major aftermarket distributors of spare parts. The volume of demand from Canada and Mexico is added by the integration of the automotive supply chain of North America and an increase in the number of vehicles in these two countries.
Europe Automotive Aftermarket Industry Insights
Europe represents a significant regional market for the automotive aftermarket, anchored by Germany's sizable and aging vehicle base and its concentration of premium automakers whose vehicles typically require specialized, higher-value replacement parts. Germany's share within the European market reflects both its large domestic vehicle fleet and its home-market presence of major automotive parts manufacturers and distributors.
The United Kingdom and France contribute additional regional demand, supported by established vehicle fleets and mature aftermarket service networks. Continued European Union regulatory focus on vehicle emissions and right-to-repair legislation supports steady regional demand for both genuine and independent aftermarket parts and service providers.
MEA & Latin America Automotive Aftermarket Industry Insights
Latin American Automotive Aftermarket is dominated by Brazil, which represents the largest share of demand in the region due to its large number of domestic automobiles and serves as an automotive manufacturing and distribution center for the region. Slow economic growth along with vehicle growth in Brazil and Mexico continues to drive gradual demand growth in the region for replacement parts and repair services.
In the Middle East & Africa region, the contribution to global demand has been lower, with demand growth occurring mainly in GCC countries like the UAE, where the import of vehicles and increased infrastructure for the automotive services industry continue to boost aftermarket demand. The demand for the aftermarket is anchored by South Africa in the African region owing to its better infrastructure.
Market Dynamics
Growth Drivers: Aging Vehicle Parc and Digital Transformation
The aging global parc of vehicles, already numbering over 1.5 billion active vehicles in circulation, stands out as the key driver behind the growth of the Automotive Aftermarket Industry, as the increasing number of vehicles operating past their initial warranties creates a continuous demand for automotive parts and repair. The trend is accentuated by the ever-higher prices of new vehicles that have encouraged buyers to retain their old vehicles for a long time and refrain from purchasing a new one.
The rapid digitization of the process of purchasing parts and the increased use of connected-car telematics serve as another considerable factor for demand, as these innovations allow for predictive maintenance and scheduling, helping predict the need for replacement parts prior to any breakdown. The consolidation of the industry, particularly that of national parts distributors and buying organizations, also contributes to the growth of the industry.
Restraints: Vehicle Electrification and Right-to-Repair Complexity
The aging global parc of vehicles, already numbering over 1.5 billion active vehicles in circulation, stands out as the key driver behind the growth of the Automotive Aftermarket Industry, as the increasing number of vehicles operating past their initial warranties creates a continuous demand for automotive parts and repair. The trend is accentuated by the ever-higher prices of new vehicles that have encouraged buyers to retain their old vehicles for a long time and refrain from purchasing a new one.
The rapid digitization of the process of purchasing parts and the increased use of connected-car telematics serve as another considerable factor for demand, as these innovations allow for predictive maintenance and scheduling, helping predict the need for replacement parts prior to any breakdown. The consolidation of the industry, particularly that of national parts distributors and buying organizations, also contributes to the growth of the industry.
Opportunities: Electric Vehicle Aftermarket Expansion and Digital Platform Growth
As the electric vehicle aftermarket matures further, it represents a significant growth opportunity for the Automotive Aftermarket Industry, as the first generation of electric vehicles enter the first period of maintenance and replacement of tires, brakes, and the unique electric vehicle batteries and charging systems. Suppliers and service providers who have developed the ability to offer competitive electric vehicle aftermarket solutions will be well placed to take advantage of the opportunity as the worldwide electric vehicle parc matures.
Increased adoption of online marketplace and telematics platforms represents a longer-term opportunity for suppliers to expand their offerings into predictive maintenance and schedule-based service. As telematics solutions and diagnostic solutions evolve, suppliers and service providers who are established players in online markets will take a disproportionately large slice of this market.
Recent Developments:
-
In January 2024, CarMax Inc. expanded its artificial intelligence-based vehicle appraisal platform across its nationwide operations to improve pricing accuracy and inventory acquisition efficiency, integrating predictive valuation analytics and automated inspection data processing capabilities.
-
In April 2024, Genuine Parts Company disclosed the acquisition of Motor Parts & Equipment Corporation (MPEC), the largest NAPA independent store operator in the United States, continuing the company's strategy of owning more stores directly in priority markets.
-
In May 2024, LKQ Corporation announced plans to sell its Elit Polska unit, based in Poland, to Sweden's MEKO as part of a broader strategy to optimize its business portfolio and concentrate on core activities.
-
In November 2024, Advance Auto Parts completed the sale of its Worldpac Inc. business for USD 1.5 billion, following a definitive purchase agreement entered in August 2024, as part of a broader strategic and operational restructuring plan.
Automotive Aftermarket Industry Key Players
-
AutoZone, Inc.
-
O'Reilly Automotive, Inc.
-
Advance Auto Parts, Inc.
-
Genuine Parts Company (NAPA)
-
LKQ Corporation
-
Robert Bosch GmbH
-
Denso Corporation
-
Continental AG
-
ZF Friedrichshafen AG
-
Aisin Corporation
-
BorgWarner Inc.
-
Tenneco Inc.
-
Valeo S.A.
-
MAHLE GmbH
-
Hyundai Mobis Co., Ltd.
-
Magna International Inc.
-
Dorman Products, Inc.
-
Standard Motor Products, Inc.
-
Bridgestone Corporation
-
Michelin Group
Automotive Aftermarket Industry Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 468.00 Billion |
| Market Size by 2035 | USD 669.85 Billion |
| CAGR | CAGR of 3.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Replacement Part (Tire, Battery, Brake Parts, Filters, Body Parts, Wheels, Lighting Components, Electronics, and Others) • by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Heavy Commercial Vehicles) • by Distribution Channel (Retailers, OEM, and Online) • by Service Channel (DIFM and DIY) • by Certification (Genuine and Non-Genuine) • by Propulsion Type (ICE and Electric Vehicle) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AutoZone, Inc., O'Reilly Automotive, Inc., Advance Auto Parts, Inc., Genuine Parts Company (NAPA), LKQ Corporation, Robert Bosch GmbH, Denso Corporation, Continental AG, ZF Friedrichshafen AG, Aisin Corporation, BorgWarner Inc., Tenneco Inc., Valeo S.A., MAHLE GmbH, Hyundai Mobis Co., Ltd., Magna International Inc., Dorman Products, Inc., Standard Motor Products, Inc., Bridgestone Corporation, Michelin Group |
Frequently Asked Questions
Leading companies in the Automotive Aftermarket Industry include AutoZone, O'Reilly Automotive, Advance Auto Parts, Genuine Parts Company, and LKQ Corporation, among others.
Key opportunities include continued maturation of the electric vehicle aftermarket as first-generation EV fleets age into their initial replacement cycles, and growing adoption of digital marketplace and connected-vehicle diagnostic platforms.
An aging global vehicle parc exceeding 1.5 billion units, combined with elevated new-vehicle prices encouraging extended ownership of existing vehicles, is the major factor driving market growth.
The Tire segment dominated the Automotive Aftermarket Industry with approximately 23.20% share in 2025.
Asia Pacific dominated the Automotive Aftermarket Industry in 2025 with approximately 29.40% share, driven by rapid vehicle aging and expanding digital aftermarket platform adoption, led by India.
