
Automotive Gear Shift System Market Report Scope & Overview:
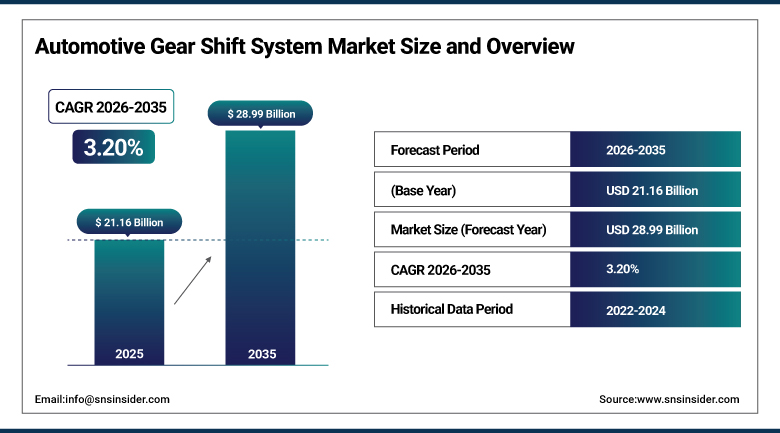
The Automotive Gear Shift System Market was valued at USD 21.16 Billion in 2025 and is expected to reach USD 28.99 Billion by 2035, growing at a CAGR of 3.20% from 2026-2035.
The Automotive Gear Shift System market growth is mainly due to the fact that the automotive industry is steadily shifting towards electronic control of the transmission system due to increasing CO2 regulations in terms of emissions and introduction of electric powertrain that requires precision of the software-controlled gear shift. While manual gear shift systems are still holding their market shares because of their relatively cheaper prices compared to other alternatives in developing countries and some commercial vehicles, automatic and dual clutch types are gaining popularity amongst urban dwellers who find themselves in stop-and-go traffic environment. Increasing demand for comfortable driving is supported by decreasing learning time required for the drivers of automated manual transmissions.
Steady reduction of stick-shifts in North America and Europe, and increasing use of the shift-by-wire technology in hybrid and electric vehicles will secure market growth for decades to come.
In August 2025, Dura Automotive Systems acquired Kongsberg Automotive's gear-actuation business, expanding its portfolio of electronic shifter solutions and strengthening its aftermarket capabilities.
To Get more information Automotive Gear Shift System Market - Request Free Sample Report
Automotive Gear Shift System Market Trends
- Continued industry shift toward electronically controlled shift-by-wire architectures replacing mechanical linkages.
- Growing adoption of dual-clutch transmission systems combining fuel efficiency with sporty acceleration characteristics.
- Rising supplier consolidation as companies combine electronic shift-by-wire competencies through acquisition.
- Increasing integration of predictive gear control technologies and adaptive shift algorithms.
- Continued gradual phase-out of manual transmission models across North American and European markets.
U.S. Automotive Gear Shift System Market Outlook
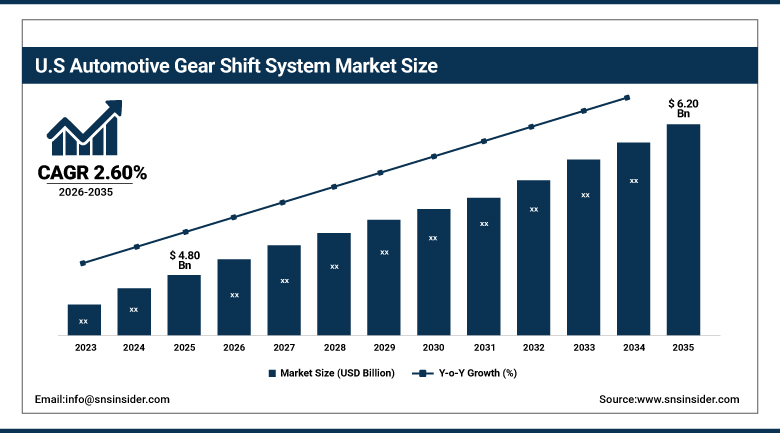
The U.S. Automotive Gear Shift System Market was valued at USD 4.80 Billion in 2025 and is expected to reach USD 6.20 Billion by 2035, growing at a CAGR of 2.60% from 2026-2035.
U.S. Automotive Gear Shift System Market growth is being further propelled by the movement towards electric and self-driving cars in the local automotive industry, with the need for OEMs to introduce electronic and hybrid shift systems for the sake of safety, comfort, and improved performance. The local market also receives additional advantages due to the location of large automotive producers and Tier 1 suppliers capable of producing shift-by-wire solutions. This helps the region to establish itself as a technological leader when it comes to automotive components of this type. Local government support for electric vehicles along with consumers' desire to have modern interior design results in the increased usage of shift-by-wire solutions.
In October 2024, BorgWarner announced expanded shift-by-wire manufacturing capacity across its North American facilities to serve growing customer demand. The expansion reflects continued domestic investment in electronic shift technology production capacity as automakers accelerate adoption of shift-by-wire systems across new vehicle platforms.
Automotive Gear Shift System Market Segment Analysis
- By Transmission Type, the Manual segment dominated the Automotive Gear Shift System Market with approximately 41.27% share in 2025, while the Dual-Clutch segment is the fastest growing with a CAGR of approximately 5.39%.
- By Technology, the Mechanical segment dominated the Automotive Gear Shift System Market with approximately 42.00% share in 2025, while the Electronic/Shift-By-Wire segment is the fastest growing with a CAGR of approximately 8.60%.
- By Vehicle Type, the Passenger Cars segment dominated the Automotive Gear Shift System Market with approximately 68.00% share in 2025, while the Light Commercial Vehicles segment is the fastest growing with a CAGR of approximately 4.80%.
- By Sales Channel, the OEM segment dominated the Automotive Gear Shift System Market with approximately 78.50% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 4.60%.
By Transmission Type, Manual dominates and Dual-Clutch grows fastest
The manual transmission gear shift assemblies are the key players in the segment of transmission type in the Automotive Gear Shift System market. This is due to the price factor that continues to make cost-conscious buyers in the developing world stick to low-cost drivetrain designs. Dual-clutch transmission system is expected to become the fastest-growing transmission type segment due to its ability to combine fuel efficiency with sporty acceleration, thus meeting emission regulations and branding needs.
Dual-clutch transmission system relies heavily on clutch-to-clutch transition improvement that takes place under joint efforts of OEMs and software developers. This system is positioned as the one to satisfy increasing needs of city buyers in stop-and-go traffic and needs of automakers to differentiate themselves through performance.
By Technology, Mechanical dominates and Electronic/Shift-By-Wire grows fastest
Mechanical linkage systems remain the dominant technology segment within the Automotive Gear Shift System Market, reflecting their established reliability, low manufacturing cost, and continued specification across manual and conventional automatic transmission platforms worldwide. This segment benefits from decades of proven mechanical engineering refinement, supporting continued use across cost-sensitive vehicle segments and markets where electronic shift technology adoption remains limited.
Electronic and shift-by-wire technology is emerging as the fastest-growing technology segment, driven by automakers' accelerating transition toward software-controllable shift architectures that eliminate mechanical linkages between the gear selector and transmission. This segment focuses on integration with autonomous driving algorithms, haptic feedback systems, and compact cabin design, positioning shift-by-wire technology to capture a rapidly growing share of overall gear shift system demand as electrification and vehicle digitization continue to advance.
By Vehicle Type, Passenger Cars dominates and Light Commercial Vehicles grows fastest
Passenger Cars is the leading vehicle type segment in the Automotive Gear Shift System Market due to the high level of production of passenger vehicles worldwide in comparison with other commercial vehicle segments. The segment is supported by consistent content of gear shift systems in all sedans, SUVs, and crossover vehicles, while the increasing number of shift-by-wire systems increases the value of gear shift components.
Light Commercial Vehicles represent the fastest-growing vehicle type segment because of the fast growth of delivery fleets for e-commerce companies that need automated and semi-automated transmission systems, since they help reduce driver training time. The segment includes robust and highly cyclical gear shift systems which are suitable for commercial deliveries. Light Commercial Vehicles will be able to gain disproportional growth in the future due to updating of vehicle transmission technologies.
By Sales Channel, OEM dominates and Aftermarket grows fastest
OEM sales remain the dominant channel within the Automotive Gear Shift System Market, reflecting the direct integration of gear shift systems into new-vehicle transmission assemblies during original manufacturing. This segment benefits from long-term supply agreements between component manufacturers and automakers, sustaining stable, high-volume demand tied directly to global vehicle production levels.
The Aftermarket segment is emerging as the fastest-growing sales channel, driven by rising demand for gear shift component replacement as the global vehicle fleet ages and by growing popularity of retrofit electronic shift solutions among consumers seeking to modernize older vehicle interiors. This segment focuses on expanding distribution networks and product availability for both mechanical and electronic gear shift replacement components, supporting steady growth as vehicle service life continues to extend.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
48.60% |
|
North America |
United States |
82.50% |
|
Europe |
Germany |
31.60% |
|
Latin America |
Brazil |
44.20% |
|
Middle East & Africa |
United Arab Emirates |
27.90% |
Asia Pacific Automotive Gear Shift System Market Insights
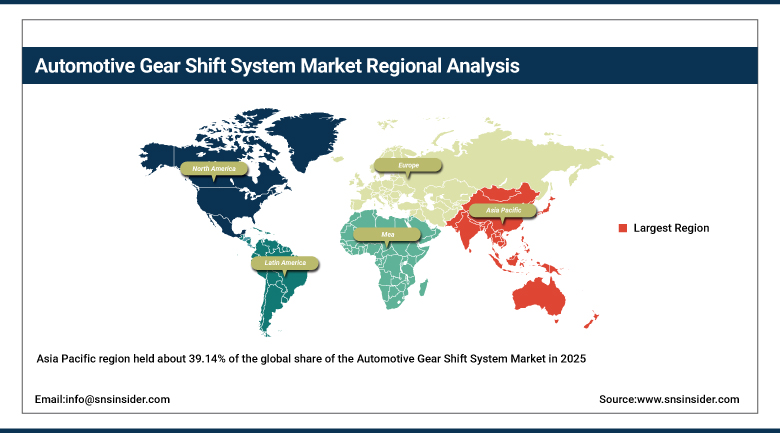
The Asia Pacific region held about 39.14% of the global share of the Automotive Gear Shift System Market in 2025 and is expected to witness the highest CAGR growth of approximately 4.8% through the forecast period from 2026-2035, owing to the huge vehicle manufacturing capability along with the increasing number of manufacturing bases of electric vehicles in the region. China is the biggest contributor among the regions owing to the wide range of automotive assembly operations along with the increasing electric vehicle manufacturing that requires shift-by-wire technology.
In addition to this, India and Japan provide regional demand for gear shifts systems, wherein the increasing production of domestic vehicles in India will result in the growing demand for efficient manual and automatic gear shift systems, while the presence of automotive electronics manufacturing operations in Japan will lead to shift-by-wire technology development.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Gear Shift System Market Insights
North America represents a significant regional market for automotive gear shift systems, anchored by the United States' large vehicle production base and its concentration of leading shift-by-wire technology developers. The United States accounts for the substantial majority of regional demand, reflecting both its vehicle production scale and its technological leadership in electronic shift system development.
Canada and Mexico contribute additional regional volume through cross-border automotive supply chain integration linked to broader North American vehicle assembly. Continued domestic shift toward electric and autonomous vehicles, along with government incentives supporting electric vehicle adoption, further supports steady regional demand growth for advanced gear shift technology.
Europe Automotive Gear Shift System Market Insights
The Europe region is one of the important regional markets for automotive gearshift systems because of the presence of Germany, which is known for having a substantial automotive manufacturing industry and for housing a number of luxury car manufacturers who have incorporated shift-by-wire technology in their cars. The presence of Germany in the Europe market is justified by its significant share in vehicle production in the region and in the market.
Apart from Germany, France and the United Kingdom add to the regional demand due to their substantial automotive manufacturing industry. The ongoing concern of the European Union regarding carbon dioxide emissions and the shift towards electrified engines keeps the demand steady.
MEA & Latin America Automotive Gear Shift System Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where rising vehicle imports and growing automotive assembly initiatives are gradually increasing component demand. South Africa continues to anchor gear shift system-related demand on the African continent, supported by its comparatively more developed automotive assembly and export base.
Latin America's Automotive Gear Shift System Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle assembly base and its role as a regional export hub for automakers operating in the region. Gradual industrial modernization and rising vehicle production across Brazil and Mexico continue to support steady regional demand growth.
Market Dynamics
Growth Drivers: Electrification and Regulatory Emissions Pressure
The increasing shift of the automotive sector towards the use of electronically controlled transmission system will drive the growth of the Automotive Gear Shift System Market, given stringent regulations governing CO2 emissions coupled with the development of advanced powertrain systems requiring software-controlled shifting gears. This is because consumers are increasingly seeking driving ease and comfort, thus the increasing preference for automatic and dual-clutch transmission systems over conventional manual transmissions.
The increasing use of shift-by-wire technology in both hybrid and electric vehicles presents yet another major source of demand for the market, given that shift-by-wire technology involves the removal of mechanical linkages to allow incorporation with self-driving algorithms and small cabins. Increasing preference for automated transmissions in fleet operators that save on driver training also contributes to market growth.
Restraints: Manual Transmission Decline and Cost Pressure in Mature Markets
The gradual phasing out of manual transmission automobiles in North America and Europe is a sophisticated limitation on the market for the Automotive Gear Shift System Market because while it increases the use of electronic shift systems, it decreases the need for mechanical shift systems. This poses challenges to suppliers who have been producing products for manual transmission automobiles and need to change direction towards the production of electronic and automatic shift products.
The ongoing competitive prices in developing countries prevent suppliers from maximizing the profits realized from electronic shift technology because manual and mechanical shift systems have significant shares due to competitive pricing. The unpredictable prices of raw materials and semiconductors pose additional challenges.
Opportunities: Shift-By-Wire Expansion and Software-Defined Vehicle Integration
Continued expansion of shift-by-wire technology adoption presents a substantial growth opportunity for the Automotive Gear Shift System Market, as automakers increasingly seek software-controllable shift architectures that integrate with broader vehicle digitization and autonomous driving development. Suppliers that can demonstrate validated, cost-competitive shift-by-wire solutions are well positioned to capture share as electric and hybrid vehicle production continues to accelerate globally.
Rising integration of predictive gear control technologies and adaptive shift algorithms presents a longer-term opportunity for suppliers to extend their product portfolios into higher-value, software-integrated shift system solutions. As software-defined vehicle platforms continue to mature, suppliers with established electronic and digital shift technology development capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2026: ZF continued advancing its by-wire technology portfolio as part of its broader software-defined vehicle strategy, with ongoing development of network-capable by-wire actuators and integrated vehicle control technologies.
- 2026: Magna introduced its DHD Duo scalable hybrid drive architecture, featuring a modular gearset configurable from one to four gears and designed to support multiple hybrid propulsion configurations across vehicle platforms.
Automotive Gear Shift System Market Key Players are:
- ZF Friedrichshafen AG
- Aisin Corporation
- BorgWarner Inc.
- Robert Bosch GmbH
- Continental AG
- JTEKT Corporation
- Dura Automotive Systems LLC
- Fuji Kiko Co., Ltd.
- GHSP
- Jopp Holding GmbH
- Kongsberg Automotive ASA
- Panasonic Corporation
- KÜSTER Holding GmbH
- Eissmann Automotive Deutschland GmbH
- Ficosa International S.A.
- Tokai Rika Co., Ltd.
- Alps Alpine Co., Ltd.
- Kostal Automobil Elektrik GmbH & Co. KG
- Marelli Holdings Co., Ltd.
- Magna International Inc.
Automotive Gear Shift System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.16 Billion |
| Market Size by 2035 | USD 28.99 Billion |
| CAGR | CAGR of 3.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Transmission Type (Manual, Automatic, Semi-Automatic, and Dual-Clutch) • By Technology (Mechanical, Electronic/Shift-By-Wire, and Hydraulic) • By Vehicle Type (Passenger Cars and Light Commercial Vehicles) • By Sales Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ZF Friedrichshafen AG; Aisin Corporation; BorgWarner Inc.; Robert Bosch GmbH; Continental AG; JTEKT Corporation; Dura Automotive Systems LLC; Fuji Kiko Co., Ltd.; GHSP; Jopp Holding GmbH; Kongsberg Automotive ASA; Panasonic Corporation; KÜSTER Holding GmbH; Eissmann Automotive Deutschland GmbH; Ficosa International S.A.; Tokai Rika Co., Ltd.; Alps Alpine Co., Ltd.; Kostal Automobil Elektrik GmbH & Co. KG; Marelli Holdings Co., Ltd.; Magna International Inc. |
Frequently Asked Questions
Leading companies in the Automotive Gear Shift System Market include ZF Friedrichshafen, Aisin Corporation, BorgWarner, Robert Bosch, and Continental, among others.
Key opportunities include continued expansion of shift-by-wire technology adoption across electric and hybrid vehicle platforms, and rising integration of predictive gear control technologies with software-defined vehicle systems.
The automotive industry's continued pivot toward electronically controlled transmission architectures, driven by tightening CO2 emissions regulations and vehicle electrification, is the major factor driving market growth.
The Mechanical segment dominated the Automotive Gear Shift System Market with approximately 42.00% share in 2025.
Asia Pacific dominated the Automotive Gear Shift System Market in 2025 with approximately 39.14% share, reflecting the region's massive vehicle production scale, led by China.
