
Automotive Navigation Systems Market Report Scope & Overview:
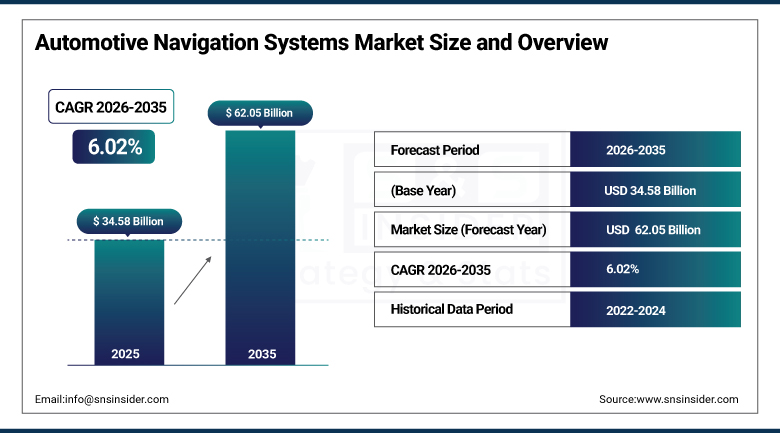
The Automotive Navigation Systems Market was valued at USD 34.58 Billion in 2025 and is expected to reach USD 62.05 Billion by 2035, growing at a CAGR of 6.02% from 2026-2035.
Automotive navigation systems are the electronic devices and software integrated into vehicles that leverage Global Navigation Satellite Systems to deliver accurate location tracking and route guidance, spanning everything from a smartphone mounted on a dashboard through fully embedded, factory-installed infotainment navigation. What began as a simple point-to-point routing tool has evolved into a genuinely central node of the modern connected car experience, increasingly fused with advanced driver assistance systems, real-time traffic intelligence, and now artificial intelligence capable of understanding natural language requests and proactively suggesting routes based on live conditions. Growth is supported by consumer demand for convenience, rising vehicle production, and government safety regulations that in several major markets require embedded navigation and emergency calling capability as standard vehicle equipment.
At CES 2026, HERE Technologies unveiled a new portfolio for software-defined vehicles built around AI-powered map intelligence, showcasing in collaboration with Qualcomm Technologies how its real-time, AI-driven mapping integrates with the Snapdragon Ride Pilot system to enhance Level 2-plus automated driving, while separately announcing a collaboration with Amazon to develop AI-powered conversational navigation combining HERE Navigation with Amazon's Alexa Custom Assistant.
To Get more information On Automotive Navigation Systems Market - Request Free Sample Report
Automotive Navigation Systems Market Trends
- Rising integration of AI-powered conversational assistants enabling natural language navigation requests.
- Growing adoption of edge-based, on-device AI navigation reducing reliance on continuous cloud connectivity.
- Expanding fusion of navigation platforms with advanced driver assistance and automated driving systems.
- Increasing use of lane-level, high-definition mapping supporting Level 2-plus and higher automation.
- Rising partnership activity between mapping companies and automotive AI platform developers.
- Growing demand for electric vehicle-optimised navigation accounting for charging stops and range constraints.
U.S. Automotive Navigation Systems Market Overview
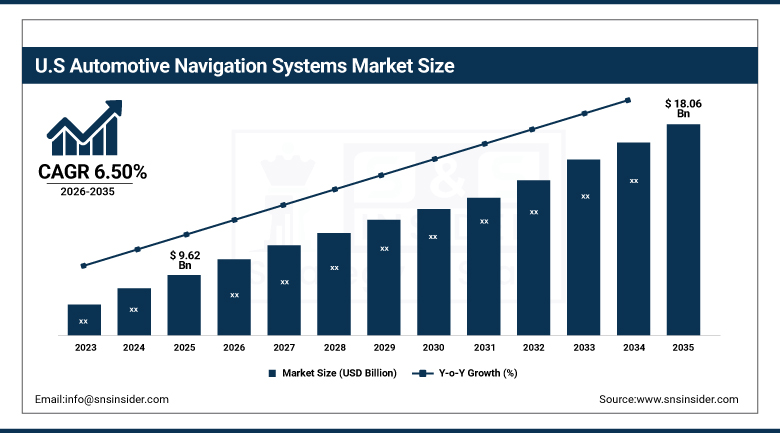
The U.S. Automotive Navigation Systems Market was valued at USD 9.62 Billion in 2025 and is expected to reach USD 18.06 Billion by 2035, growing at a CAGR of 6.50% from 2026-2035.
The U.S. Automotive Navigation Systems Market benefits from a large vehicle parc, strong consumer demand for connected car technology, and the presence of leading navigation software, and automotive technology companies in the country that continue to compete on artificial intelligence capability and software-defined vehicle readiness. Automakers building for the U.S. market continue to prioritise over-the-air-updatable navigation platforms that can evolve alongside broader vehicle software, rather than the fixed, difficult-to-update embedded systems. Leading automotive suppliers headquartered in the country continue to form strategic partnerships with mapping and AI companies to accelerate development of genuinely differentiated in-cabin navigation experiences, reflecting the shortened development cycles automakers increasingly demand as vehicle production timelines compress from roughly four years toward eighteen to twenty-four months.
In January 2026, Visteon Corporation and TomTom announced a strategic collaboration to deliver what the companies describe as the world's first in-car local AI conversational navigation assistant, integrating Visteon's cognitoAI platform with TomTom's Automotive Navigation Application to create a privacy-first navigation experience that operates primarily on-device rather than depending on continuous cloud connectivity.
Automotive Navigation Systems Market Segment Analysis
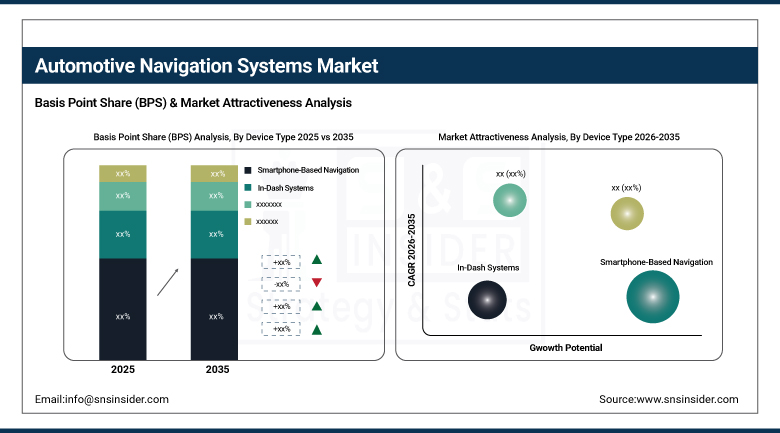
- By Device Type, the Smartphone-Based Navigation segment dominated the market with a 48.11% share in 2025, while the In-Dash Systems segment is the fastest growing with a CAGR of 12.84% during 2026-2035.
- By Technology, the 2D Navigation segment dominated the market with a 45.60% share in 2025, while the Augmented Reality Navigation segment is the fastest growing with a CAGR of 9.10% during 2026-2035.
- By Vehicle Type, the Passenger Cars segment dominated the market with a 77.58% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of 10.12% during 2026-2035.
- By Connectivity, the Embedded Systems segment dominated the market with a 64.41% share in 2025, while the Connected Systems segment is the fastest growing with a CAGR of 11.68% during 2026-2035.
- By Component, the Hardware segment dominated the market with a 46.85% share in 2025, while the Software segment is the fastest growing with a CAGR of 9.25% during 2026-2035.
- By Sales Channel, the OEM segment dominated the market with a 68.40% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of 8.15% during 2026-2035.
By Device Type, Smartphone-Based Navigation Dominates the Market and In-Dash Systems Grows Fastest
Smartphone-based navigation dominated the market in 2025 with a 48.11% share. The near-universal ownership of smartphones equipped with sophisticated, frequently updated mapping applications continues to make this the most accessible and cost-free navigation option available to the overwhelming majority of drivers worldwide, and many vehicles, particularly in lower and mid-range price segments, continue to rely on smartphone integration through platforms such as Apple CarPlay and Android Auto rather than a dedicated, factory-embedded system. The continuous, automatic update cycle smartphone mapping applications enjoy, free of the multi-year development and validation cycles embedded automotive systems typically require, continues to give this device type a genuine functional advantage that keeps it the largest category by a considerable margin over every dedicated hardware alternative.
In-dash systems are projected to be the fastest-growing device type over the forecast period, registering a CAGR of 12.84%, as automakers increasingly integrate navigation deeply within broader vehicle software architecture, enabling tighter coordination with advanced driver assistance systems, vehicle diagnostics, and increasingly sophisticated in-cabin AI assistants that a smartphone-based solution simply cannot replicate given its inherent separation from the vehicle's own sensors and control systems. Rising software-defined vehicle adoption, combined with shortened development cycles that now allow automakers to deploy customised in-dash navigation applications in a matter of weeks rather than years, continues to accelerate this category's above-market growth relative to the broader smartphone-dominated device mix.
By Technology, 2D Navigation Dominates the Market and Augmented Reality Navigation Grows Fastest
The 2D Navigation segment dominated the Automotive Navigation Systems Market in 2025. Its leading position is supported by widespread integration across passenger and commercial vehicles, established navigation infrastructure, and relatively lower system complexity compared with advanced visualization technologies. 2D navigation provides essential route guidance, mapping, traffic information, and point-of-interest functions at comparatively accessible costs. Its compatibility with embedded infotainment systems and broad availability across vehicle price categories continue to sustain demand, particularly among mainstream vehicles where cost efficiency and dependable navigation functionality remain important purchasing considerations.
The Augmented Reality Navigation market segment is expected to witness the highest growth rate between 2026 and 2035. The growing uptake of modern driver assistance systems, connected cars and digital cockpits has driven the need for navigation systems that can display the routing details directly in front of the driver. Augmented reality navigation allows for overlaying of guidance details, road details, lane details and other location-based details on top of the actual surroundings and provides contextual awareness. The automotive companies are increasingly embedding advanced visualization features in premium cars.
By Vehicle Type, Passenger Cars Dominates the Market and Commercial Vehicles Grows Fastest
Passenger cars dominated the market in 2025 with a 77.58% share. The sheer global production and ownership volume of passenger vehicles continues to anchor this vehicle type as the overwhelming source of automotive navigation demand, reinforced by rising consumer expectation that even entry-level passenger vehicles ship with some form of navigation capability, whether embedded or smartphone-integrated, as a now-standard rather than premium feature. Automakers across nearly every price segment continue to compete on infotainment and navigation experience quality as a genuine point of consumer differentiation, sustaining passenger cars' position as the clear largest vehicle type category across the broader market.
Commercial vehicles are projected to be the fastest-growing vehicle type over the forecast period, registering a CAGR of 10.12%, as fleet operators increasingly adopt sophisticated navigation systems capable of handling complex routing constraints, including vehicle height and weight restrictions, mandated rest stops, and multi-stop delivery optimisation that consumer-grade navigation was never designed to address. Rising e-commerce-driven freight volumes and growing fleet electrification, which introduces genuinely new charging-stop routing requirements, continue to drive above-market growth for this vehicle type relative to the broader passenger-car-dominated vehicle mix.
By Connectivity, Embedded Systems Dominates the Market and Connected Systems Grows Fastest
Embedded systems dominated the market in 2025 with a 64.41% share, benefiting substantially from the integration of eCall emergency calling systems and sensor fusion capability that regulatory requirements in several major markets now mandate as standard vehicle equipment. Because embedded navigation is built directly into the vehicle's electrical architecture from the factory, it can draw on the vehicle's own sensors, GPS antenna placement, and diagnostic systems in ways a tethered or smartphone-based alternative cannot, and this deep integration advantage, combined with regulatory mandates in multiple regions, continues to anchor embedded systems as the clear leading connectivity category across the broader automotive navigation systems market.
Connected systems are projected to be the fastest-growing connectivity category over the forecast period, registering a CAGR of 11.68%, as rising cellular and cloud connectivity adoption continues to enable real-time traffic updates, over-the-air map refreshes, and increasingly sophisticated AI-powered features that a purely offline embedded system cannot deliver on its own. The automotive navigation system services market is forecast to double between 2026 and 2031 according to industry analysis, reflecting genuinely accelerating demand for the subscription-based connected services increasingly layered atop core navigation hardware, positioning connected systems for sustained above-market growth relative to the broader embedded-dominated connectivity mix.
By Component, Hardware Dominates the Market and Software Grows Fastest
Hardware dominated the market in 2025. GPS receivers, sensors, displays, and the underlying processing units that power every navigation system, whether embedded or portable, continue to represent the physical foundation without which no navigation capability, however sophisticated the software layer above it, can function at all, sustaining hardware's position as the largest component category across the broader automotive navigation systems market.
Software is projected to be the fastest-growing component over the forecast period, registering a CAGR of 9.25%, as the rise of AI-powered maps and increasingly sophisticated navigation intelligence continues to shift meaningful value away from the underlying hardware and toward the software layer that determines route quality, predictive accuracy, and the natural language conversational capability rapidly becoming a genuine competitive differentiator across the industry. Continued advancement in AI-powered predictive navigation, which anticipates traffic conditions and driver preferences before a driver even requests a route, continues to reinforce software's accelerating growth relative to the broader hardware-dominated component mix.
By Sales Channel, OEM Dominates the Market and Aftermarket Grows Fastest
OEM installation dominated the market in 2025. Automakers continue to specify navigation systems directly into new vehicles during original design and manufacturing, ensuring proper integration with the vehicle's broader electrical and infotainment architecture, and this factory-fit approach continues to account for the overwhelming majority of overall market volume as embedded navigation becomes an increasingly standard, rather than optional, feature across new vehicle production worldwide.
The aftermarket is projected to be the fastest-growing sales channel over the forecast period, registering a CAGR of 8.15%, as owners of older vehicles equipped only with basic or outdated navigation systems increasingly seek aftermarket upgrade options, and growing awareness of retrofit smartphone integration kits and portable navigation devices continues to drive above-market growth for this channel relative to the broader OEM-dominated sales mix.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
33.48% |
|
North America |
United States |
85.90% |
|
Europe |
Germany |
27.35% |
|
Latin America |
Brazil |
23.60% |
|
Middle East & Africa |
United Arab Emirates |
20.85% |
Asia Pacific Automotive Navigation Systems Market Insights
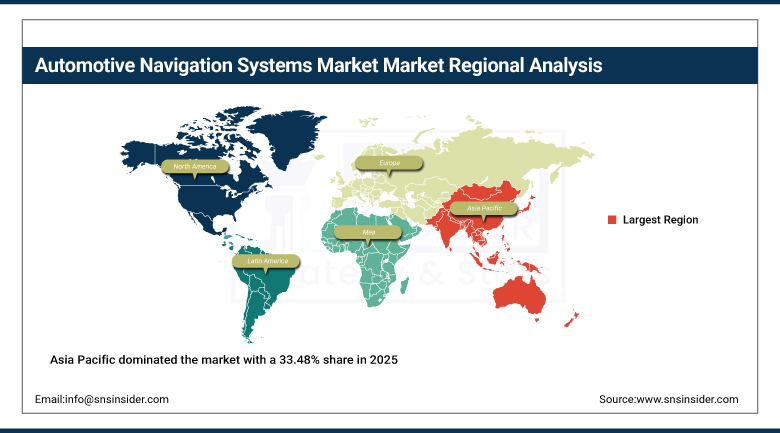
Asia Pacific dominated the market with a 33.48% share in 2025, and the region is also projected to grow at a CAGR of approximately 7.85% through the forecast period. The region's position as the world's largest vehicle production base, combined with rapidly expanding domestic electric vehicle manufacturing and growing consumer demand for connected in-cabin technology, continues to anchor this leadership position across both established and emerging automotive markets throughout the region.
China anchors regional demand through its substantial vehicle manufacturing base and rapidly expanding electric vehicle production, supported by a fast-growing ecosystem of domestic mapping and navigation technology providers competing alongside established international players. Japan and South Korea contribute additional regional depth through established automotive electronics supply chains and early AI navigation adoption, while India's expanding vehicle production and growing middle-class consumer base continue to add meaningful incremental regional growth as domestic automakers extend navigation capability across a broader range of price segments.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Navigation Systems Market Insights
North America was the significant region in the automotive navigation systems market in 2025, according to industry analysis, anchored overwhelmingly by the United States, which alone represents a substantial majority of overall regional revenue. Strong consumer demand for connected vehicle technology, a concentration of leading mapping and navigation software companies headquartered within the region, and rapid adoption of software-defined vehicle architecture among domestic automakers continue to sustain the region's position among the largest and most technologically advanced automotive navigation markets in the world.
Canada contribute additional regional demand through vehicle manufacturing and assembly operations closely integrated with U.S. automotive supply chains. Continued strategic partnership activity between automotive suppliers and leading mapping and AI companies, combined with rising electric vehicle adoption requiring navigation platforms capable of managing charging infrastructure and range constraints, is expected to sustain strong regional demand growth through the forecast period.
Europe Automotive Navigation Systems Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial automotive manufacturing base and its position as home to several premium automakers and leading mapping technology companies that have driven navigation innovation across the region for decades. The region's deep automotive engineering expertise and early adoption of advanced driver assistance integration continue to sustain steady demand across every major navigation device and connectivity category.
The United Kingdom, France, and Italy add consistent regional demand as national automakers continue extending advanced navigation and AI-powered assistant capability across broader vehicle segments beyond traditional premium models alone. Continued European regulatory emphasis on vehicle safety, including mandated emergency calling capability across new vehicles, continues to reinforce sustained embedded navigation system demand across the broader regional market.
MEA and Latin America Automotive Navigation Systems Market Insights
The Middle East and Africa region is supported by growing premium and luxury vehicle sales across the United Arab Emirates and Saudi Arabia, where rising consumer demand for advanced in-vehicle technology continues to expand regional adoption of sophisticated navigation and connected car capability across an increasingly affluent regional vehicle-owning population.
Latin America is anchored by Brazil, where a substantial domestic vehicle manufacturing sector sustains steady navigation system demand across both passenger and commercial vehicle segments. Mexico contributes further incremental growth given its deep integration into North American automotive supply chains and its growing role as a manufacturing base for vehicles destined for both domestic and export markets.
Growth Drivers: Connected Car Adoption and AI-Powered Mapping Innovation
Connected car adoption stands as the primary growth driver, as rising traffic congestion, government safety regulations, and consumer demand for convenience continue to drive integration of increasingly sophisticated navigation systems with broader advanced driver assistance and automated driving capability. Growing electric vehicle adoption reinforces this trend, as EV drivers require navigation platforms capable of accounting for charging infrastructure availability and range constraints in ways combustion vehicle navigation never needed to address, creating genuinely new functional requirements that continue to drive platform innovation across the entire industry.
The rise of AI-powered maps and cloud-based navigation platforms represents a second major driver, as smart city development and expanding integration with advanced driver assistance systems continue to widen the addressable market for genuinely intelligent, context-aware navigation capability. Continued advancement in natural language conversational navigation, capable of understanding complex driver requests without requiring precise destination input, continues to reinforce sustained platform investment across every major automotive market as this capability rapidly shifts from a premium differentiator toward a genuinely expected standard feature.
Restraints: Integration Complexity and Smartphone Competition
Integration complexity remains a genuine restraint, as embedded navigation systems must coordinate reliably with a vehicle's broader electrical and infotainment architecture, a technical undertaking that continues to extend development timelines and add engineering cost relative to simpler, standalone navigation solutions that operate independently of deeper vehicle system integration.
Competition from free, continuously updated smartphone navigation applications presents a further restraint, as many consumers, particularly in price-sensitive vehicle segments, continue to question the value of paying a premium for embedded navigation capability when a smartphone mounted on the dashboard delivers comparable or superior mapping accuracy at no additional cost, a competitive pressure that continues to push embedded system providers toward deeper vehicle integration and AI capability that a smartphone genuinely cannot replicate as the primary basis for differentiation.
Opportunities: Software-Defined Vehicle Platforms and AI Conversational Navigation
Continued development of software-defined vehicle navigation platforms represents a substantial opportunity, as suppliers that can deliver genuinely flexible, rapidly deployable, over-the-air-updatable navigation applications stand to capture demand from automakers seeking to compress development cycles from years toward months while maintaining the ability to continuously improve navigation capability throughout a vehicle's entire service life.
Continued advancement of AI-powered conversational navigation offers a further avenue for growth, as companies that can deliver genuinely natural, privacy-conscious, and reliably accurate voice-driven navigation experiences are positioned to capture demand from automakers and consumers alike increasingly expecting their vehicle to understand plain-language requests rather than requiring precise, structured destination input, a capability gap that continues to separate genuinely differentiated navigation platforms from more commoditised alternatives.
Recent Developments
- 2026: Garmin Ltd. expanded its automotive technology collaboration with Qualcomm by introducing the Nexus high-performance computing platform, integrating localization, perception, vehicle control, and map functionality for future vehicle programs.
- 2026: Robert Bosch GmbH introduced its AI-powered cockpit platform at CES 2026, incorporating precise navigation, AI-based scene understanding, voice assistance, and integrated cockpit functions for next-generation vehicles.
- 2026: Continental AG advanced integrated cockpit and vehicle-computing technologies supporting navigation, infotainment, driver assistance, and software-defined vehicle architectures.
Automotive Navigation Systems Companies are:
- Garmin Ltd.
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Alps Alpine Co., Ltd.
- Pioneer Corporation
- TomTom N.V.
- HERE Global B.V.
- Harman International Industries (Samsung)
- Panasonic Automotive Systems Co., Ltd.
- Aisin Corporation
- Visteon Corporation
- Clarion Co., Ltd. (Forvia)
- Mitsubishi Electric Corporation
- JVCKenwood Corporation
- LG Electronics Inc.
- Apple Inc.
- Google LLC
- Qualcomm Incorporated
- NVIDIA Corporation
Automotive Navigation Systems Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 34.58 Billion |
| Market Size by 2035 | USD 62.05 Billion |
| CAGR | CAGR of 6.02% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Smartphone-Based Navigation, In-Dash Systems, Portable Navigation Devices) • By Technology (2D Navigation, 3D Navigation, Augmented Reality Navigation, AI-Enhanced Navigation) • By Vehicle Type (Passenger Cars, Commercial Vehicles) • By Connectivity (Embedded Systems, Connected Systems, Tethered Systems) • By Component (Hardware, Software, Services) • By Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Garmin Ltd., Robert Bosch GmbH, Continental AG, Denso Corporation, Alps Alpine Co., Ltd., Pioneer Corporation, TomTom N.V., HERE Global B.V., Harman International Industries (Samsung), Panasonic Automotive Systems Co., Ltd., Aisin Corporation, Visteon Corporation, Clarion Co., Ltd. (Forvia), Mitsubishi Electric Corporation, JVCKenwood Corporation, LG Electronics Inc., Apple Inc., Google LLC, Qualcomm Incorporated, NVIDIA Corporation. |
Frequently Asked Questions
Key players include Garmin Ltd., Robert Bosch GmbH, Continental AG, Denso Corporation, TomTom N.V., and HERE Global B.V., among other automotive technology and mapping companies.
Continued development of software-defined vehicle navigation platforms and continued advancement of AI-powered conversational navigation represent the primary opportunities.
Growth is primarily driven by connected car adoption, combined with the rise of AI-powered maps and cloud-based navigation platforms.
By Device Type, Smartphone-Based Navigation dominated the market with a 48.11% share in 2025, reflecting the near-universal accessibility of smartphone mapping applications.
Asia Pacific dominated the market with a 33.48% share in 2025, supported by the region's position as the world's largest vehicle production base.
