
Automotive Radiator Fan Market Report Scope & Overview:
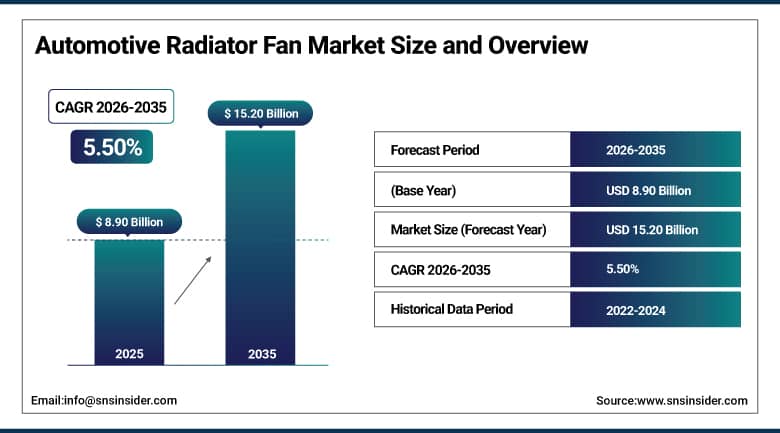
The Automotive Radiator Fan Market was valued at USD 8.90 Billion in 2025 and is expected to reach USD 15.20 Billion by 2035, growing at a CAGR of 5.50% from 2026–2035.
An automotive radiator fan is a critical component of a vehicle's cooling system, designed to regulate engine temperature by dissipating heat and drawing air through the radiator to cool the engine coolant. The fan is typically electrically operated and activates when the engine reaches a certain temperature or when the air conditioning is in use, and vehicles would not run at optimum levels without this component operating correctly, since a flawed cooling mechanism can directly affect other engine systems and cause them to misfire or malfunction. Increasing automotive production globally, fueled by rising consumer demand for vehicles, has created a concurrent rise in the need for efficient cooling solutions, while the shift toward more advanced automotive technologies such as electric and hybrid vehicles is opening entirely new avenues for radiator fan manufacturers.
SPAL Automotive, based in Italy and a global leader in automotive thermal management, has spent decades developing brushless motor technology specifically to keep pace with battery and hybrid vehicle cooling requirements, with its latest fans carrying IP68 and IP6K9K sealing ratings that make them completely waterproof and dustproof. That level of environmental sealing matters more than it might seem for a fan spinning behind a radiator grille: as electric and hybrid vehicles route more coolant through battery packs and power electronics rather than just an engine block, a fan failure now risks thermal problems well beyond the traditional engine overheating scenario the component was originally designed to prevent.
To Get More Information On Automotive Radiator Fan Market - Request Free Sample Report
Automotive Radiator Fan Market Trends:
-
Rising adoption of brushless electric motor technology delivering longer service life and reduced noise relative to traditional brushed designs
-
Growing preference for aluminum radiator fans over steel and copper alternatives, driven by lighter weight and superior corrosion resistance
-
Increasing demand for advanced thermal management systems supporting battery and power electronics cooling in electric and hybrid vehicles
-
Expanding direct-fit fan designs offering ready-to-install compatibility that eliminates the need for engine or body modifications
-
Growing integration of smart, variable-speed fan control systems optimizing cooling performance while reducing parasitic power draw
-
Rising commercial vehicle demand for heavy-duty cooling solutions supporting extended engine life under continuous, high-load operation
U.S. Automotive Radiator Fan Market Outlook:
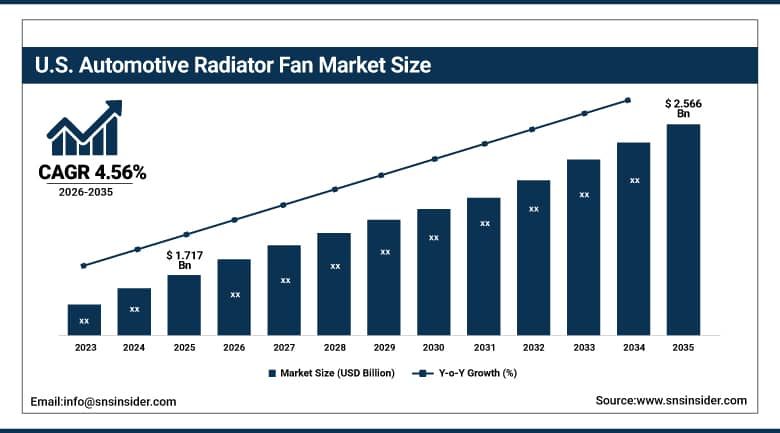
The U.S. Automotive Radiator Fan Market was valued at approximately USD 1.717 Billion in 2025 and is expected to reach approximately USD 2.566 Billion by 2035, growing at a CAGR of approximately 4.56%.
Demand in the United States is fueled by rising demand for automobiles that have been shaped through the use of technology in manufacturing fans for the automobiles. The demand for electric cars is creating new opportunities for domestic manufacturers of radiator fans in the country. While passenger automobiles will remain to dominate the market, commercial automobiles are now becoming a real fast-growing industry since there is increased demand for heavy-duty cooling systems among truckers and logistics companies.
Industry analysis of the broader vehicle brushless cooling fan category found a genuinely oligopolistic market structure, with the top five suppliers, including Johnson Electric, Mahle, and Hanon Systems, accounting for a substantial share of global revenue in 2025, driven by rising demand for electrified powertrain cooling and modular front-end cooling systems. That concentration matters for American automakers sourcing radiator fans, since it means most U.S. vehicle platforms ultimately draw from the same small pool of specialized thermal management suppliers regardless of which brand badge ends up on the hood.
Automotive Radiator Fan Market Segment Analysis:
-
By Fan Type, the Electric segment dominated the Automotive Radiator Fan Market with approximately 68.40% share in 2025, and is also the fastest growing with a CAGR of approximately 6.80%.
-
By Fit Type, the Direct Fit segment dominated the Automotive Radiator Fan Market with approximately 67.20% share in 2025, while the Universal Fit segment is the fastest growing with a CAGR of approximately 6.40%.
-
By Material, the Aluminum segment dominated the Automotive Radiator Fan Market with approximately 46.60% share in 2025, and is also the fastest growing with a CAGR of approximately 6.90%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Radiator Fan Market with approximately 62.40% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.60%.
-
By Sales Channel, the OEM segment dominated the Automotive Radiator Fan Market with approximately 71.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 6.20%.
By Fan Type, Electric dominates and grows fastest
Electric fans held the largest share of the fan-type segment in 2025, valued for their ability to activate independently of engine speed, running only when the engine reaches a certain temperature or when air conditioning is in use, which reduces parasitic power draw relative to mechanically driven fans permanently coupled to the engine. That combination of efficiency and precise, condition-responsive activation keeps electric fans the dominant fan-type category across the broader automotive radiator fan market.
Electric fans are also the fastest-growing fan-type category, an unusual case where the already-dominant segment continues gaining share as brushless motor technology and smart, variable-speed control systems continue displacing mechanical fan designs entirely. The rise of electric and hybrid vehicles, which depend on electrically driven cooling for both engine and battery thermal management, continues reinforcing this above-average growth trajectory relative to the declining mechanical fan alternative.
By Fit Type, Direct Fit dominates, Universal Fit grows fastest
Direct fit fans held the largest share of the fit-type segment in 2025, offering high vehicle compatibility and ease of installation with a ready-to-install design that eliminates the need for modifications to the engine or vehicle body. That installation convenience and cost efficiency keep direct fit designs the dominant fit-type category across both OEM and aftermarket applications.
Universal fit fans are growing fastest as aftermarket customization and performance vehicle applications continue favoring flexible, adaptable fan designs that can be configured across a wider range of vehicle makes and models. Growing demand for aftermarket customization and specialty vehicle cooling upgrades continues reinforcing this above-average growth trajectory relative to the broader, direct-fit-dominated fit-type mix.
By Material, Aluminum dominates and grows fastest
Aluminum held the largest share of the material segment in 2025, valued for its lighter weight and superior corrosion resistance compared to steel and copper alternatives, properties that directly support broader vehicle fuel efficiency and durability goals. That combination of weight savings and long-term durability keeps aluminum the dominant material choice across the broader automotive radiator fan market.
Aluminum is also the fastest-growing material category as manufacturers continue prioritizing lightweight components across nearly every vehicle system to offset the added weight of battery packs in electric and hybrid vehicle platforms. Stringent emission regulations globally pushing for improved engine cooling efficiency continue reinforcing this above-average growth trajectory relative to the broader steel and composite material alternatives.
By Vehicle Type, Passenger Cars dominates, Commercial Vehicles grows fastest
Passenger cars held the largest share of the vehicle-type segment in 2025, reflecting the sheer scale of global passenger vehicle production and sales relative to commercial vehicle output in any given year. That production and sales scale keeps passenger cars the dominant vehicle-type category across the broader automotive radiator fan market.
Commercial vehicles are emerging as the fastest-growing vehicle-type segment due to the increasing demand for heavy-duty cooling solutions that support extended engine life under continuous, high-load operation across trucks, buses, and other commercial platforms. Growing freight transportation volume and fleet modernization investment continue reinforcing this above-average growth trajectory relative to the broader, passenger-car-dominated vehicle-type mix.
By Sales Channel, OEM dominates, Aftermarket grows fastest
OEM sales accounted for the largest share of the sales-channel segment in 2025, reflecting how radiator fans are overwhelmingly factory-installed components specified during vehicle design and assembly rather than purchased separately by the typical new vehicle buyer. That deep integration between fan design and overall vehicle cooling system engineering keeps OEM channels the dominant distribution pathway across nearly every radiator fan category.
The aftermarket is growing fastest as the growing demand for such OEM-equivalent products in the automotive aftermarket and customization sector continues expanding, particularly as an aging global vehicle fleet generates rising demand for radiator fan replacement following component wear or failure. Increased vehicle parc size across both developed and emerging markets continues reinforcing this above-average growth trajectory relative to the broader, OEM-dominated sales-channel mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.60% |
|
North America |
United States |
80.40% |
|
Europe |
Germany |
25.20% |
|
Latin America |
Brazil |
34.80% |
|
Middle East & Africa |
UAE |
29.60% |
Asia Pacific Automotive Radiator Fan Market Insights
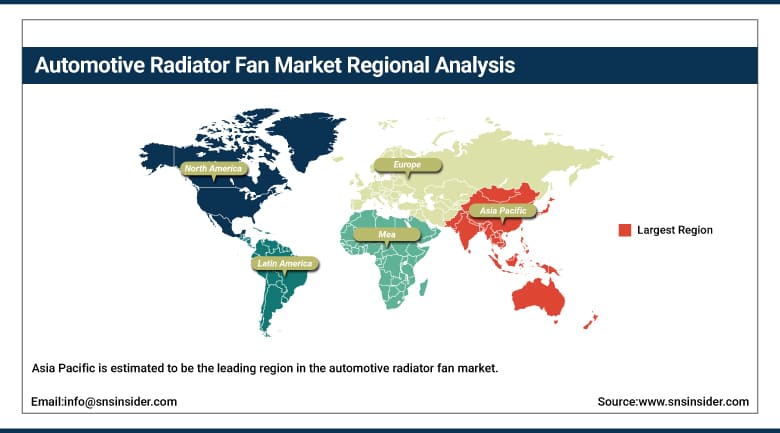
Asia Pacific is estimated to be the leading region in the automotive radiator fan market, driven by the increasing use of passenger cars and commercial vehicles, rapid urbanization, and consistent rise in vehicle production across the region's largest and fastest-growing automotive economies. That combination of manufacturing scale and rising consumer vehicle demand continues reinforcing this leading and accelerating position.
China's massive vehicle production base gives the region substantial baseline demand, while India's rapidly expanding automotive manufacturing sector is drawing significant new investment in radiator fan production capacity. Japan and South Korea represent more mature, technology-forward markets with established brushless motor manufacturing standards, while Southeast Asian markets continue following a similar urbanization-driven growth trajectory as regional manufacturing infrastructure expands.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Radiator Fan Market Insights
North America is a significant market for automotive radiator fans with high concentrations of leading thermal management suppliers and an increase in demand for electric cars creating new opportunities for local manufacturers. The largest part of demand is represented by the United States, where there is an increase in the number of car productions and innovations influencing the domestic automotive cooling industry.
Demand from Canada is added through their car sales and cooling systems requirements in cold climate conditions, and the demand from Mexico is growing due to the growth of nearshoring automotive manufacturing. Supply relations between the countries unite demand in North America, and major suppliers usually provide products to all three markets.
Europe Automotive Radiator Fan Market Insights
Europe represents a mature, technically advanced automotive radiator fan market, shaped by stringent emission regulations globally pushing for improved engine cooling efficiency across the region's largest automotive manufacturing economies. Germany anchors regional demand, home to a large automotive manufacturing base and several major thermal management suppliers with deep engineering expertise.
France and Italy contribute meaningful volume as well, each with substantial automotive manufacturing sectors adapting to tightening EU emissions and fuel-efficiency requirements. Growing regional emphasis on brushless motor technology and lightweight aluminum construction continues shaping product development across the region more directly than in most other global markets.
MEA & Latin America Automotive Radiator Fan Market Insights
The Middle East and Africa represent a smaller but developing automotive radiator fan market, with the UAE driving demand through growing vehicle sales and automotive retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader automotive manufacturing and vehicle ownership infrastructure development.
Latin America is a growing market led by Brazil, where expanding vehicle production and rising consumer demand for fuel-efficient vehicles continue driving radiator fan adoption. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing automotive manufacturing sectors.
Market Dynamics:
Growth Drivers: Rising vehicle production and electric vehicle adoption fueling adoption
Increasing use of passenger cars and commercial vehicles, along with rapid urbanization, is one of the clearest forces behind rising automotive radiator fan demand, as growth in the automotive industry and surge in vehicle production continue expanding the addressable market across nearly every region worldwide. Rising demand for fuel-efficient vehicles continues reinforcing this demand base, as efficient cooling systems directly support the fuel economy gains automakers are pursuing across new vehicle platforms.
The shift toward more advanced automotive technologies such as electric and hybrid vehicles adds a second major driver, opening entirely new avenues for radiator fan manufacturers as these vehicles require sophisticated thermal management for battery packs and power electronics beyond traditional engine cooling. Stringent emission regulations globally pushing for improved engine cooling efficiency continue reinforcing this demand base across nearly every major automotive market.
Restraints: Raw material price volatility and technology transition costs limiting margin stability
Raw material price volatility remains a genuine restraint, since radiator fan manufacturers depend on aluminum, steel, and specialty plastic inputs that remain exposed to broader commodity market swings affecting production costs across the industry. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-fan demand remains steady.
Technology transition costs add a further restraint, as manufacturers face genuine engineering and retooling investment shifting from mechanical to electric fan designs and further toward brushless motor technology required for electric and hybrid vehicle applications. That transition burden falls disproportionately on smaller manufacturers without dedicated engineering and manufacturing capability built into their operations.
Opportunities: Electric vehicle thermal management and brushless motor technology expansion opening new growth avenues
Thermal management in electric vehicles presents a legitimate opportunity for manufacturers in obtaining premium market share among those automakers who require advanced thermal management capabilities for their battery pack and power electronic components, which conventional cooling technologies meant for engines were never capable of handling. Manufacturers who develop advanced thermal management capabilities are well-placed to benefit from premium pricing amid growing demand for electric cars.
Brushless motor technology development is another major opportunity for manufacturers in terms of developing fully waterproof and dustproof fans with extended lifespan compared to conventional ones. Manufacturers who are capable of developing brushless technology can take advantage of premium pricing offered by automakers looking for long-lasting fan technologies in their increasingly electrified vehicle designs.
Recent Developments:
-
In 2025, SPAL Automotive continued expanding its brushless axial fan lineup, featuring IP68 and IP6K9K sealed motors designed for maximum protection against dust and water in demanding automotive applications.
-
In 2025, multiple major suppliers, including Johnson Electric and Mahle, continued developing high-performance cooling fan solutions optimized for noise reduction and electromagnetic compatibility compliance in electrified vehicle platforms.
-
In 2025, emerging Asian manufacturers, including Jiangsu Langxin Electric and Jiangsu Chaoli Electric, continued expanding production capacity to serve China's rapidly accelerating new energy vehicle thermal management demand.
-
In 2025, Hanon Systems continued advancing modular front-end cooling system integration, combining radiator fans with broader vehicle thermal management architecture for both passenger and commercial vehicle platforms.
Automotive Radiator Fan Market Key Players:
-
Johnson Electric Holdings Limited
-
Marelli Holdings Co., Ltd.
-
Hella KGaA Hueck & Co. (Forvia)
-
Mahle GmbH
-
Standard Motor Products, Inc.
-
Robert Bosch GmbH
-
Valeo SA
-
BorgWarner Inc.
-
Brose Fahrzeugteile SE & Co. KG
-
Delta Radiator Fan Ltd.
-
DENSO Corporation
-
SPAL Automotive S.r.l.
-
Continental AG
-
AMETEK, Inc.
-
Nidec Corporation
-
Hanon Systems
-
Mitsuba Corporation
-
Aptiv PLC
-
Sanden Corporation
-
Jiangsu Chaoli Electric Co., Ltd.
Automotive Radiator Fan Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 14.87 Billion |
| Market Size by 2035 | USD 22.82 Billion |
| CAGR | CAGR of 5.3% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Corn, Wheat, Cassava, Potato) • By Application (Food & Beverage, Industrial, Pharmaceutical, Paper & Textile) • By Modification Type (Physically Modified, Chemically Modified, Enzymatically Modified) • By Form (Dry, Liquid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ingredion Incorporated, Cargill, Incorporated, Roquette Frères, Tate & Lyle plc, Archer Daniels Midland Company, Royal Avebe U.A., Emsland Group, Grain Processing Corporation, AGRANA Beteiligungs-AG, Südstärke GmbH, Sanstar Ltd., Global Bio-chem Technology Group Company Limited, Universal Starch-Chem Allied Ltd., Gujarat Ambuja Exports Limited, Manildra Group, KMC (Kartoffelmelcentralen A.m.b.A.), Meihua Holdings Group Co., Ltd., Zhucheng Xingmao Corn Developing Co., Ltd., China Essence Group Limited, Japan Corn Starch Co., Ltd. |
Frequently Asked Questions
Leading companies include Johnson Electric Holdings Limited, Marelli Holdings Co., Ltd., Hella KGaA Hueck & Co., Mahle GmbH, and Standard Motor Products, Inc., among other major automotive thermal management manufacturers.
Opportunities include electric vehicle thermal management for battery and power electronics cooling and brushless motor technology expansion offering longer service life and reduced noise.
Growth is driven by increasing use of passenger cars and commercial vehicles, rapid urbanization, and the shift toward more advanced automotive technologies such as electric and hybrid vehicles.
Electric dominates by fan type with approximately 68.40% share, Direct Fit dominates by fit type with roughly 67.20% share, Aluminum dominates by material with about 46.60% share, and Passenger Cars dominates by vehicle type with approximately 62.40% share; Universal Fit, Commercial Vehicles, and Aftermarket are among the fastest-growing segments within their respective categories, alongside Electric and Aluminum.
Asia Pacific is the largest and fastest-growing regional market, led by China, given the region's rapid urbanization and consistent rise in vehicle production.
