
Automotive Smart Antenna Market Report Scope & Overview:
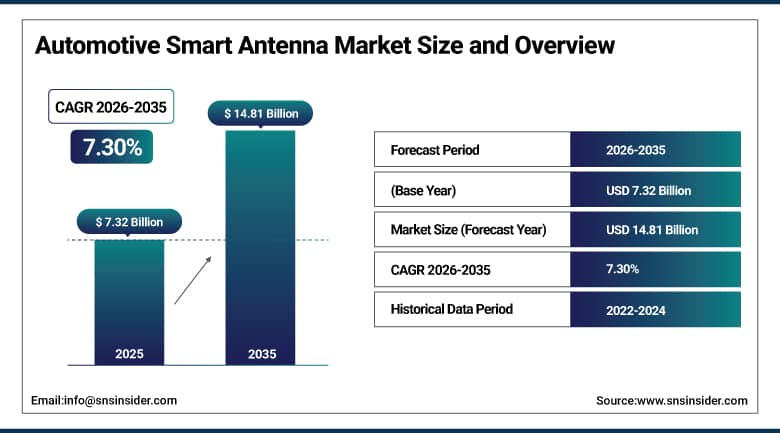
The Automotive Smart Antenna Market was valued at USD 7.32 Billion in 2025 and is expected to reach USD 14.81 Billion by 2035, growing at a CAGR of 7.30% from 2026-2035.
The Automotive Smart Antenna Market is undergoing a structural shift as traditional antennas, which only had the capability of reception, are transitioning to smart antennas, which have the capability of transforming connected cars and autonomous systems and other functionalities such as infotainment, telematics, and navigation. The modern car is equipped with an average of 20 different antennas, and this number is continuing to grow to accommodate all the wireless connectivity that will be needed for functions such as remote keyless entry, navigation, telematics, and cellular connectivity in addition to the coming up of 5G and 6G technology standards. The shark fin antenna module is the common physical module due to its capability of integrating cellular, GNSS, and broadcast antennas into one aerodynamic unit.
In January 2025, Harada Industries announced the launch of its next-generation MIMO 5G shark-fin antenna module for passenger cars, developed in collaboration with a leading Japanese automaker and designed to simultaneously support 5G NR, GNSS, V2X, and Wi-Fi 6E within a single compact unit. The launch reflects a broader supplier strategy of consolidating an expanding number of wireless standards into fewer, more tightly integrated antenna modules, a design direction that is becoming increasingly necessary as vehicles add connectivity requirements faster than available roof and body surface area can accommodate separate dedicated antennas for each function.
To Get More Information On Automotive Smart Antenna Market - Request Free Sample Report
Automotive Smart Antenna Market Trends
- Continued consolidation of multiple wireless standards into single shark-fin and embedded antenna modules.
- Rising adoption of embedded antenna designs integrated into bumpers, spoilers, and mirrors to reduce drag and weight.
- Growing demand for multi-band antennas supporting simultaneous 5G, GNSS, V2X, and Wi-Fi connectivity.
- Expanding battery-electric vehicle production driving demand for antennas engineered for advanced EMI mitigation.
- Increasing supplier investment in in-house RF and phased-array chipset capability to mitigate semiconductor supply risk.
U.S. Automotive Smart Antenna Market Outlook
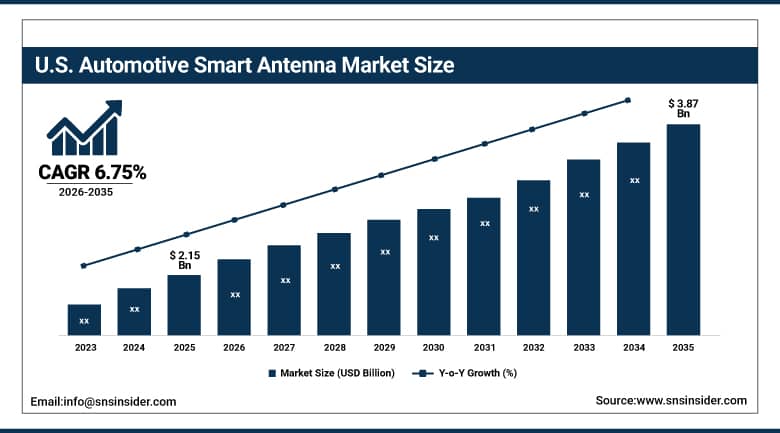
The U.S. Automotive Smart Antenna Market was valued at USD 2.15 Billion in 2025 and is expected to reach USD 3.87 Billion by 2035, growing at a CAGR of 6.75% from 2026-2035.
The U.S. Automotive Smart Antenna Market growth continues to be reinforced by strong The integration of connected vehicle technology in OEMs, aided by the deployment of 5G technology infrastructure by national operators along with the continuous demand of consumers for infotainment and navigation systems on mid- and premium-class automobiles. The domestic demand is steadily shifting towards multi-band shark-fin antennas and embedded antenna modules that will enable all the three types of connections—cellular, GNSS, and V2X—at once.
In January 2025, Texas Instruments unveiled new radar sensor chips featuring 3D wavelength antennas, enhancing compact vehicle sensor integration and supporting the increasingly dense sensor and connectivity packages found in modern advanced driver-assistance systems. The launch illustrates how domestic semiconductor suppliers are extending antenna innovation beyond traditional communication functions into radar and sensing applications, a convergence that is broadening the addressable market for antenna technology suppliers beyond connectivity modules into the sensor fusion hardware that autonomous and semi-autonomous driving features depend on.
Automotive Smart Antenna Market Segment Analysis
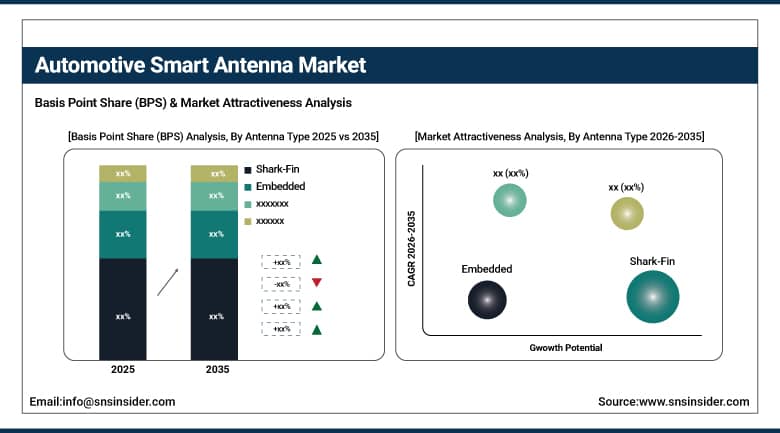
- By Antenna Type, the Shark-Fin segment dominated the Automotive Smart Antenna Market with approximately 58.79% share in 2025, while the Embedded segment is the fastest growing with a CAGR of approximately 12.53%.
- By Connectivity Type, the Cellular segment dominated the Automotive Smart Antenna Market with approximately 35.00% share in 2025, while the GPS/GNSS segment is the fastest growing with a CAGR of approximately 9.10%.
- By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Smart Antenna Market with approximately 56.90% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 9.40%.
- By Propulsion Type, the Internal Combustion Engine segment dominated the Automotive Smart Antenna Market with approximately 69.97% share in 2025, while the Battery-Electric Vehicle segment is the fastest growing with a CAGR of approximately 16.28%.
- By Application, the Telematics segment dominated the Automotive Smart Antenna Market with approximately 33.60% share in 2025, while the V2X Communication segment is the fastest growing with a CAGR of approximately 14.85%.
By Antenna Type, Shark-Fin dominates, and Embedded grows fastest
Shark fin antenna modules constitute the majority of the antennas used in the Automotive Smart Antenna Market due to the characteristic features where cellular, GNSS, and broadcast functions are incorporated within an aerodynamic enclosure which makes the antenna assembly easier compared to individual installation of several antennas. The market enjoys wide OEM standardization since most of the car manufacturers have standardized on shark fin antennas as the connectivity module.
Embedded antennas are emerging rapidly as European automakers pursue lower drag coefficients and reduced wiring harness weight by integrating antenna elements directly into bumpers, spoilers, and mirrors rather than mounting a separate rooftop module. As OEMs prioritize tool-agnostic, configurable designs, this segment focuses strongly on platforms that let manufacturers mix multiple radiating elements within a single engineering framework, reducing development overhead across vehicle trims.
By Connectivity Type, Cellular dominates, and GPS/GNSS grows fastest
Cellular connectivity remains the dominant connectivity-type segment, characterized by its foundational role in telematics, emergency call systems, and over-the-air software update delivery, functions that have become standard across nearly every new vehicle equipped with a connected services subscription.
The GPS/GNSS category is growing to become one of the fastest-growing categories of connectivity technologies because of the growing need for precise positioning, which is required in the advanced driver-assistance systems and autonomous driving capabilities, which require precise positioning in centimeters. The growth of this category is mainly attributed to the need for navigation reliability in dense urban areas.
By Vehicle Type, Passenger Vehicles dominate, and Commercial Vehicles grow fastest
Passenger vehicles remain the dominant vehicle-type segment, characterized by significantly higher production volumes and consumers' growing expectation that their vehicles seamlessly integrate with connected lifestyles, offering uninterrupted access to streaming, navigation, and interactive infotainment content during transit.
Commercial vehicles are emerging as the fastest-growing vehicle-type segment, driven by fleet operators adopting telematics-based tracking, driver safety monitoring, and V2X-enabled collision avoidance systems to reduce operating risk and improve logistics efficiency. As fleet managers prioritize real-time vehicle visibility, this segment focuses strongly on ruggedized antenna designs capable of withstanding the more demanding duty cycles commercial operation requires.
By Propulsion Type, Internal Combustion Engine dominates, and Battery-Electric Vehicle grows fastest
Internal combustion engine vehicles remain the dominant propulsion-type segment, characterized by their continued high share of global vehicle production despite accelerating electrification, sustaining substantial antenna demand across a vehicle category that remains the volume backbone of most automakers' current model lineups.
Battery-electric vehicles are emerging as the fastest-growing propulsion-type segment, driven by tightening emissions rules and declining battery costs that continue to expand BEV production volumes. As EV manufacturers prioritize signal integrity, this segment focuses strongly on advanced electromagnetic interference mitigation techniques that address the distinct noise environment created by high-voltage battery and inverter systems located near antenna installations.
By Application, Telematics dominates, and V2X Communication grows fastest
Telematics remains the dominant application segment, characterized by its established role in vehicle tracking, remote diagnostics, emergency call systems, and usage-based insurance programs that have driven sustained antenna demand across both passenger and commercial vehicle fleets for more than a decade.
V2X Communication is emerging rapidly as European mandates for vehicle-to-everything connectivity and expanding intelligent transportation infrastructure investment drive automaker adoption of V2X-capable antenna modules. As regulators and automakers prioritize collision avoidance and traffic efficiency, this segment focuses strongly on low-latency communication antennas capable of exchanging safety-critical data with infrastructure and surrounding vehicles in real time.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.90 |
|
Europe |
Germany |
30.85 |
|
Asia Pacific |
China |
43.60 |
|
Middle East & Africa |
Saudi Arabia |
38.40 |
|
Latin America |
Brazil |
46.75 |
North America Automotive Smart Antenna Market Insights
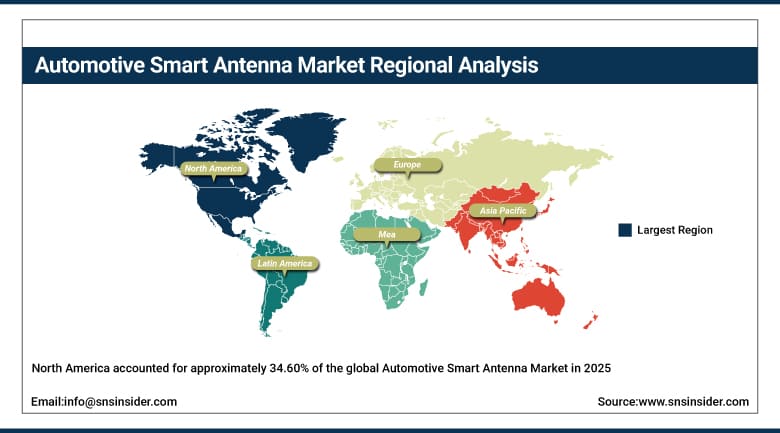
North America accounted for approximately 34.60% of the global Automotive Smart Antenna Market in 2025, remaining the largest regional market on the strength of strong OEM adoption of connected vehicle technologies and robust 5G infrastructure rollouts by national carriers. The United States dominates regional demand, supported by extensive engineering and manufacturing operations maintained by Continental, TE Connectivity, and Texas Instruments.
Sustained consumer demand for advanced infotainment, navigation, and driver-assistance features across mid- and premium-segment vehicles continues to reinforce regional demand. Canada contributes additional regional demand through its own automotive manufacturing sector, which is closely integrated with U.S. vehicle production supply chains.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Smart Antenna Market Insights
Asia Pacific is projected to expand at a CAGR of approximately 9.85% from 2026 to 2035, the fastest of any region, driven by a high concentration of antenna and vehicle manufacturers alongside rapidly increasing vehicle production volumes across China, Japan, and India. China's expanding domestic vehicle production, including rising sales of SUVs and premium vehicles equipped with advanced connectivity features, is generating substantial regional demand for smart antenna modules.
Japan enjoys supremacy in terms of the development of antenna technologies, hosting companies like Harada Industries among others which are still introducing new generation multi-band antennas. The growth in automobile production in India and an increased demand for connectivity features in cars is making substantial additions to the above-average growth rate in the region.
Europe Automotive Smart Antenna Market Insights
Europe represents a significant Automotive Smart Antenna Market, fueled by the mandatory regulations concerning the connectivity of everything to vehicles as well as a good number of premium automobile makers that have made the early adoption of sophisticated multiband antenna systems. The country with high demand for automotive smart antennas is Germany due to the presence of many premium car makers like Continental and Hella.
France and the United Kingdom contribute meaningful additional regional demand through their own automotive manufacturing bases, while continued European emphasis on reducing vehicle drag coefficients is reinforcing demand for embedded antenna designs that integrate into body panels rather than protruding rooftop modules.
MEA & Latin America Automotive Smart Antenna Market Insights
The Middle East & Africa Automotive Smart Antenna Market is expanding rapidly, with Saudi Arabia's NEOM development ordering thousands of autonomous vehicles requiring precision GNSS antenna systems, and the United Arab Emirates' target for a substantial share of autonomous travel by 2030 driving multi-band antenna demand in desert regions with sparse terrestrial network coverage.
Latin America is led by Brazil, where the national telecommunications regulator's clearance of C-V2X spectrum has seeded early connected-vehicle pilot programs in major metropolitan areas. Mexico contributes additional regional demand through its growing role as a nearshore vehicle manufacturing hub serving North American automotive supply chains.
Market Dynamics
Growth Drivers: 5G Deployment and Connected Vehicle Adoption
The deployment of 5G technology and future deployment of 6G across the world will continue to be the major growth factor for the Automotive Smart Antenna Market as automotive manufacturers strive to install antenna systems in their cars that can offer improved speed and reduced latency to support over-the-air applications.
Rising consumer expectation for seamless connected-lifestyle integration is reinforcing this driver, as vehicle buyers increasingly prioritize infotainment streaming, real-time navigation, and interactive digital services that depend on reliable, multi-band antenna performance. This consumer-driven demand is compounding the technology-driven upgrade cycle associated with successive generations of cellular network standards.
Restraints: Signal Interference and Cybersecurity Compliance Costs
Interference from metal vehicle body components and other electronic systems continues to reduce antenna reception quality, creating engineering challenges that require careful antenna placement and shielding design, particularly as vehicles add an increasing number of individual antenna elements within limited available surface area.
Increased security compliance costs in light of regulation like UNECE R-155, which relates to the management of cybersecurity in connected cars, increases the engineering cost for antenna suppliers and communication module manufacturers. These costs tend to be more challenging for small suppliers who do not have a regulatory affairs department like diversified Tier 1 suppliers.
Opportunities: Embedded Antenna Integration and Autonomous Vehicle GNSS Demand
Continued development of embedded antenna designs that integrate into bumpers, spoilers, and mirrors presents a significant opportunity for suppliers to capture premium pricing from European automakers prioritizing reduced drag coefficients and lighter wiring harnesses, even as embedded modules currently command a meaningful cost premium over traditional shark-fin designs.
Expanding autonomous vehicle deployment, including large-scale orders for precision GNSS-equipped vehicles in Gulf state smart-city developments, presents a further opportunity for suppliers offering high-precision, multi-constellation antenna systems. Suppliers successfully commercializing ruggedized, high-accuracy GNSS antennas are positioned to capture premium pricing from both passenger autonomous vehicle programs and off-highway applications such as mining and agricultural machinery.
Recent Developments:
- 2026: Taoglas launched an AI-driven Antenna Product Recommendation Engine, designed to help engineers identify suitable antennas and RF components using automated recommendations based on its antenna-design expertise.
- 2026: Continental completed the separation of its former automotive business into AUMOVIO, while focusing the remaining Continental Group on tires and ContiTech activities. This restructuring changes the corporate positioning of Continental's automotive connectivity and electronics activities.
- 2026: DENSO announced its expanding 2026 product portfolio and continued development of vehicle electronic and sensing technologies. Its broader automotive electronics portfolio supports increasingly connected vehicle architectures, although the announcement is more general than a dedicated smart-antenna launch.
Automotive Smart Antenna Market Key Players are:
- Continental AG
- Denso Corporation
- TE Connectivity Ltd.
- Forvia SE
- Ficosa Internacional SA
- Harada Industry Co., Ltd.
- Laird Connectivity (Molex)
- Kathrein Automotive GmbH
- Hirschmann Car Communication GmbH
- Amphenol Corporation
- Rosenberger Hochfrequenztechnik GmbH & Co. KG
- Yokowo Co., Ltd.
- Molex, LLC
- Airgain, Inc.
- Taoglas Group Holdings Limited
- Harman International Industries, Inc.
- Texas Instruments Incorporated
- NXP Semiconductors N.V.
- Kyocera Corporation
- Calearo Antenne S.p.A.
Automotive Smart Antenna Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.32 Billion |
| Market Size by 2035 | USD 14.81 Billion |
| CAGR | CAGR of 7.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Antenna Type (Shark-Fin, Embedded, Fixed-Mast, Glass Antenna, Others) • By Connectivity Type (Cellular, GPS/GNSS, Wi-Fi, Bluetooth, V2X) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles) • By Propulsion Type (Internal Combustion Engine, Battery-Electric Vehicle, Hybrid and Plug-in Hybrid (HEV/PHEV)) • By Application (Telematics, Infotainment, Navigation, Remote Diagnostics & eCall, V2X Communication) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Continental AG, Denso Corporation, TE Connectivity Ltd., Forvia SE, Ficosa Internacional SA, Harada Industry Co., Ltd., Laird Connectivity (Molex), Kathrein Automotive GmbH, Hirschmann Car Communication GmbH, Amphenol Corporation, Rosenberger Hochfrequenztechnik GmbH & Co. KG, Yokowo Co., Ltd., Molex, LLC, Airgain, Inc., Taoglas Group Holdings Limited, Harman International Industries, Inc., Texas Instruments Incorporated, NXP Semiconductors N.V., Kyocera Corporation, Calearo Antenne S.p.A. |
Frequently Asked Questions
Key players in the Automotive Smart Antenna Market include Continental AG, Denso Corporation, TE Connectivity Ltd., Forvia SE, and Ficosa Internacional SA, among others.
Key opportunities lie in embedded antenna designs integrated into body panels for reduced drag, and in high-precision, multi-constellation GNSS antennas serving expanding autonomous vehicle deployments.
The continued global rollout of 5G and forthcoming 6G networks, combined with rising consumer demand for connected vehicle services, is the major growth factor.
By Antenna Type, the Shark-Fin segment dominated the Automotive Smart Antenna Market with approximately 58.79% share in 2025.
