
Balloon Valvuloplasty Devices Market Report Scope & Overview:
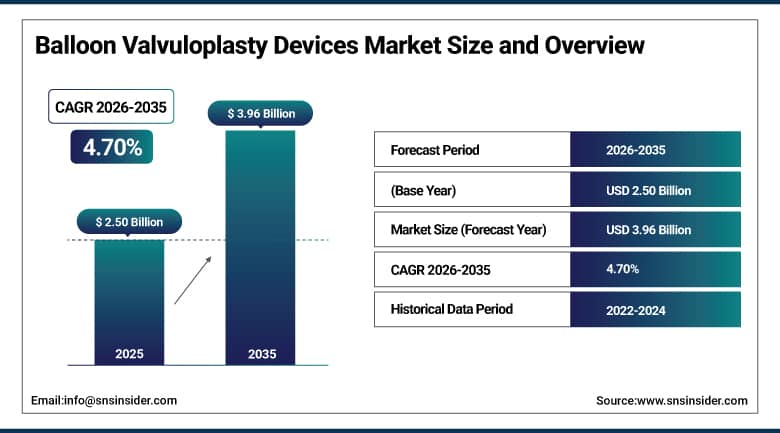
The Balloon Valvuloplasty Devices Market was valued at USD 2.50 Billion in 2025 and is expected to reach USD 3.96 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
Balloon valvuloplasty devices constitute an established category within interventional cardiology, using catheter-mounted balloons to widen narrowed heart valves and restore blood flow without replacing the native valve. A growing elderly population, a rising burden of aortic and mitral valve stenosis, and the preference for minimally invasive, catheter-based procedures continue to expand the patient base treated with these devices. Hospitals, cardiac catheterization laboratories, and ambulatory surgical centers rely on them as stand-alone therapy, as a bridge to transcatheter valve replacement, and as a palliative option for frail patients. Sustained growth is being shaped by higher-pressure balloon designs, improved procedural access techniques, and broader structural heart adoption, reinforcing this market's position as a durable segment of the wider cardiovascular device industry.
On March 11, 2025, Medinotec received U.S. FDA 510(k) clearance for its OutFlo Aortic Valve Dilation Balloon Catheter, a non-occlusive perfusion balloon designed for dilation of the aortic valve while maintaining blood flow. The company reported that first commercial sales are expected during the first quarter of its fiscal 2027.
To Get More Information On Balloon Valvuloplasty Devices Market - Request Free Sample Report
Balloon Valvuloplasty Devices Market Trends:
-
Growing development of ultra-high-pressure balloon catheters designed for heavily calcified valve anatomy.
-
Rising use of balloon aortic valvuloplasty as a bridge to transcatheter aortic valve replacement in unstable patients.
-
Expanding clinical evidence on alternative access routes, including transradial valvuloplasty.
-
Increasing adoption of non-occlusive perfusion balloons that maintain cardiac output during dilation.
-
Rising development of pediatric-specific balloon catheters for congenital valve conditions.
-
Growing structural heart investment across China and other emerging markets.
U.S. Balloon Valvuloplasty Devices Market Overview:
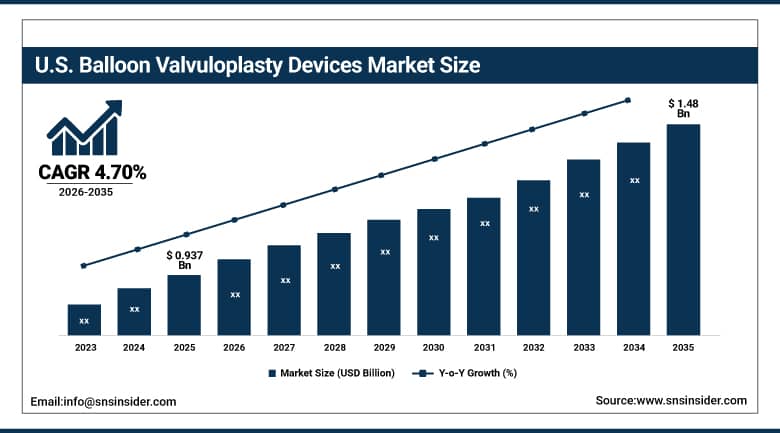
The U.S. Balloon Valvuloplasty Devices Market was valued at USD 0.937 Billion in 2025 and is expected to reach USD 1.48 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
The U.S. Balloon Valvuloplasty Devices Market is growing steadily, supported by a large and ageing population with a high prevalence of aortic stenosis and by the country's extensive network of structural heart programs. Balloon valvuloplasty remains an important option for patients who are unstable, frail, or awaiting transcatheter or surgical valve replacement, which sustains routine procedural demand across hospitals and catheterization laboratories. Manufacturers continue to introduce higher-pressure and more precisely controlled balloon designs, and FDA clearances for new catheters are broadening physician choice. Established reimbursement, strong clinical training, and rapid uptake of minimally invasive techniques further support market expansion, positioning the U.S. as the largest single contributor to regional revenue through the forecast period and keeping procedure volumes resilient even as transcatheter valve replacement expands.
On May 11, 2026, Flagstaff, Arizona-based Corvention announced that it had received FDA 510(k) clearance for its KardiaPSI Balloon Catheter, an ultra-high-pressure device for balloon aortic valvuloplasty. The catheter combines a 24-atmosphere rating with a short 2.5 cm balloon, in diameters from 19 to 29 mm.
Balloon Valvuloplasty Devices Market Segment Analysis:
-
By Application, the Aortic Valve Stenosis segment dominated the market with a 58.40% share in 2025, while the Pulmonary Valve Stenosis segment is the fastest growing with a CAGR of 5.70% during 2026-2035.
-
By Product Type, the Balloon Catheters segment dominated the market with a 52.40% share in 2025, while the Cutting Balloon Devices segment is the fastest growing with a CAGR of 6.30% during 2026-2035.
-
By Balloon Type, the Semi-Compliant segment dominated the market with a 54.60% share in 2025, while the Non-Compliant segment is the fastest growing with a CAGR of 5.60% during 2026-2035.
-
By End Use, the Hospitals segment dominated the market with a 56.40% share in 2025, while the Cardiac Catheterization Labs segment is the fastest growing with a CAGR of 5.90% during 2026-2035.
By Application, Aortic Valve Stenosis Dominates the Market and Pulmonary Valve Stenosis Grows Fastest
Aortic Valve Stenosis dominated the market in 2025, a position built on the high prevalence of calcific aortic stenosis among older adults and the continuing role of balloon aortic valvuloplasty as a temporizing, stratifying, or palliative procedure. Clinicians favour valvuloplasty precisely because it offers rapid relief in unstable patients who cannot yet undergo valve replacement, and because it is widely used to pre-dilate valves during transcatheter procedures, a combination that keeps aortic applications the largest category across the broader market, even as other valve indications continue to expand around it.
Pulmonary Valve Stenosis is projected to be the fastest-growing application over the forecast period. Balloon dilation is the established first-line treatment for congenital pulmonary stenosis in infants and children, and improved neonatal screening and access to pediatric cardiac care in emerging regions are widening the treated population. Continued development of pediatric-sized balloon catheters also supports adoption, allowing pulmonary valve applications to close the gap with aortic indications in overall market demand.
By Product Type, Balloon Catheters Dominates the Market and Cutting Balloon Devices Grows Fastest
Balloon Catheters dominated the market in 2025. The catheter is the core consumable in every valvuloplasty procedure, and each case requires one or more balloons matched to the valve annulus, which makes catheters the largest revenue contributor by a clear margin. Steady procedure volumes, the need for multiple sizes in inventory, and the frequency of replacement keep this product category ahead of inflation devices, guidewires, and accessories across the broader market.
Cutting Balloon Devices are expected to be the fastest-growing product type over the forecast period. These specialized balloons use small blades or scoring elements to fracture resistant tissue, and they are attracting interest for heavily calcified and fibrotic lesions that conventional balloons struggle to open. As operators encounter more complex anatomy in older patients, and as manufacturers refine scoring designs, cutting balloon devices continue to close the gap with standard catheters in overall market demand.
By Balloon Type, Semi-Compliant Dominates the Market and Non-Compliant Grows Fastest
Semi-Compliant balloons dominated the market in 2025. Their combination of predictable sizing with a degree of forgiving expansion makes them a familiar and versatile choice across aortic, pulmonary, and mitral applications, and they are widely stocked in catheterization laboratories. Operators value the balance they offer between safety margin and effective dilation, which continues to sustain semi-compliant designs as the largest balloon type category across the broader market.
Non-Compliant balloons are projected to expand fastest over the forecast period. Their ability to hold a fixed diameter under high inflation pressure delivers focal force exactly where it is needed, which matters for calcified valves and for pre-dilation before transcatheter implants. As new high-pressure catheters reach the market and clinicians seek greater procedural precision, non-compliant designs continue to close the gap with semi-compliant balloons in overall market demand.
By End Use, Hospitals Dominates the Market and Cardiac Catheterization Labs Grows Fastest
Hospitals dominated the market in 2025. Valvuloplasty is typically performed in settings with cardiac surgery backup, anaesthesia support, and imaging, particularly for high-risk elderly patients, and hospitals house the structural heart teams that manage these cases. Their concentration of skilled interventionalists and purchasing power continues to sustain hospitals as the largest end use category across the broader market.
Cardiac Catheterization Labs are expected to be the fastest-growing end use over the forecast period. Dedicated cath labs, including those in stand-alone cardiac centers, are handling a growing share of structural procedures as techniques become less invasive and as access routes such as transradial approaches gain acceptance. Rising investment in specialized cardiac facilities continues to close the gap between cath labs and hospital-based settings in overall market demand.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
91.20% |
|
Europe |
Germany |
27.80% |
|
Asia Pacific |
China |
33.60% |
|
Latin America |
Brazil |
49.20% |
|
Middle East & Africa |
South Africa |
26.60% |
North America Balloon Valvuloplasty Devices Market Insights
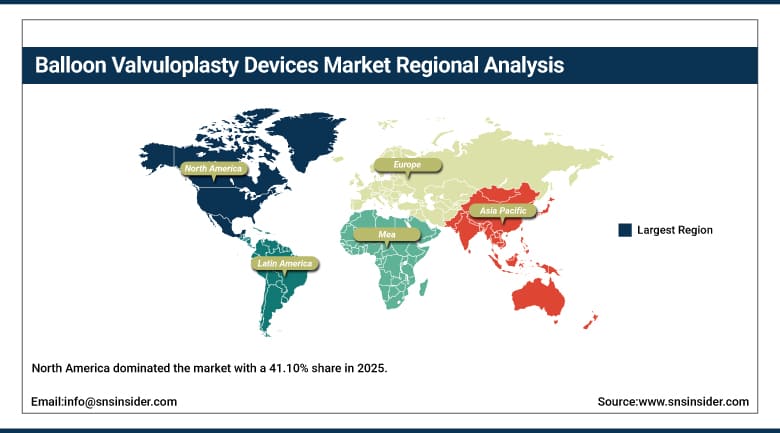
North America dominated the market with a 41.10% share in 2025. A high prevalence of cardiovascular and valvular heart disease, advanced healthcare infrastructure, frequent new product launches, and timely regulatory approvals continue to anchor this leadership position. The United States shapes regional demand through its large structural heart programs and concentration of leading device manufacturers and start-ups developing high-pressure balloon technology.
Canada contributes additional regional volume through provincial cardiac care programs and growing transcatheter valve activity. Continued innovation in balloon design and expanding clinical evidence are expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building structural heart capacity from a smaller base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Balloon Valvuloplasty Devices Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 6.60% during 2026-2035, supported by rapidly ageing populations, expanding cardiac care infrastructure, and rising adoption of catheter-based treatments. China is becoming an important growth area as its structural heart intervention field develops quickly and local manufacturers introduce valvuloplasty and transcatheter valve products.
Japan contributes depth through its advanced cardiac care system and one of the world's oldest populations, while India and South Korea add growth as investment in cardiovascular facilities rises. Together these markets position the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Balloon Valvuloplasty Devices Market Insights
Europe holds a meaningful share of the global market, underpinned by an ageing population, well-developed cardiology services, and a strong base of valvuloplasty balloon manufacturers. Germany anchors regional demand through high procedure volumes and a dense network of heart centers, while European companies supply non-compliant and semi-compliant balloons to hospitals worldwide.
France, Italy, the United Kingdom, and Spain contribute consistent demand as national health systems extend transcatheter therapies and use valvuloplasty as a bridging procedure. Steady demographic pressure is expected to support stable, mid-single-digit growth across the region through the forecast period.
MEA & Latin America Balloon Valvuloplasty Devices Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand as private and public hospitals expand interventional cardiology services. Mexico and Argentina add incremental volume, though budget constraints and uneven access to specialized centers continue to limit wider adoption.
The Middle East & Africa region is growing from a small base, with demand concentrated in Gulf Cooperation Council markets, Turkey, Israel, and Egypt, where investment in cardiac centers is rising. South Africa anchors demand on the African continent, supported by its comparatively developed private healthcare sector, though rheumatic valve disease in wider Africa remains under-served.
Market Dynamics:
Growth Drivers: Valvular Heart Disease Burden and Minimally Invasive Preference
Growing prevalence of valvular heart disease acts as the main growth factor, supported by the process of ageing in populations, which leads to higher instances of calcific aortic stenosis and degenerative mitral disease. With an increase in the number of elderly patients requiring treatment for symptomatic stenosis, there is increased need for solutions that can repair valves quickly with low risks and balloon dilation remains relevant along with valve replacement.
Minimally invasive and catheter-based procedures being preferred constitute the second main growth factor. There are benefits of shortening recovery time, minimizing risks, and treating patients who cannot undergo surgery, and this procedure is often performed in combination with transcatheter valve procedures. Additional product launch, regulatory approvals, and infrastructure development in emerging markets are further growth factors.
Restraints: Procedure Durability and Cost Barriers
Limited durability of the clinical benefit remains a genuine restraint on market growth, as restenosis of the valve after balloon dilation can occur within months, which positions valvuloplasty mainly as a bridge or palliative option rather than a definitive therapy. The growth of transcatheter valve replacement, which offers longer-lasting outcomes, can therefore limit the use of stand-alone valvuloplasty in eligible patients.
Cost and skill barriers present further restraints. Smaller centers in developing regions often lack the financial resources to buy high-end balloon systems, and the procedure requires experienced structural heart operators and imaging support. Shortages of trained specialists and high procedure costs reduce accessibility in lower-income regions, slowing market penetration.
Opportunities: High-Pressure Designs and Pediatric Device Development
The development of high-pressure, precisely controlled balloon catheters offers a substantial opportunity, as calcified valve anatomy remains a persistent challenge for conventional balloons. Companies that deliver reliable force in a short, stable balloon profile can win share among operators seeking predictability, and can extend their offerings for pre-dilation in transcatheter procedures.
The development of pediatric-specific balloon valvuloplasty devices presents a further avenue for growth. Children with congenital valve conditions need appropriately sized, low-profile catheters, and improved screening is bringing more patients into treatment in emerging markets. Distribution partnerships and regional manufacturing can further widen access and open recurring revenue for suppliers with established structural heart relationships.
Recent Developments:
-
2021, Keystone Heart announced an exclusive agreement to distribute InterValve Medical's balloon aortic valvuloplasty portfolio, including the V8 and TAV8 catheters, in the United States.
-
2022, Boston Scientific completed its acquisition of Baylis Medical Company, adding transseptal access solutions, guidewires, sheaths, and dilators used in catheter-based left-heart procedures.
-
2023, Abbott received FDA approval for its Navitor transcatheter aortic valve system for patients with severe aortic stenosis at high or extreme surgical risk.
Balloon Valvuloplasty Devices Market Key Players:
-
Abbott Laboratories
-
Boston Scientific Corporation
-
Medtronic plc
-
B. Braun Melsungen AG
-
Edwards Lifesciences Corporation
-
Cordis (Cardinal Health)
-
Teleflex Incorporated
-
Becton, Dickinson and Company
-
Terumo Corporation
-
Cook Medical LLC
-
Merit Medical Systems, Inc.
-
AngioDynamics, Inc.
-
NuMED, Inc.
-
Osypka Medical
-
Balton Sp. z o.o.
-
Biotronik SE & Co. KG
-
Meril Life Sciences Pvt. Ltd.
-
InterValve Medical (Venus Medtech)
-
Corvention, Inc.
-
Medinotec Inc.
Balloon Valvuloplasty Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.50 Billion |
| Market Size by 2035 | USD 3.96 Billion |
| CAGR | CAGR of 4.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Application (Aortic Valve Stenosis, Pulmonary Valve Stenosis, Mitral Valve Stenosis, and Others) • by Product Type (Balloon Catheters, Cutting Balloon Devices, Inflation Devices, and Accessories) • by Balloon Type (Semi-Compliant and Non-Compliant) • by End Use (Hospitals, Cardiac Catheterization Labs, and Ambulatory Surgical Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott Laboratories, Boston Scientific Corporation, Medtronic plc, B. Braun Melsungen AG, Edwards Lifesciences Corporation, Cordis (Cardinal Health), Teleflex Incorporated, Becton, Dickinson and Company, Terumo Corporation, Cook Medical LLC, Merit Medical Systems, Inc., AngioDynamics, Inc., NuMED, Inc., Osypka Medical, Balton Sp. z o.o., Biotronik SE & Co. KG, Meril Life Sciences Pvt. Ltd., InterValve Medical (Venus Medtech), Corvention, Inc., Medinotec Inc. |
Frequently Asked Questions
Key players include Abbott Laboratories, Boston Scientific, Medtronic, B. Braun Melsungen, Edwards Lifesciences, Cordis, Teleflex, Becton Dickinson, Terumo, and Cook Medical, among others.
The development of high-pressure, precisely controlled balloon catheters and pediatric-specific valvuloplasty devices represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by the rising prevalence of valvular heart disease in an ageing population, combined with a strong preference for minimally invasive, catheter-based procedures.
By Application, Aortic Valve Stenosis dominated the market with a 58.40% share in 2025, reflecting the high prevalence of calcific aortic stenosis among older adults.
North America dominated the market with a 41.10% share in 2025, supported by a high prevalence of valvular disease, advanced healthcare infrastructure, and frequent product approvals, led by the United States.
