
Cancer Diagnostics Market Report Scope & Overview:
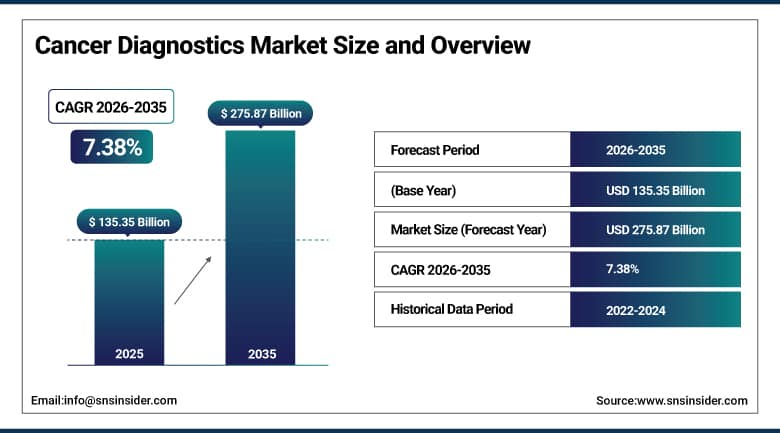
The Cancer Diagnostics Market was valued at USD 135.35 Billion in 2025 and is expected to reach USD 275.87 Billion by 2035, growing at a CAGR of 7.38% from 2026-2035.
The Cancer Diagnostics Market is expanding as health systems detect more cancers earlier and match patients to targeted therapies with molecular testing. Rising cancer incidence in ageing populations, wider screening programs and the growth of precision oncology all increase test volumes. Consumables such as assay kits and reagents account for the largest share of spending, because every test run requires them. In vitro diagnostics (IVD), next-generation sequencing (NGS), liquid biopsy and artificial intelligence-assisted imaging are widening what clinicians can detect from a blood draw or a tissue sample. Companion diagnostics that accompany new cancer drugs add steady demand. North America leads the market, while Asia Pacific is expected to grow at the fastest pace as screening coverage expands.
⮞In June 2026, the NHS-Galleri trial in England, which enrolled more than 142,000 volunteers aged 50 to 77, reported that its primary endpoint of fewer late-stage cancers was not met. A prespecified secondary analysis showed a reduction of more than 20% in stage 4 cancers.
To Get More Information On Cancer Diagnostics Market - Request Free Sample Report
Cancer Diagnostics Market Trends
-
Adoption of liquid biopsy and circulating tumor DNA tests for screening, monitoring and minimal residual disease
-
Expansion of companion diagnostics approved alongside targeted cancer therapies
-
Use of artificial intelligence in digital pathology and cancer imaging interpretation
-
Launch of organized population screening programs for lung and colorectal cancer
-
Regulatory reform of laboratory-developed tests and in vitro diagnostic rules
U.S. Cancer Diagnostics Market Outlook
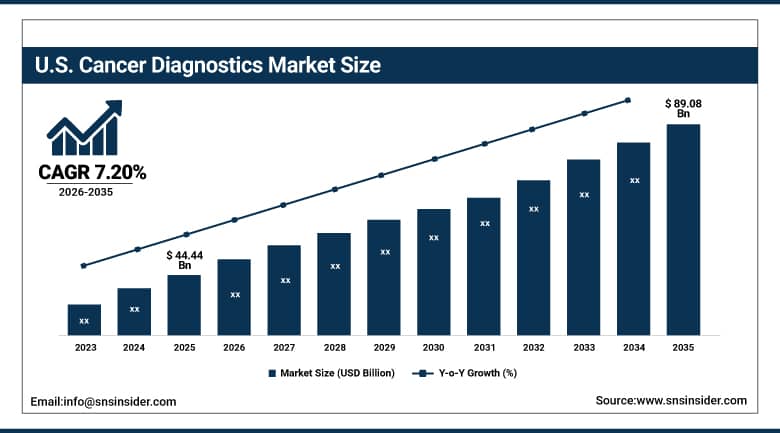
The U.S. Cancer Diagnostics Market was valued at USD 44.44 Billion in 2025 and is expected to reach USD 89.08 Billion by 2035, growing at a CAGR of 7.20% from 2026-2035.
The U.S. Cancer Diagnostics Market is the largest national market for cancer testing, supported by high screening rates, broad insurance coverage and rapid uptake of molecular assays. Hospital laboratories, reference laboratories and cancer centers run a large volume of immunohistochemistry, sequencing and imaging tests each year. The Food and Drug Administration (FDA) approves companion diagnostics alongside many oncology drugs, which links drug launches to test demand. Medicare payment policy for advanced diagnostic laboratory tests supports new blood-based screening products. Debate over the oversight of laboratory-developed tests shapes how new assays reach patients. Demand is expected to rise as multi-cancer detection, minimal residual disease testing and digital pathology move from trials into routine care.
⮞For instance, on September 23, 2026, the FDA Molecular and Clinical Genetics Panel voted 7 to 2, with one abstention, that the benefits of the Galleri multi-cancer blood test from GRAIL outweigh its risks. The vote came before any decision on the product.
Cancer Diagnostics Market Segment Analysis
-
By Product, the Consumables segment dominated the Cancer Diagnostics Market with approximately 61.43% share in 2025, and is also the fastest growing with a CAGR of approximately 7.73%.
-
By Technology, the In Vitro Diagnostics segment dominated the Cancer Diagnostics Market with approximately 51.60% share in 2025, while the Imaging segment is the fastest growing with a CAGR of approximately 8.74%.
-
By Cancer Type, the Breast Cancer segment dominated the Cancer Diagnostics Market with approximately 17.70% share in 2025, while the Lung Cancer segment is the fastest growing with a CAGR of approximately 9.63%.
-
By End User, the Hospitals and Clinics segment dominated the Cancer Diagnostics Market with approximately 45.77% share in 2025, while the Diagnostic Laboratories segment is the fastest growing with a CAGR of approximately 8.48%.
By Product, Consumables Dominates the Cancer Diagnostics Market and Is Also the Fastest Growing
Consumables hold the leading position because every cancer test consumes assay kits, reagents, probes, antibodies, stains and sample preparation materials. Laboratories buy these items continuously, and each new test panel adds a recurring stream of purchases that outlasts the sale of the analyzer itself. Instrument makers support this pattern by tying platforms to proprietary reagents, which keeps utilization high across the installed base. Rising test volumes from screening programs and treatment selection therefore flow first into kit and reagent orders. Large laboratory networks also negotiate multi-year reagent contracts, which stabilizes revenue for suppliers and encourages them to widen test menus.
Consumables are also the fastest growing product group as new assays reach the clinic faster than new instruments. Companion diagnostic kits, liquid biopsy panels and immunohistochemistry reagents are launched alongside targeted drugs, and sequencing-based tests require high-cost flow cells and library preparation kits. Decentralized testing in regional laboratories raises kit demand further. Software and services form a smaller product group, though interpretation platforms and digital pathology tools are gaining ground as laboratories seek help with data analysis and reporting. Manufacturers are also designing closed cartridges and automated sample preparation, which cut hands-on time for laboratories short of skilled staff.
⮞In July 2025, the FDA approved the Oncomine Dx Express Test from Thermo Fisher Scientific, a next-generation sequencing assay used as a companion diagnostic for ZEGFROVY and for tumor profiling. The approval shows how assay kits follow new drug approvals.
By Technology, In Vitro Diagnostics Dominates the Cancer Diagnostics Market and Imaging Grows Fastest
In vitro diagnostics lead the technology mix because most cancer decisions rely on a laboratory test, whether it is a tumor marker in blood, a pathology stain on tissue or a sequencing panel on a biopsy. This group includes immunoassays, polymerase chain reaction, immunohistochemistry, in situ hybridization and sequencing, and it spans screening, diagnosis, treatment selection and monitoring. Laboratories already have the staff, workflows and reimbursement codes for these tests, which supports steady volume. Companion diagnostics tied to cancer drugs further anchor the segment in routine oncology practice.
Imaging is expected to grow fastest as screening programs, artificial intelligence and new contrast and tracer agents improve how early tumors are found. Low-dose computed tomography for lung screening, three-dimensional mammography, contrast-enhanced breast imaging and positron emission tomography are all gaining use. Software that flags suspicious findings helps radiologists manage rising caseloads, and national screening programs add procedure volume. Biopsy remains the confirmatory step, with liquid biopsy extending it to patients for whom tissue is hard to obtain. Automated image analysis and structured reporting are also reducing the time between suspicious findings and tissue confirmation.
⮞In August 2026, the FDA cleared expanded use of the PATHWAY HER2 (4B5) test and the VENTANA HER2 Dual ISH test from Roche as companion diagnostics for HER2-positive metastatic gastroesophageal adenocarcinoma. The clearance supports pathology-based treatment selection.
By Cancer Type, Breast Cancer Dominates the Cancer Diagnostics Market and Lung Cancer Grows Fastest
Breast cancer accounts for the largest testing volume because it is among the most common cancers worldwide and is the subject of long-established screening programs. Mammography, ultrasound, magnetic resonance imaging, biopsy and receptor testing for hormone and HER2 status form a complete diagnostic pathway. Genomic assays that guide chemotherapy decisions and hereditary risk tests add further volume. Awareness campaigns and insurance coverage in high-income countries keep women entering screening on a regular schedule. Genetic risk testing for BRCA variants and multigene panels also feeds additional follow-up imaging and surveillance for high-risk women. Smoking cessation programs often accompany screening and encourage participation among high-risk groups.
Lung cancer is the fastest growing type as low-dose computed tomography screening spreads and molecular testing becomes standard for non-small cell disease. Guidelines call for testing of EGFR, ALK and other biomarkers before targeted therapy, which creates demand for panels and companion diagnostics. Government programs for high-risk smokers are opening in several countries, and blood-based tests are being studied as a way to reach people who do not attend imaging. Colorectal and prostate cancer remain large categories, supported by stool-based, blood-based and prostate-specific testing.
⮞For example, Australia's National Lung Cancer Screening Program started on July 1, 2025, offering free low-dose computed tomography scans to people aged 50 to 70 who smoke or have a smoking history. The program shows how public screening raises diagnostic volumes.
By End User, Hospitals and Clinics Dominates the Cancer Diagnostics Market and Diagnostic Laboratories Grows Fastest
Hospitals and clinics remain the leading end users because they diagnose and treat most cancer patients and operate pathology, radiology and oncology units in one setting. Tumor boards use imaging, biopsy and molecular results together to choose treatment, and hospitals hold the capital budgets for analyzers, scanners and digital pathology systems. Academic medical centers also run many of the trials that generate new biomarkers. Reimbursement for inpatient and outpatient diagnostics supports a steady flow of cases through hospital laboratories. Cancer centers also invest in integrated reporting, which brings imaging, pathology and genomic results into one record for the tumor board.
Diagnostic laboratories are growing fastest as specialized reference laboratories take on the complex molecular and genomic tests that smaller hospitals cannot run efficiently. Sequencing, minimal residual disease monitoring and multi-gene panels need scale, expert interpretation and quality systems that favor centralized providers. Hospitals increasingly send out these tests, and direct-to-clinician ordering of blood-based assays is spreading. Regulatory decisions on laboratory-developed tests influence how quickly these laboratories can introduce new products. Large reference laboratories also benefit from outsourcing contracts with hospital systems, which increase their sample volumes and justify investment in higher-throughput sequencers and automation.
⮞In March 2025, the U.S. District Court for the Eastern District of Texas vacated the FDA's 2024 final rule on laboratory-developed tests, ruling that the agency lacks authority over them. The decision affects how laboratories bring new cancer assays to market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
85.27 |
|
Europe |
Germany |
23.94 |
|
Asia Pacific |
China |
39.46 |
|
Latin America |
Brazil |
44.18 |
|
Middle East & Africa |
Saudi Arabia |
27.63 |
North America Cancer Diagnostics Market Insights
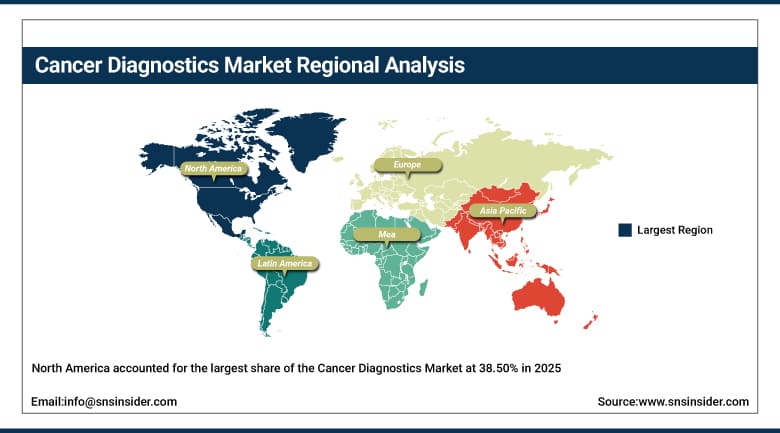
North America accounted for the largest share of the Cancer Diagnostics Market at 38.50% in 2025, led by the United States and supported by Canada. High screening participation, broad insurance coverage, a dense network of cancer centers and early adoption of molecular tests keep volumes high. Leading assay and instrument makers are based in the region, and companion diagnostics are often approved here first. Medicare coverage of blood-based colorectal screening has widened access to newer products. Large health systems also run integrated pathology and genomics services, which speeds treatment selection.
Canada is building organized screening programs across its provinces, with lung screening expanding steadily, while provincial health systems manage test funding through central review. Pathology laboratories in both countries are adopting digital slides and artificial intelligence tools to cope with workforce shortages. Debate over how laboratory-developed tests are overseen adds uncertainty for laboratories, but it has not slowed the arrival of new multi-gene and liquid biopsy products. Canadian guidelines are also being updated to cover more cancer types, and provinces are investing in laboratory networks that can process higher volumes of molecular tests close to patients.
⮞As of February 2026, 7 of Canada's 13 provinces and territories offered lung cancer screening programs. The count shows how organized screening is spreading at the provincial level.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Cancer Diagnostics Market Insights
Europe is a large and mature region led by Germany, the United Kingdom, France, Italy and Spain. National health systems fund organized breast, cervical and colorectal screening, and the European Union is encouraging member states to add lung and prostate programs. Germany and France host major assay and instrument makers, and regional laboratories handle a high volume of pathology and molecular tests. Public hospitals tend to centralize molecular testing in a small number of regional centers, which supports high utilization of sequencers and automated pathology systems across the region.
Regulation shapes the pace of change. The In Vitro Diagnostic Regulation raises documentation and notified-body requirements, and the European Commission has proposed ways to simplify it. Health technology assessment bodies scrutinize new tests before reimbursement, which slows adoption of multi-cancer tests. The United Kingdom runs some of the largest evaluations of blood-based screening, and Nordic countries are early adopters of digital pathology. Cross-border research networks and large academic trials also generate evidence that national agencies use when deciding on reimbursement, which influences the rollout of new assays across the region.
⮞The European Union opened a funding call to pilot and implement lung cancer screening programs on September 23, 2025, and closed it on January 6, 2026. The call supports member states in setting up organized programs.
Asia Pacific Cancer Diagnostics Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 8.58% during 2026-2035. China, Japan, India, South Korea and Australia lead demand, supported by large patient populations, expanding hospital capacity and government cancer control plans. China has approved a growing number of domestic and foreign companion diagnostics, while Japan and South Korea run established screening systems and adopt advanced imaging early. Hospital groups in Southeast Asia are also adding molecular pathology units to serve medical travelers, which raises demand for imported and locally made assay kits.
India is scaling population screening for oral, breast and cervical cancer through its public health system, and private laboratory chains are expanding molecular testing in large cities. Australia has launched a national lung screening program, and Singapore and Thailand are investing in genomic medicine. Uneven access outside major cities and price sensitivity remain obstacles, but local manufacturing of kits and instruments is lowering costs and improving supply. Digital pathology and teleradiology networks are also being built to connect smaller hospitals with expert centers, which helps close the specialist gap across the region.
⮞In February 2026, China's National Medical Products Administration approved the Promega OncoMate MSI Detection Kit as a companion diagnostic for KEYTRUDA in microsatellite instability-high solid tumors. The approval adds to the growing list of locally approved companion tests.
MEA & Latin America Cancer Diagnostics Market Insights
In Latin America, Brazil, Mexico, Argentina and Colombia lead demand, supported by public screening programs and a growing private laboratory sector. Brazil's national health system is moving toward organized screening for colorectal and cervical cancer, and Mexico's large private and social security networks buy molecular tests for treatment selection. Funding limits, long waiting times for biopsy results and uneven access outside large cities continue to restrain testing, but multinational suppliers are expanding local laboratory partnerships. Public-private partnerships are also bringing mobile mammography units to remote areas, and laboratories in Chile and Colombia are adopting sequencing for tumor profiling.
⮞On May 21, 2026, Brazil's Ministry of Health added the fecal immunochemical test to its national colorectal screening program for adults aged 50 to 75. The program is the first organized, population-based effort of its kind in the country.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead demand. Gulf governments are investing in genomics centers, national cancer plans and early detection programs, and private hospital groups buy advanced imaging and molecular platforms. In much of sub-Saharan Africa, late-stage presentation and limited pathology capacity remain major challenges, and donor-supported programs focus on cervical and breast cancer screening. Medical tourism hubs in the Gulf also draw investment in advanced imaging and molecular pathology, and South Africa hosts the region's most developed network of private pathology laboratories.
⮞On January 7, 2026, the UAE Minister of Health and Prevention told the Federal National Council that the country is moving toward nationwide mandatory early cancer screening linked to health insurance.
Market Dynamics
Growth Drivers: Rising Cancer Incidence, Screening Programs and Precision Oncology Drive Growth in the Cancer Diagnostics Market
The growing number of cancer cases is the base of demand. Ageing populations and lifestyle risk factors increase the number of people who need screening, diagnosis and monitoring, and early detection is now a stated priority of national cancer plans. Organized programs for breast, cervical, colorectal and lung cancer bring more people into testing, and each positive result leads to confirmatory imaging, biopsy and molecular profiling. Public and private payers are extending coverage to newer screening products. Falling costs and growing clinical evidence also encourage guideline bodies to recommend broader testing, which feeds demand for panels and monitoring assays.
Precision oncology adds a second layer of demand. Many new cancer drugs are approved with a companion diagnostic, so each launch creates a defined test market. Sequencing costs have fallen, which allows broad tumor profiling to become routine in advanced disease. Liquid biopsy lets clinicians follow treatment response from a blood sample, and artificial intelligence tools help pathologists and radiologists handle larger caseloads with more consistent results. Rising public awareness and patient advocacy also push more people toward screening appointments, which lifts demand for downstream tests.
⮞On March 11, 2025, the Centers for Medicare and Medicaid Services granted Advanced Diagnostic Laboratory Test status to the Shield blood test from Guardant Health for colorectal cancer screening, with Medicare payment effective April 1, 2025.
Restraints: Regulatory Complexity, Reimbursement Gaps and Workforce Shortages Restrain Growth in the Cancer Diagnostics Market
Regulation and reimbursement slow the introduction of new tests. Approval pathways differ across the United States, Europe and Asia, and manufacturers must produce clinical evidence that satisfies each regulator and payer. Coverage decisions for multi-cancer and minimal residual disease tests are often delayed until outcomes data are available, which leaves laboratories to absorb costs in the interim. Uncertainty over rules for laboratory-developed tests adds to planning difficulty. Reimbursement lists may also exclude newer tests for years, which discourages smaller laboratories from offering them to patients.
Capacity and cost also limit growth. Many regions lack enough pathologists, radiologists and genetic counselors, so samples wait longer and screening programs cannot always scale. Advanced sequencing and imaging equipment is expensive, and smaller hospitals in lower-income markets cannot always afford it. Concerns about overdiagnosis, false positives and data privacy also temper adoption of some screening products, and patients in rural areas may face travel barriers. Supply chain disruptions and price pressure from tenders also limit margins for manufacturers.
⮞On December 16, 2025, the European Commission published a proposal to simplify the medical device and in vitro diagnostic regulations, covering performance studies, in-house devices and notified-body involvement. The proposal reflects the compliance burden facing diagnostic makers.
Opportunities: Multi-Cancer Detection, Liquid Biopsy and Digital Pathology Create Opportunities in the Cancer Diagnostics Market
Blood-based detection offers a large opportunity because it could reach people who skip invasive or inconvenient screening. Multi-cancer early detection tests, minimal residual disease assays and tumor-informed monitoring are moving through trials and regulatory review, and payers are watching the evidence closely. Companies that secure clear regulatory status and reimbursement stand to build recurring testing volumes that extend well beyond today's single-cancer screens. Consolidation among diagnostic companies may also create large integrated players that can fund long clinical trials and fast global launches.
Digital pathology and artificial intelligence create further opportunities. Slide scanners, image analysis software and decision support tools allow laboratories to share cases remotely, reduce turnaround time and standardize biomarker scoring. Emerging markets are building cancer centers and screening programs, which opens space for affordable kits, point-of-care assays and locally manufactured instruments. Partnerships between diagnostic firms and drug developers also extend the reach of companion tests. Public screening mandates and insurance linkage in some countries could also expand the eligible population far beyond today's levels.
⮞On October 9, 2026, Natera announced that the FDA granted breakthrough device designation to its multi-cancer early detection blood test, based on data covering 12 cancer types. The assay remains investigational.
Recent Developments:
-
2026: Abbott completed its acquisition of Exact Sciences, adding the Cologuard, Cancerguard, Oncotype DX and Oncodetect tests to its portfolio. The transaction expands Abbott's presence in cancer screening and treatment-selection diagnostics.
-
2026: CareDx completed its acquisition of Naveris, the developer of the NavDx circulating tumor DNA test. The acquisition gives CareDx a presence in cancer monitoring alongside its transplant diagnostics.
-
2026: Agilent Technologies completed its acquisition of Biocare Medical, a supplier of immunohistochemistry and molecular pathology products used in cancer diagnostics. The purchase broadens Agilent's pathology portfolio for cancer laboratories.
-
2025: Bio-Rad Laboratories announced its QX700 series of droplet digital polymerase chain reaction platforms following its acquisition of Stilla Technologies. The launch widens its digital polymerase chain reaction offering for oncology research and testing.
Cancer Diagnostics Market Key Players are:
-
F. Hoffmann-La Roche Ltd
-
Abbott Laboratories (including Exact Sciences)
-
Thermo Fisher Scientific Inc.
-
Illumina, Inc.
-
QIAGEN N.V.
-
Hologic, Inc.
-
Siemens Healthineers AG
-
GE HealthCare Technologies Inc.
-
Guardant Health, Inc.
-
Natera, Inc.
-
GRAIL, Inc.
-
Myriad Genetics, Inc.
-
Agilent Technologies, Inc.
-
Bio-Rad Laboratories, Inc.
-
Danaher Corporation (Leica Biosystems)
-
Becton, Dickinson and Company
-
Sysmex Corporation
-
Koninklijke Philips N.V.
Cancer Diagnostics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 135.35 Billion |
| Market Size by 2035 | USD 275.87 Billion |
| CAGR | CAGR of 7.38% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Consumables, Instruments, and Software and Services) • By Technology (In Vitro Diagnostics, Imaging, Biopsy, and Others) • By Cancer Type (Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer, and Others) • By End User (Hospitals and Clinics, Diagnostic Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | F. Hoffmann-La Roche Ltd, Abbott Laboratories (including Exact Sciences), Thermo Fisher Scientific Inc., Illumina, Inc., QIAGEN N.V., Hologic, Inc., Siemens Healthineers AG, GE HealthCare Technologies Inc., Guardant Health, Inc., Natera, Inc., GRAIL, Inc., Myriad Genetics, Inc., Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Danaher Corporation (Leica Biosystems), Becton, Dickinson and Company, Sysmex Corporation, Koninklijke Philips N.V. |

Frequently Asked Questions
Key players include Roche, Abbott, Thermo Fisher Scientific, Illumina, QIAGEN, Hologic, Siemens Healthineers, GE HealthCare, Guardant Health, Natera, GRAIL, Myriad Genetics, Agilent Technologies, Bio-Rad Laboratories, Danaher, Becton Dickinson, Sysmex and Philips.
Key opportunities include multi-cancer early detection, liquid biopsy and minimal residual disease testing, digital pathology with artificial intelligence, and affordable testing for emerging markets building screening programs.
Rising cancer incidence, expanding screening programs and the spread of precision oncology with companion diagnostics are the main growth factors, supported by falling sequencing costs.
By Product, the Consumables segment dominated the market in 2025 with an estimated 61.43% share, supported by recurring purchases of assay kits and reagents.
North America dominated the market with a share of 38.50% in 2025, driven by high screening rates, broad coverage and early adoption of molecular tests.
