
Type 1 Diabetes Market Report Scope & Overview:
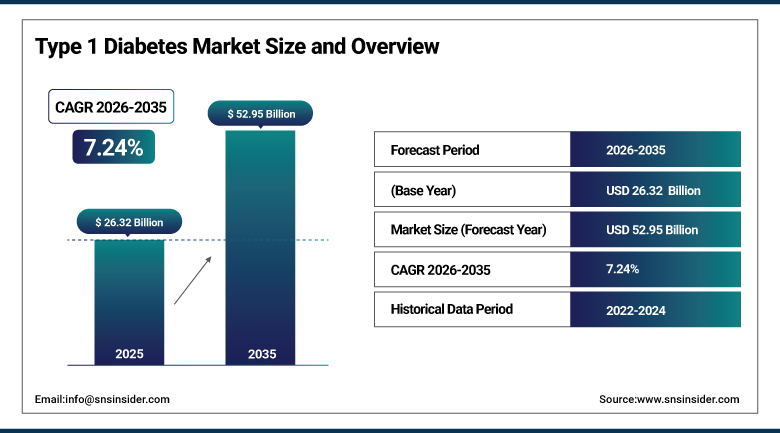
The Type 1 Diabetes Market was valued at USD 26.32 Billion in 2025 and is expected to reach USD 52.95 Billion by 2035, growing at a CAGR of 7.24% from 2026-2035.
The Type 1 Diabetes Market is expanding as care moves from basic insulin injection toward connected, automated treatment. Insulin remains the base of therapy, since people with the condition cannot make it. Continuous glucose monitors and automated insulin delivery systems now link sensors, algorithms and pumps. Smart pens bring similar data to people who prefer injections. Immunotherapy and cell replacement are opening a path to delay or reverse the disease. Rising diagnoses, wider reimbursement and earlier screening add volume. Biosimilar insulins and local manufacturers improve access outside wealthy markets. The market is expected to grow as devices, drugs and digital tools converge.
⮞In 2025, the International Diabetes Federation estimated in the 11th edition of its Diabetes Atlas that about 9.5 million people worldwide live with type 1 diabetes. The size of this patient base supports steady, lifelong demand for insulin and monitoring products.
To Get more information Type 1 Diabetes Market - Request Free Sample Report
Type 1 Diabetes Market Trends
-
Rapid adoption of automated insulin delivery systems that link pumps, sensors and algorithms
-
Spread of continuous glucose monitoring to children, pregnant women and all insulin users
-
Approval of disease-modifying immunotherapy for early-stage and recently diagnosed patients
-
Growth of insulin biosimilars and local insulin manufacturing in emerging markets
-
Early islet autoantibody screening programs that detect disease before symptoms appear
U.S. Type 1 Diabetes Market Outlook
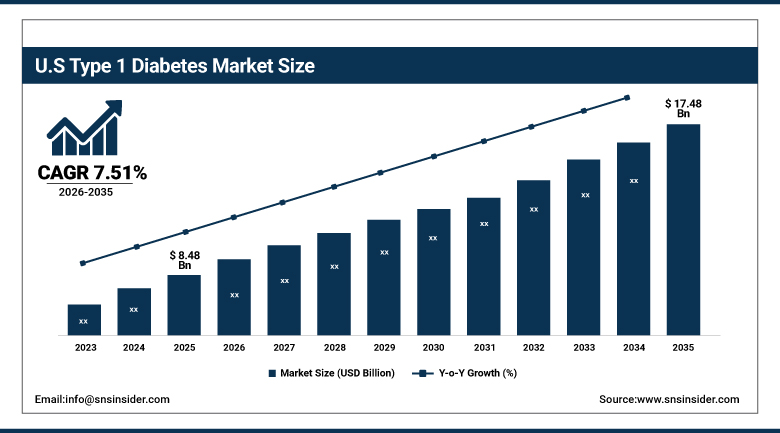
The U.S. Type 1 Diabetes Market was valued at USD 8.48 Billion in 2025 and is expected to reach USD 17.48 Billion by 2035, growing at a CAGR of 7.51% from 2026-2035.
The U.S. Type 1 Diabetes Market is the largest national market, supported by early technology adoption and broad insurance coverage. Most patients use insulin pens or pumps, and continuous glucose monitoring is standard in many clinics. Automated insulin delivery systems are gaining share among adults and children. The Food and Drug Administration has cleared several new sensors, pumps and insulins in recent years. Medicare and private insurers continue to widen coverage for monitoring supplies. Insulin price caps and biosimilar launches are lowering out-of-pocket costs. Endocrinologist shortages limit access in rural areas. Demand is expected to rise with new approvals and wider screening.
⮞The Centers for Disease Control and Prevention reported in 2026 that about 2.1 million people in the United States live with diagnosed type 1 diabetes. The figure shows the size of the U.S. patient base that relies on insulin and monitoring products.
Type 1 Diabetes Market Segment Analysis
-
By Device Type, the Insulin Pens segment dominated the Type 1 Diabetes Market with approximately 46.65% share in 2025, while the Insulin Pumps segment is the fastest growing with a CAGR of approximately 9.44%.
-
By Insulin Type, the Long-Acting Insulin segment dominated the Type 1 Diabetes Market with approximately 58.45% share in 2025, while the Rapid-Acting Insulin segment is the fastest growing with a CAGR of approximately 8.54%.
-
By Treatment Type, the Insulin Therapy segment dominated the Type 1 Diabetes Market with approximately 47.82% share in 2025, while the Automated Insulin Delivery Systems segment is the fastest growing with a CAGR of approximately 10.24%.
-
By End User, the Home Care segment dominated the Type 1 Diabetes Market with approximately 53.86% share in 2025 and is also the fastest growing with a CAGR of approximately 8.84%.
-
By Distribution Channel, the Retail Pharmacies segment dominated the Type 1 Diabetes Market with approximately 49.45% share in 2025, while the Online Pharmacies segment is the fastest growing with a CAGR of approximately 9.74%.
By Device Type, Insulin Pens Dominates the Type 1 Diabetes Market and Insulin Pumps Grows Fastest
Insulin pens lead because they are easy to carry, dose accurately and need less training than vials and syringes. Children, older adults and people with limited dexterity find cartridges simpler to use, and pen needles are cheap and widely stocked. Most insulin makers sell prefilled and reusable pens, so prescribers choose them at diagnosis. Payers favor pens because dosing errors and avoidable hospital visits fall. Smart pens that log each dose and share it with sensors add a digital layer to a familiar format. These factors keep pens at the center of daily insulin delivery in developed and emerging markets.
Insulin pumps are growing fastest as automated insulin delivery turns them from simple dosing devices into closed-loop systems. Algorithms read sensor values every few minutes and adjust basal delivery without user input, which improves time in range and reduces night-time lows. Patch pumps without tubing appeal to children and active adults, and newer models connect to smartphones. Insurers increasingly cover pumps for all people with the condition rather than only for those with poor control. Manufacturers are also launching systems cleared for pregnancy and for young children, which widens the eligible population and supports repeat purchases of consumables.
⮞In April 2026, Tandem Diabetes Care reported that Control-IQ users spent 12.6% more time in the pregnancy glucose target range in the CIRCUIT trial. The result supported FDA clearance of the system for pregnancy and shows the clinical case for automated insulin delivery.
By Insulin Type, Long-Acting Insulin Dominates the Type 1 Diabetes Market and Rapid-Acting Insulin Grows Fastest
Long-acting insulin remains the largest type because every person with the condition needs a continuous background dose. Glargine, degludec and detemir analogs provide stable coverage for up to a full day with limited peaks, which lowers the risk of overnight hypoglycemia. Prescribers pair them with mealtime insulin in multiple daily injection regimens that still treat a large share of patients. Biosimilar glargine launches have widened access and narrowed price gaps. Once-weekly basal candidates are in development and could reshape the segment, although early approvals have been for adults with type 2 diabetes. Prescription volumes stay stable because therapy continues for life.
Rapid-acting insulin is the fastest growing type as ultra-rapid analogs and inhaled formulations improve mealtime control. Faster absorption lets patients dose closer to eating and correct high readings more quickly, and pump algorithms rely on these analogs to adjust delivery. Pediatric labels are expanding, which opens a younger patient base. Competition from biosimilar aspart and lispro is lowering prices and encouraging use in emerging markets. Automated systems also raise the number of small doses delivered, which lifts consumption per patient. Clinicians increasingly prefer analogs over regular human insulin for mealtime coverage in new starts.
⮞In May 2026, MannKind announced that the U.S. FDA approved Afrezza, an inhaled mealtime insulin, for children and adolescents aged 6 and older with type 1 or type 2 diabetes. The approval extends rapid-acting options to a younger group.
By Treatment Type, Insulin Therapy Dominates the Type 1 Diabetes Market and Automated Insulin Delivery Systems Grows Fastest
Insulin therapy dominates because no approved treatment replaces it for people who have lost beta cell function. Every patient with stage 3 disease needs lifelong insulin, delivered by injection or pump, and treatment guidelines place it at the center of care. Modern analogs, biosimilars and new delivery formats keep the segment broad and competitive. Biosimilar entry has improved affordability in Asia and Latin America, where insulin access remains uneven. Health systems also buy insulin through large tenders, which gives suppliers predictable volumes. Newer therapies are expected to add to insulin rather than replace it for the foreseeable future.
Automated insulin delivery systems are the fastest growing treatment type because they combine a sensor, a pump and a control algorithm into one closed loop. Clinical studies show higher time in range and fewer severe lows, and guidelines now recommend automation for many people with the condition. New entrants have launched systems with tubeless pods, bionic pancreas algorithms and open source options. Reimbursement is widening in Europe and the Middle East, and pediatric clearances bring younger users. Software updates add features without hardware changes, which improves retention. Immunotherapy and islet cell therapy remain small today but are drawing strong investment.
⮞In June 2026, the U.S. Food and Drug Administration granted accelerated approval to Tzield (teplizumab) for pediatric patients with recently diagnosed stage 3 type 1 diabetes. The approval rests on a surrogate endpoint, C-peptide, and extends treatment options beyond insulin.
By End User, Home Care Dominates the Type 1 Diabetes Market and Is Also the Fastest Growing
Home care leads because type 1 diabetes is managed by the patient every day, with injections, glucose checks and pump changes performed outside clinical settings. Hospitals diagnose and stabilize patients, but nearly all dosing, monitoring and supply purchases happen at home. Caregivers of young children handle devices and data feeds, and remote follow-up by endocrinology teams reduces clinic visits. Insurance plans and mail order services deliver consumables directly to households. Training programs and diabetes educators help families adopt pumps and sensors. These patterns keep the home as the primary place of care and consumption for insulin and device products.
Home use is also the quickest growing setting as connected devices move care data to the cloud. Smartphone apps share sensor readings with parents and physicians, and automated systems run with little daily input. Telehealth visits have become routine for adjusting settings, which supports adoption outside large cities. Smart insulin pens and starter kits for people who prefer injections extend digital features to the home. Manufacturers design products for self-installation and simple supply replenishment, while payers favor settings that avoid hospital stays. Hospitals and clinics retain importance for new diagnoses and complex cases, and research institutes drive trials of new therapies.
⮞In January 2026, Medtronic received U.S. FDA clearance for its MiniMed Go smart multiple daily injection system, which pairs a connected insulin pen with a glucose sensor. The clearance extends connected care to home users who do not wear pumps.
By Distribution Channel, Retail Pharmacies Dominates the Type 1 Diabetes Market and Online Pharmacies Grows Fastest
Retail pharmacies lead because most people with type 1 diabetes collect insulin, test strips, pen needles and sensors through monthly prescriptions at community stores. Pharmacists provide counseling, and insurance billing and substitution rules are well established in these outlets. Chain pharmacies negotiate supply with manufacturers, which gives them reliable stock of insulin analogs and biosimilars. Pharmacy benefit managers steer patients toward preferred products, and retail locations offer same-day access during shortages or emergencies. Many chains also sell glucose monitors on prescription, which keeps traffic steady. These features make retail the default route for refill purchases in most countries.
Online pharmacies are growing fastest as mail order and subscription delivery become routine for chronic therapy. Patients value home delivery of insulin in temperature-controlled packaging, automatic refills and price comparison. Digital platforms link prescriptions from telehealth visits to dispensing, which shortens the path from diagnosis to supply. Direct-to-consumer programs from device makers also ship sensors and pump supplies straight to users. Regulators in several markets have approved e-pharmacy models, though cold chain handling and counterfeit risks require strict oversight. Younger patients and caregivers are the heaviest adopters, and subscription models improve adherence by reducing missed refills.
⮞In July 2026, Meitheal Pharmaceuticals announced that the U.S. FDA approved Garzulys (insulin aspart-fsan), a biosimilar referencing NovoLog. The approval adds a lower-cost mealtime option that pharmacies can dispense across retail and online channels.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
77.54 |
|
Europe |
Germany |
21.38 |
|
Asia Pacific |
China |
31.27 |
|
Latin America |
Brazil |
46.92 |
|
Middle East & Africa |
Saudi Arabia |
28.63 |
North America Type 1 Diabetes Market Insights
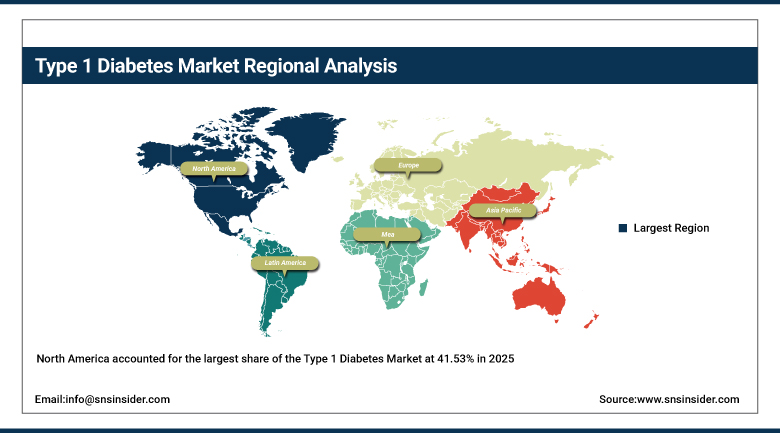
North America accounted for the largest share of the Type 1 Diabetes Market at 41.53% in 2025, led by the United States and supported by Canada. High diagnosis rates, early adoption of automated insulin delivery and broad private and public coverage keep spending per patient high. Many leading pump, sensor and insulin makers run large commercial and manufacturing bases in the region, and new products often reach patients here first. Clinical guidelines recommend continuous glucose monitoring from diagnosis, which brings sensors into routine care. Research networks also host many immunotherapy and cell therapy trials.
Affordability is the main regional debate. Insulin price caps in several U.S. states and in federal programs, together with biosimilar launches, are reducing out-of-pocket cost for many patients. Canadian provincial plans are broadening pump and sensor coverage, although criteria vary. Payers still manage utilization of devices through prior authorization, which can slow switching between brands. Telehealth endocrinology and pharmacy delivery are extending access in rural counties. Corporate restructuring, including the spin-off of diabetes device businesses, is reshaping competition, and companies are pursuing pediatric and pregnancy labels to grow addressable populations.
⮞In December 2025, the American Diabetes Association released its Standards of Care in Diabetes 2026, which recommend continuous glucose monitoring at diabetes onset and anytime thereafter. The recommendation supports broader sensor use across North American clinics.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Type 1 Diabetes Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and the Nordic countries. National health systems fund most insulin and devices, so reimbursement decisions made by bodies such as the National Institute for Health and Care Excellence shape adoption. Hybrid closed loop systems are moving from pilot programs into routine care in several countries, and Nordic clinics have been early adopters of diabetes technology. Denmark and France host major insulin manufacturers, which anchors regional production and research.
Tendering and cost control define the market. Regional tenders favor biosimilar insulins and push prices down, while governments weigh the cost of pumps and sensors against fewer long-term complications. The Medical Device Regulation has increased the certification burden on device makers. Germany's digital health application pathway supports connected diabetes tools. Cross-border supply of insulin has helped limit shortages. Gaps remain between Western and Eastern Europe in access to automated systems, which creates room for expansion as budgets grow and as pregnancy-specific and pediatric indications win funding. Regional research funding and patient registries also support trial recruitment for new therapies.
⮞In June 2026, the National Institute for Health and Care Excellence published draft guidance recommending that a pregnancy-specific hybrid closed loop system be offered to all women, trans men and non-binary people with type 1 diabetes who are pregnant or planning pregnancy. The draft points to wider public funding of automated insulin delivery in the United Kingdom.
Asia Pacific Type 1 Diabetes Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 7.84% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. Japan and Australia have mature technology markets with strong reimbursement for sensors and pumps. China is expanding local insulin manufacturing and is one of the largest producers of insulin pumps. India has a large and underdiagnosed young patient group, and public programs provide insulin at no charge in parts of the country. Rising incomes and urban healthcare spending support adoption of analogs, pens and monitors.
Access gaps remain wide. Many patients in lower-income countries still use human insulin and syringes, and glucose test strips are rationed. Chinese manufacturers such as Gan & Lee and Tonghua Dongbao are pursuing analog and biosimilar approvals, including in regulated Western markets. Governments are expanding pediatric screening and insulin supply chains, and sensor makers are launching lower-priced models. Private hospital chains in Southeast Asia adopt pumps faster than public systems. Limited numbers of diabetes educators still slow management, so training programs are being added to close this gap.
⮞In May 2026, India's Ministry of Health and Family Welfare issued a guidance document on diabetes mellitus in children that directs mobile health teams to screen children and adolescents up to 18 years and provides lifelong insulin through non-communicable disease clinics. The guidance should widen early detection of type 1 diabetes in public health programs.
MEA & Latin America Type 1 Diabetes Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Chile. Public systems supply insulin analogs and glucose meters, but coverage for pumps and sensors is limited and often depends on court orders or private insurance. Brazil's health technology assessment body, Conitec, issued a preliminary unfavorable recommendation in 2026 on public coverage of real-time glucose monitors because of budget impact, which shows the cost barrier. Private hospital networks and a growing middle class drive device uptake in major cities, and regional partnerships with global suppliers help secure insulin and sensors for public programs.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Kuwait, Qatar and South Africa lead demand. Gulf states have high diabetes prevalence and large public health budgets, and they are adopting automated insulin delivery. Julphar in the United Arab Emirates manufactures insulin locally. Across much of Africa, insulin supply is erratic, diagnosis is often late and families frequently pay out of pocket. Donation and tiered pricing programs help, but they do not reach every child, so local manufacturing and regional procurement pools are gaining policy attention.
⮞In February 2026, Insulet launched the Omnipod 5 automated insulin delivery system across Saudi Arabia, Kuwait, Qatar and the United Arab Emirates, announced at the Emirates Diabetes and Endocrine Congress. The launch shows rising demand for tubeless automated systems in the Gulf region.
Market Dynamics
Growth Drivers: Rising Diagnoses and Connected Care Drive Growth in the Type 1 Diabetes Market
Global prevalence of type 1 diabetes continues to rise, and adult-onset diagnoses account for a large share of cases, which widens the patient group beyond children. Longer survival with better care means patients remain on therapy for decades. Expanded screening for islet autoantibodies identifies people earlier and brings them into treatment pathways sooner. Each new patient generates recurring purchases of insulin, needles, sensors and pump supplies, which supports stable revenue growth for manufacturers. Public awareness campaigns and pediatric screening programs add further diagnoses in emerging markets. Digital tools that flag early warning signs, such as unexplained weight loss and thirst, help primary care doctors refer children sooner.
Continuous glucose monitors that transmit readings every few minutes now feed pumps, pens and smartphone apps, and the same data helps physicians adjust therapy remotely. New sensors with ketone detection bring safety features that appeal to families and payers. Reimbursement for sensors is expanding to all insulin users in several markets. Manufacturers also launch lower-cost sensors and longer-wear models, which increase both the number of users and the length of use. Data platforms and artificial intelligence tools add recurring software revenue, and pharmacies and clinics increasingly bundle sensors with insulin supply under a single contract.
⮞In August 2026, Abbott received U.S. FDA authorization for Libre Duo 10 Day, which the company described as the world's first dual glucose and ketone sensing technology, for people aged 2 and older. The product adds ketone information relevant to the risk of diabetic ketoacidosis.
Restraints: Insulin Cost and Access Gaps Restrain Growth in the Type 1 Diabetes Market
High prices and unequal availability of insulin and devices hinder growth, especially in low- and middle-income nations. Patients tend to ration their supplies of insulin and strips while diagnosis usually happens when they experience diabetic ketoacidosis. The pumps and monitors cost many thousands per year and have uneven coverage across the countries as well as within insurance providers. The out-of-pocket costs discourage some people from using devices or monitoring. Fragmented distribution and lack of refrigeration facilities increase the difficulty in the rural settings, and the public funds restrict procurement quantities for advanced insulin analogs.
Hypoglycemia remains a daily concern and a cause of emergency visits, and device failures or recalls can undermine trust in automated systems. Regulatory pathways for new combination products are demanding, and teplizumab eligibility is narrow because it applies to specific disease stages. Interoperability gaps between sensors, pumps and apps frustrate users who want to mix brands. Health systems also face a shortage of endocrinologists and diabetes educators who can train patients on advanced devices, which slows the shift from injections to automation. Data privacy rules and cybersecurity concerns about connected devices add compliance work for manufacturers.
⮞In May 2025, the Access to Medicine Foundation reported that company programs reached less than 10% of children and young people who needed type 1 diabetes care in 71 low- and middle-income countries in 2023. The finding highlights the scale of unmet access.
Opportunities: Cell Therapy, Immunotherapy and Early Screening Create Opportunities in the Type 1 Diabetes Market
Disease-modifying treatments could turn a chronic management market into one with curative options. Teplizumab is approved to delay onset and to preserve insulin production in newly diagnosed patients, and cell therapies are in clinical trials with early data showing insulin independence in small groups. Large companies are investing in stem cell derived islets, immune-protected cells and encapsulation. Successful products would command premium prices and could shift spending from lifelong insulin supplies toward short-course or one-time treatments, while still requiring monitoring and follow-up care. Early clinical successes also attract venture funding and large pharmaceutical partnerships, which accelerate development timelines and manufacturing scale-up.
There is growing international support for islet autoantibody screening of the general population, which will be able to detect early-stage disease prior to onset of symptoms. Early detection avoids ketoacidosis at first encounter and provides patients that can receive immunotherapy treatment. Screening requires the use of laboratories, education, and follow-up services, thus driving demand within diagnostics and digital. The emerging markets provide further upside with the use of biosimilar insulin, reduced cost pens, and local manufacture increasing access, while system labels tailored for pediatrics and pregnancy enable technology usage in new patient groups.
⮞In September 2026, Breakthrough T1D convened the first international consensus guidance, published in Diabetologia and endorsed by 20 societies, recommending general population islet autoantibody screening in childhood. The guidance supports screening-led diagnosis and earlier access to intervention.
Recent Developments:
-
In May 2026, Vertex Pharmaceuticals reported that it had completed its internal manufacturing analysis for the zimislecel Phase 1/2/3 study and resumed dosing, with updated timelines expected later in the year. The islet cell therapy is being developed to restore insulin production and has not yet been filed for approval.
-
In September 2026, Bayer announced that the U.S. FDA approved Kerendia (finerenone) for adults with chronic kidney disease associated with type 1 diabetes, based on the FINE-ONE trial. The approval adds a kidney protection option for a complication that affects long-term outcomes.
-
In August 2026, Eledon Pharmaceuticals reported that all 12 patients in a University of Chicago islet transplant study using tegoprubart achieved insulin independence and HbA1c below 6.5%, with follow-up of up to 22 months. The study is small and investigator-initiated, and it supports interest in new immunosuppression regimens for islet transplant.
-
In August 2026, Sana Biotechnology said it expects to file an IND and begin a Phase 1/2 trial of SC451, a hypoimmune-modified islet cell therapy derived from induced pluripotent stem cells, as early as this year. Its earlier UP421 study showed C-peptide production through 14 months without immunosuppression in one patient.
Type 1 Diabetes Market Key Players
-
Novo Nordisk A/S
-
Eli Lilly and Company
-
Sanofi
-
Biocon Biologics
-
MiniMed Group, Inc. (formerly Medtronic Diabetes)
-
Dexcom, Inc.
-
Abbott Laboratories
-
Insulet Corporation
-
Tandem Diabetes Care, Inc.
-
Beta Bionics, Inc.
-
Sequel Med Tech
-
Senseonics Holdings, Inc.
-
mylife Diabetes Care
-
MannKind Corporation
-
Tonghua Dongbao Pharmaceutical Co., Ltd.
-
Gan & Lee Pharmaceuticals
-
Julphar (Gulf Pharmaceutical Industries)
-
Roche Diabetes Care (Accu-Chek)
Type 1 Diabetes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 26.32 Billion |
| Market Size by 2035 | USD 52.95 Billion |
| CAGR | CAGR of 7.24% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Insulin Pens, Insulin Pumps, Insulin Syringes, Continuous Glucose Monitors, and Others) • By Insulin Type (Long-Acting Insulin, Rapid-Acting Insulin, Short-Acting Insulin, Intermediate-Acting Insulin, and Premixed Insulin) • By Treatment Type (Insulin Therapy, Automated Insulin Delivery Systems, Immunotherapy, and Islet Cell Therapy) • By End User (Home Care, Hospitals and Clinics, and Research Institutes) • By Distribution Channel (Retail Pharmacies, Online Pharmacies, and Hospital Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Biocon Biologics, MiniMed Group, Inc. (formerly Medtronic Diabetes), Dexcom, Inc., Abbott Laboratories, Insulet Corporation, Tandem Diabetes Care, Inc., Beta Bionics, Inc., Sequel Med Tech, Senseonics Holdings, Inc., mylife Diabetes Care, MannKind Corporation, Tonghua Dongbao Pharmaceutical Co., Ltd., Gan & Lee Pharmaceuticals, Julphar (Gulf Pharmaceutical Industries), Roche Diabetes Care (Accu-Chek) |

Frequently Asked Questions
Key players include Novo Nordisk, Eli Lilly and Company, Sanofi, Biocon Biologics, MiniMed, Dexcom, Abbott, Insulet, Tandem Diabetes Care, Beta Bionics, Sequel Med Tech, Senseonics, mylife Diabetes Care, MannKind, Tonghua Dongbao, Gan & Lee Pharmaceuticals, Julphar and Roche Diabetes Care.
Key opportunities include disease-modifying immunotherapy, islet cell therapy, early autoantibody screening, closed-loop insulin delivery and insulin biosimilars in emerging markets.
Rising diagnosed prevalence and the adoption of continuous glucose monitoring and automated insulin delivery are the main growth factors.
By Device Type, the Insulin Pens segment dominated the market in 2025 with an estimated 46.65% share, supported by ease of use, accurate dosing and wide availability.
North America dominated the market with a share of 41.53% in 2025, driven by early technology adoption, high diagnosis rates and broad insurance coverage.
