
Canned Tuna Market Report Scope & Overview:
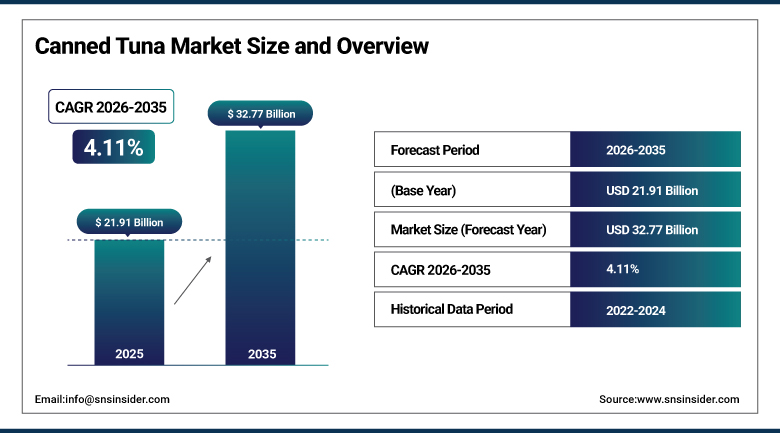
The Canned Tuna Market was valued at USD 21.91 Billion in 2025 and is expected to reach USD 32.77 Billion by 2035, growing at a CAGR of 4.11% from 2026 to 2035.
The Canned Tuna Market is witnessing consistent growth due to increasing consumer demand for ready-to-eat and protein-rich foods that have a longer shelf life. One of the most stable varieties of packaged seafood, canned tuna has advantages of longer shelf life, inexpensive protein and easy availability in almost every house across the globe. Increasing consumer awareness about health continues to boost the demand for tuna’s omega-3 fatty acids that suit health-conscious and working individuals who want to eat quickly. In addition to this, developments in packaging and processing technologies, increasing use of AI-enabled sustainability tracking systems and the increasing preference of consumers for sustainable and organic canned tuna are some of the factors driving this trend.
In 2025, Thai Union Group committed to 100% responsibly sourced canned tuna, supporting its SeaChange sustainability program and reflecting continued industry investment in traceable, certified sourcing amid rising consumer demand for ethical seafood practices.
To Get more information Canned Tuna Market - Request Free Sample Report
Canned Tuna Market Trends
- Growing consumer preference for high-protein, ready-to-eat formats is driving product innovation across pouches, meal bowls, and single-serve packaging.
- Rising adoption of blockchain and AI-based traceability technologies is helping brands verify sustainable, dolphin-safe fishing practices and build consumer trust.
- Expanding demand for flavored and regionally inspired tuna variants is broadening the category’s appeal beyond traditional plain preparations.
- Increasing prioritization of Marine Stewardship Council certified catch lines is being driven by consumer willingness to pay premiums for verified sustainable sourcing.
- Growing innovation in eco-friendly and lightweight packaging materials is helping brands meet sustainability standards while attracting eco-conscious consumers.
U.S. Canned Tuna Market Outlook
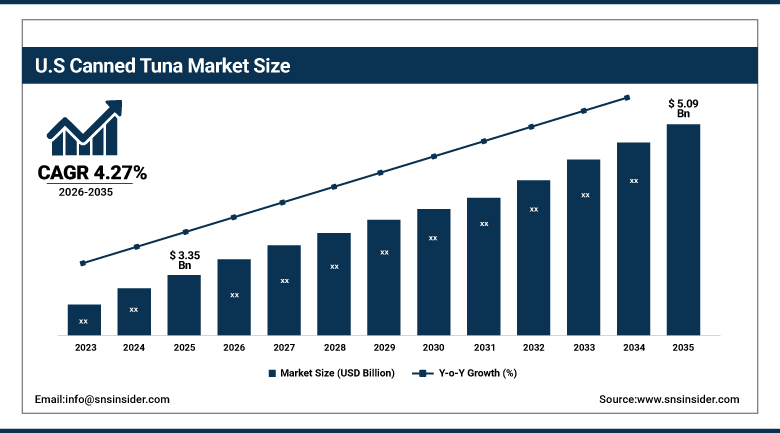
The U.S. Canned Tuna Market was valued at USD 3.35 Billion in 2025 and is projected to reach USD 5.09 Billion by 2035, growing at a CAGR of 4.27% during 2026-2035.
US Canned Tuna Market is experiencing continuous growth, thanks to the significant rise in demand for easy access to protein products, especially among the consumers who have little time but need something nutritious to eat. Canned tuna remains a health food in demand for containing omega-3 fatty acids and attracts the attention of physically active and healthy lifestyle-oriented consumers. The companies producing tuna practice sustainable fishing, using tuna from certified fishery organizations to satisfy the environmental criteria of consumers. Products such as high protein tuna in pouches and pre-seasoned meals in ready-to-eat bowls attract convenience-oriented consumers. There is a good distribution system for the products through supermarkets, convenience stores, and growing online sales.
In 2025, Bumble Bee Foods launched high-protein tuna pouches marketed toward fitness customers and meal prep enthusiasts, reflecting continued mainstream brand investment in convenient, protein-focused product formats beyond traditional canned formats.
Canned Tuna Market Segment Analysis
- By Product Type, light tuna segment dominated the canned tuna market in 2025 with around 50% share; flavored tuna segment is the fastest-growing segment.
- By Species, skipjack segment dominated the market in 2025 with around 61.65% share; yellowfin/albacore segment is the fastest-growing segment.
- By Packaging Medium, in water segment dominated the market in 2025 with around 55% share; in oil segment is the fastest-growing segment.
- By Distribution Channel, supermarkets & hypermarkets segment dominated the market in 2025; online segment is the fastest-growing segment.
By Product Type, Light Tuna Dominates the Canned Tuna Market While Flavored Tuna Registers the Fastest Growth
Light Tuna is the Market Leader in the Canned Tuna Market, earning revenues of 50% in 2025 because of its ability to attract price-sensitive customers and wide customer base as the basic type of inexpensive canned tuna fish that is available at every general retail channel globally. This is because of the existing supplier relationship with skipjack fisheries and cost-effective processing capabilities which enable competitive pricing for retail consumers. The wide range of price affordability and established consumer base of light tuna is helping in sustaining market leadership in this segment.
Flavored Tuna is the fastest growing product category in the market as the manufacturers are launching new flavors of tuna such as spice flavors inspired by different regions, which satisfy the changing demands of customers towards food diversity through convenience of the canned form of the fish. The rising interest among consumers to have ready-to-eat premium tuna flavors which do not require any further cooking is prompting manufacturers to develop new flavors of tuna fish.
By Species, Skipjack Dominates the Canned Tuna Market While Yellowfin/Albacore Registers the Fastest Growth
Skipjack dominates the Canned Tuna Market, accounting for 61.65% of revenue in 2025, as the most abundant and cost-efficient tuna species suited for large-scale commercial fishing and canning operations worldwide. Skipjack’s rapid reproduction rate and relatively stable population levels support sustainable large-scale harvesting compared to other commercially fished tuna species. The cost efficiency and sustainable harvesting profile of skipjack are reinforcing this segment’s continued market leadership.
Yellowfin/Albacore is experiencing rapid growth driven by increasing consumer demand for premium, higher-quality tuna varieties associated with superior taste and texture compared to skipjack. Rising consumer willingness to pay premium prices for albacore’s milder flavor and firmer texture, often marketed as “white meat tuna,” is compelling brands to expand premium species offerings. Growing demand for premium and gourmet canned tuna positioning is opening up substantial opportunities for commercial utilization in this segment.
By Packaging Medium, In Water Dominates the Canned Tuna Market While In Oil Registers the Fastest Growth
Water is Dominating the Canned Tuna Market owing to robust customer demand for lower-calorie and health conscious packing methods as consumers’ health awareness is growing along with dietary control. Water packed tuna has an advantage of its appeal to calorie and health conscious consumers in search of low-fat lean proteins. Broad health conscious consumer appeal and existing manufacturing capabilities of water packed tuna are contributing to this product line’s leadership in the market.
Oil is witnessing fast-growing popularity with premium and gourmet positioning tactics more often resorting to oil-packed tuna, especially olive oil packed tuna considered of higher taste and culinary possibilities. Growing demand for premium Mediterranean style canned tuna is forcing manufacturers targeting European gourmet consumers to produce oil packed tuna. Premiumization trends prevailing in the overall category of canned fish are presenting a lot of opportunities for commercial application in this segment.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
Europe |
Germany |
21.60% |
|
North America |
United States |
84.90% |
|
Asia Pacific |
China |
33.40% |
|
Middle East & Africa |
UAE |
22.10% |
|
Latin America |
Brazil |
23.90% |
North America Canned Tuna Market Insights
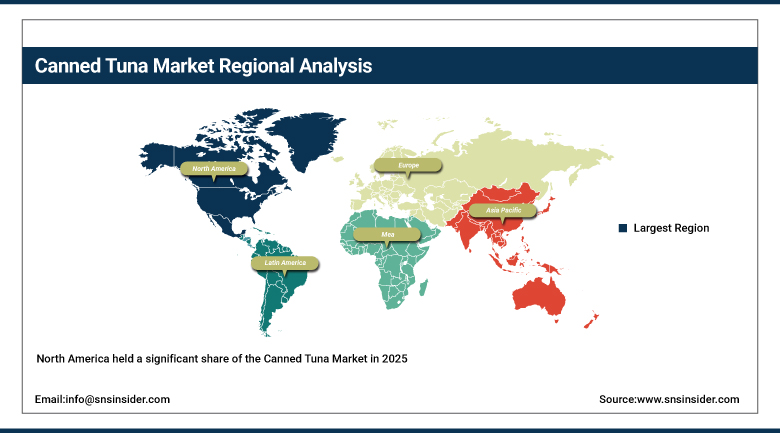
North America held a significant share of the Canned Tuna Market in 2025, supported by strong demand for convenient protein sources among busy consumers and well-established canned seafood brand recognition. Rising consumer interest in sustainable fishing practices and organic canned tuna options across the United States and Canada is supporting product innovation. Increasing investment in high-protein and ready-to-eat product formats is further reinforcing North America’s market position.
The United States accounted for approximately 84.90% of the North American market in 2025, reflecting its large consumer base and extensive canned seafood brand distribution infrastructure. Canada is contributing to regional growth through steady demand for convenient, protein-rich packaged seafood products.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Canned Tuna Market Insights
Europe is expected to have been dominant in the global Canned Tuna Market in 2025, with an estimated revenue market share of 41.65% of the global market, given the fact that the region has a long-standing reputation for having well-liked and convenient fish products such as canned tuna due to their nutritional value like high protein and omega-3 fatty acids. The increased awareness about sustainability and ethical fishing is influencing the consumption patterns in the major countries in Europe. Certain customer demographics have a greater inclination toward products that are more responsible for the environment.
In 2025, Germany was expected to account for an approximate market share of 21.60% of the total European market due to the strong customer preferences in the country for protein-rich fish products. The other European countries like Spain, Italy, and France have also contributed positively to market growth in the region. Spain and Italy are known to have globally renowned canned tuna brands.
Asia Pacific and Latin America Canned Tuna Market Insights
Asia Pacific is exhibiting steady growth as strong seafood dietary traditions and expanding convenience food demand support sustained canned tuna consumption across the region. Latin America is similarly benefiting from expanding modern retail infrastructure and growing consumer interest in convenient, protein-rich packaged food products across major regional markets.
China accounted for approximately 33.40% of the Asia Pacific market in 2025, supported by strong seafood dietary traditions and expanding convenience food demand. Brazil represented 23.90% of the Latin American market in 2025, driven by expanding modern retail penetration, with Mexico also contributing to regional growth through rising interest in convenient protein sources.
Middle East & Africa Canned Tuna Market Insights
The Middle East & Africa region is expected to register the fastest CAGR in the Canned Tuna Market during 2026–2035, driven by rising urbanization, expanding modern retail infrastructure, and growing consumer adoption of convenient, protein-rich packaged food products. The UAE and Saudi Arabia are witnessing particularly strong growth as expanding middle-class populations increasingly adopt Western-style packaged food consumption patterns. Rising product innovation and growing consumer awareness regarding canned tuna’s nutritional benefits are further supporting market expansion. Rising demand for affordable, shelf-stable protein sources is also reinforcing the region’s above-average growth trajectory compared with more mature markets.
The UAE led the Middle East & Africa market with a 22.10% regional share in 2025, supported by growing urbanization and expanding modern retail penetration. Saudi Arabia and South Africa are also contributing meaningfully to regional growth, with rising demand for convenient, affordable protein sources across expanding urban populations.
Market Dynamics
Growth Drivers: Convenient Protein Demand and Health Consciousness Driving Market Growth
The key drivers behind the growth of the Canned Tuna Market are increasing consumer demand for easy, protein-filled, and long shelf life products due to urbanization and lifestyle changes. Due to its reputation as a low-cost, nutritious, and easy to prepare protein product, producers are experiencing continuous growth potential in retail as well as in foodservice, which further helps in growth in the global canned tuna market.
Increasing awareness about health is adding to the growing demand for the omega-3 fatty acids in the product among health-conscious consumers. Innovation in terms of packaging and processing techniques, including the use of AI technology in the supply chain management of the product, is driving sustainability trends in the canned tuna market.
Restraints: Overfishing Concerns and Raw Material Price Volatility Limiting Market Expansion
Though the market shows potential due to strong demand, the category will face several barriers linked to the overfishing issue and strict regulatory requirements for dolphin-safe fishery methods that will demand continual investments. The extreme instability of input cost due to the volatility of tinplate metal packaging and international fuel and transportation taxes will remain a challenge for processing margins. The variability of raw materials depending on the tuna catches and fishing quotas may influence the financial performance of manufacturers and the stability of pricing.
The high price of sustainability certification, traceability solutions, and compliance with regulatory demands adds up to high production costs and impacts negatively on price competitiveness of smaller manufacturers. Besides, the growing competition of seafood products from international manufacturers and private labels is another factor adding pressure on prices.
Opportunities: Sustainable Sourcing Innovation and Premium Product Expansion Creating New Growth Avenues
Sustainability through innovative sourcing, premium product offerings, and flavors as well as entry into emerging markets represent significant opportunities. Creating Marine Stewardship Council certified catch lines with digital traceability from vessels to cans could address the emerging consumer trend to be willing to pay premiums for sustainability. Manufacturers can benefit from consumer demand for high-protein, ready-to-eat products such as pouches and meal bowls. Offering more flavors and regional varieties of tuna is yet another way for manufacturers to differentiate themselves and provide more consumption occasions.
Manufacturers can innovate on environmentally friendly and lightweight packaging materials, thereby gaining differentiating, sustainability-related product positioning as well as attracting environment-conscious consumers. Investment in advanced technologies in the form of AI-based vessel tracking and blockchain traceability represents another opportunity for companies to gain consumers' trust and ensure regulatory compliance at the same time. Investing in emerging markets with high urbanization rate represents another important opportunity for category growth in the long run.
Recent Developments:
- 2026: Australian retailers accelerated the transition toward certified sustainable canned tuna, with approximately 70% of canned tuna sold in Australia sourced from MSC-certified fisheries. Coles, Woolworths, and ALDI also shifted their private-label tuna ranges to 100% MSC-certified sourcing.
- 2026: Thai Union reported that more than 99.9% of its tuna was responsibly sourced, alongside 100% vessel-level traceability and 95% on-the-water monitoring coverage, highlighting the growing importance of traceability, responsible sourcing, and supply-chain transparency in the canned tuna industry.
- 2025: StarKist Co. expanded its ready-to-eat tuna bowl portfolio, introducing pre-seasoned meal options for convenient, healthy meal choices.
Canned Tuna Market key players are:
- Thai Union Group PCL
- StarKist Co.
- Bumble Bee Foods, LLC
- Bolton Group S.p.A.
- Century Pacific Food, Inc.
- Jealsa Rianxeira S.A.
- Princes Limited
- John West Foods Ltd.
- Dongwon F&B Co., Ltd.
- FCF Co., Ltd.
- Frinsa del Noroeste S.A.
- Calvo Group
- Wild Planet Foods, Inc.
- American Tuna, Inc.
- Ocean Brands Ltd.
- Grupo Conservas Garavilla S.L.U.
- Tri Marine International Pte. Ltd.
- Pescanova S.A.
- Connors Bros. (Clover Leaf Seafoods)
- Maruha Nichiro Corporation
Canned Tuna Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.91 Billion |
| Market Size by 2035 | USD 32.77 Billion |
| CAGR | CAGR of 4.11% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Light Tuna, Flavored Tuna, and Others) • By Species (Skipjack, Yellowfin/Albacore, and Others) • By Packaging Medium (In Water, and In Oil) • By Distribution Channel (Supermarkets & Hypermarkets, and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thai Union Group PCL; StarKist Co.; Bumble Bee Foods, LLC; Bolton Group S.p.A.; Century Pacific Food, Inc.; Jealsa Rianxeira S.A.; Princes Limited; John West Foods Ltd.; Dongwon F&B Co., Ltd.; FCF Co., Ltd.; Frinsa del Noroeste S.A.; Calvo Group; Wild Planet Foods, Inc.; American Tuna, Inc.; Ocean Brands Ltd.; Grupo Conservas Garavilla S.L.U.; Tri Marine International Pte. Ltd.; Pescanova S.A.; Connors Bros. (Clover Leaf Seafoods); Maruha Nichiro Corporation. |
Frequently Asked Questions
Key players include Thai Union Group PCL, StarKist Co., Bumble Bee Foods, LLC, Bolton Group S.p.A., and Century Pacific Food, Inc., among others.
Key opportunities include sustainable sourcing innovation with digitized traceability, premium and flavored product expansion, high-protein ready-to-eat formats, eco-friendly packaging development, and expansion into emerging urbanizing markets.
The market is driven by rising consumer demand for convenient, protein-rich, and long-shelf-life food options amid urbanization and changing lifestyles.
The Light Tuna segment dominated the Canned Tuna Market in 2025, accounting for 50.00% of revenue share.
The Europe region dominated the Canned Tuna Market in 2025, accounting for approximately 41.65% of global market share, driven by strong consumer preference for protein-rich, omega-3-containing seafood.
