
Central Lab Market Report Scope & Overview:
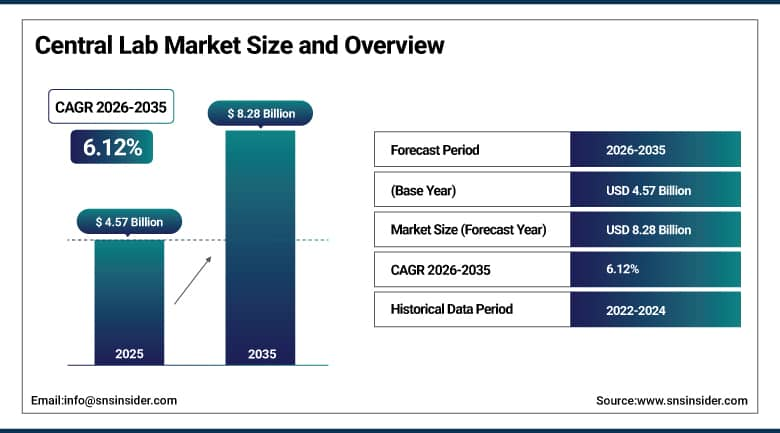
The Central Lab Market was valued at USD 4.57 Billion in 2025 and is estimated at USD 4.85 Billion in 2026. It is projected to reach USD 8.28 Billion by 2035, advancing at a CAGR of 6.12% from 2026 to 2035. Central laboratories provide standardized safety, biomarker, genomic, and specialty testing for multi-site clinical trials, so that results from different hospitals can be compared on one validated platform. Rising trial complexity, outsourcing by sponsors, and wider use of biomarkers in study design are lifting demand for these services across all participating countries.
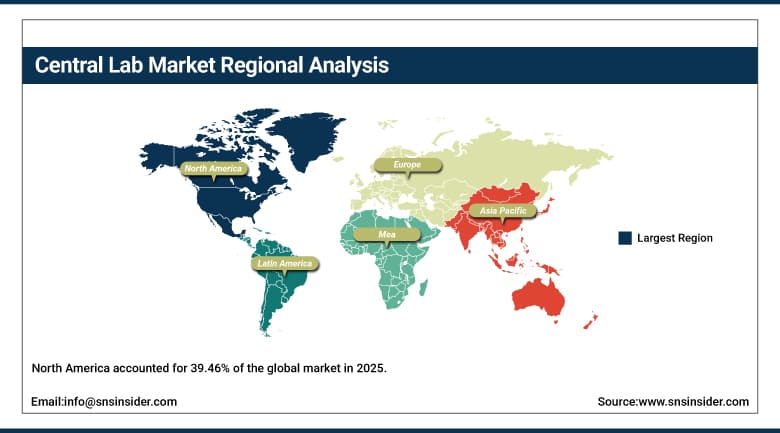
North America was the largest regional market in 2025 with a 39.46% share. A large concentration of sponsors, a deep base of accredited laboratories, and a high volume of late-stage studies keep the region ahead. Europe follows with a mature trial network and strong regulatory harmonization. Asia Pacific is expected to register the fastest expansion over the forecast period because sponsors are moving more studies to China, India, Japan, and South Korea and laboratories are adding local capacity to process samples near the sites. Latin America and Middle East & Africa remain smaller but are building capacity.
To Get More Information On Central Lab Market - Request Free Sample Report
Key Report Takeaways
- By service type, biomarker services held a 30.84% share in 2025, while genetic and genomic services are the fastest growing.
- By therapeutic area, oncology accounted for a 33.72% share in 2025, while neurology is the fastest growing.
- By clinical trial phase, Phase III represented a 47.38% share in 2025, while Phase II is the fastest growing.
- By end user, pharmaceutical companies commanded a 46.52% share in 2025, while biotechnology companies are the fastest growing.
- By region, North America led with a 39.46% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Biomarker and genomic testing is taking a larger share of every trial budget. Sponsors now collect samples for exploratory markers from the first participant, which raises the number of assays that a central laboratory must run and store.
Decentralized and hybrid trial designs are changing sample logistics. Home collection, local phlebotomy, and direct-to-participant kits require central laboratories to track specimens in real time and to manage shipments across many more collection points.
Laboratory information systems and automation are being upgraded. Providers are standardizing software across sites so that sponsors receive consistent data formats, faster query resolution, and clearer audit trails for regulatory inspections.
Capacity is moving toward Asia Pacific. Acquisitions and new facilities in China and nearby countries reflect the growing share of global studies that enroll participants there and the need to avoid long international shipping times.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Growth in Clinical Trial Volumes and Multi-Site Studies |
+3.18% |
Global, strongest in Asia Pacific |
Short term (2 years or less) |
|
Outsourcing by Pharmaceutical and Biotechnology Sponsors |
+2.46% |
North America and Europe |
Medium term (2 to 4 years) |
|
Biomarker and Precision Medicine Testing Demand |
+1.83% |
Global |
Medium term (2 to 4 years) |
|
Decentralized Trials and Digital Sample Tracking |
+1.52% |
North America and Europe |
Medium term (2 to 4 years) |
|
Rising Research Investment and Pipeline Complexity |
+1.17% |
Global |
Long term (4 years or more) |
Growth in Clinical Trial Volumes and Multi-Site Studies
The number of clinical studies under way keeps rising, and each multi-country trial needs standardized testing that individual hospital laboratories cannot supply. Central laboratories fill this need by applying one method, one reference range, and one data format to samples from every site. The World Health Organization trial registry shows that China registered 127,650 trials between 2019 and June 2026, which illustrates how fast study activity is spreading across Asia Pacific. More sites mean more kits, more shipments, and more testing for providers.
Outsourcing by Pharmaceutical and Biotechnology Sponsors
Drug developers prefer to outsource specialized laboratory work so that internal teams can focus on science and portfolio decisions. Small and mid-sized biotechnology companies in particular lack the staff and accreditation needed to run global safety and biomarker testing. The U.S. Food and Drug Administration approved 46 novel drugs in 2025, and each new program starts a cycle of trials that depend on contracted laboratories. Long-term service agreements give providers visible revenue and encourage steady investment in instruments and quality systems.
Biomarker and Precision Medicine Testing Demand
Trial protocols increasingly call for biomarker screening to select participants, confirm mechanism, and measure response. These tests often use flow cytometry, immunoassays, sequencing, or mass spectrometry, which require specialized instruments and validated procedures that few sponsors maintain themselves. Oncology, neurology, and immunology programs generate the heaviest demand. Central laboratories that offer wide assay menus and reliable turnaround times become preferred partners, and the added complexity of each study raises the value of every sample processed. Study teams therefore treat laboratory selection as a strategic choice.
Decentralized Trials and Digital Sample Tracking
Remote and hybrid study designs allow participants to give samples at home, in local clinics, or at mobile sites. This approach widens recruitment but multiplies the number of shipping routes and handling steps. The European Medicines Agency received 2,844 initial trial applications in its Clinical Trials Information System during 2025, many of them multinational. Central laboratories answer with barcoded kits, temperature monitoring, and platforms that give sponsors live visibility of every specimen from collection to result. Such tools also reduce lost samples.
Rising Research Investment and Pipeline Complexity
Growing research budgets and more complex drug modalities, including cell and gene therapies, increase the number and type of assays needed in each program. ClinicalTrials.gov listed 601,694 registered studies as of November 2026, a measure of the breadth of global development activity. Complex products often require specialty testing for immune response, safety markers, and long-term follow-up. Providers that invest in new methods and flexible capacity can secure sponsors early and keep them across later phases. This breadth keeps demand resilient across cycles.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Operating and Infrastructure Cost |
-1.64% |
Global |
Medium term (2 to 4 years) |
|
Shortage of Skilled Laboratory Personnel |
-1.22% |
Global |
Long term (4 years or more) |
|
Stringent Regulation and Accreditation Burden |
-0.77% |
North America and Europe |
Long term (4 years or more) |
|
Complex Multi-Region Sample Logistics |
-0.41% |
Asia Pacific, Latin America, and Middle East & Africa |
Medium term (2 to 4 years) |
High Operating and Infrastructure Cost
Running a central laboratory requires accredited facilities, cold-chain storage, high-throughput instruments, kit production lines, and validated software, and all of these carry heavy fixed cost. Small providers struggle to match the scale of global networks, and sponsors seeking lower prices can push margins down. Costs for dry ice, courier services, and temperature-controlled packaging add to the burden, since a single shipment error can force a participant to repeat a visit and delay a study. Low utilization of idle capacity further erodes returns during slow periods.
Shortage of Skilled Laboratory Personnel
Central laboratories depend on trained technologists, project managers, and data specialists who understand good clinical practice and accreditation rules. Competition for these workers is intense, and turnover raises training cost and quality risk. Expansion into new regions is limited by the time it takes to build a qualified team. Providers respond with automation and structured training, but staffing gaps can still slow the start of new studies and limit capacity during peak periods. Wage pressure in major trial hubs adds to the challenge.
Stringent Regulation and Accreditation Burden
Laboratories handling trial samples must follow national accreditation rules, good clinical and laboratory practice, and strict data integrity standards. In August 2026 the Centers for Medicare & Medicaid Services listed 300,720 laboratories in its CLIA database, which shows how many facilities operate under the framework in the United States. Every additional jurisdiction adds audits, documentation, and proficiency testing, raising compliance cost and lengthening the time needed to open a new site. Inspections can also lead to costly corrective actions when findings arise.
Complex Multi-Region Sample Logistics
Moving biological specimens across borders requires export permits, customs clearance, and unbroken temperature control. Delays in emerging regions with limited courier networks can compromise sample stability and force retesting. Political events and airline capacity shifts add further uncertainty. Sponsors increasingly ask providers to place laboratories closer to enrolling sites, but building local facilities requires time and capital, so logistics remain a practical limit on growth in several markets. Seasonal weather disruption and holiday shipping limits create further delays for time-sensitive specimens.
Central Lab Market Segment Analysis
By Service Type, Biomarker Services Dominate Central Lab Market; Genetic and Genomic Services to Register Fastest Growth.
Biomarker Services hold dominance due to the presence of almost every protocol using exploratory and confirmatory biomarkers, which need to be carried out using highly specialized instruments and expertise. Sponsors prefer validated assays that can be used again and again in different programs and central vendors can provide an extensive range of menus within one contract. The demand is maximum in oncology and immunology programs wherein biomarker data is used to determine patient selection and doses to be administered. Biomarker services have been contributing 30.84% of the revenue generated by the industry in 2025.
Genetic and genomic services hold the position of highest growth rates due to the widespread use of sequencing and polymerase chain reaction panels in clinical trial designs. The falling costs per sample and increasing gene and cell therapy programs have increased testing frequency, besides sponsors prefer germ line and tumor profiling for participant stratification. Genetic and genomic vendors are investing in sequencers and bioinformatics team members, and this domain is expected to grow at a CAGR of 8.04% during 2026-2035.
By Therapeutic Area, Oncology Dominates Central Lab Market; Neurology to Register Fastest Growth.
Oncology leads because cancer drugs are more numerous than any other drug programs, and frequent sampling is needed due to safety issues, pharmacokinetic study, and tumor markers. It is common for studies to involve people from many different countries, which promotes centralization of testing services. Combination therapy contributes to increased number of visits and specimens per each participant. Oncology studies took 33.72% share of the market in 2025. Long-term adjuvant and maintenance studies add to sample volume and provide opportunities for long-term contracts due to the long period of testing.
Neurology is expected to be the fastest-growing area as developers work on drug programs for Alzheimer disease, Parkinson disease, and neurological disorders. Programs of this type require fluid biomarker analysis, genetic screening, and extended duration of follow-up which increases workload of laboratories. Blood biomarkers will substitute invasive techniques in the future, thus making clinical trials more attractive, while the segment will grow by a CAGR of 6.74% over 2026-2035 period. Increase in the patient pool, emergence of new fluid biomarker tests, and ongoing financial investments into research also help.
By Clinical Trial Phase, Phase III Dominates Central Lab Market; Phase II to Register Fastest Growth.
Phases III lead due to having the largest number of subjects, taking place at the most locations, and lasting the longest time periods. Each subject offers multiple specimens for safety and efficacy, thus increasing the volume of tests significantly. Consistent methodology in laboratories is expected for the pivotal trials, thus experienced central laboratories are chosen by sponsors. The share of Phase III work on the market was 47.38% in 2025. Long time periods imply repeated blood and urine sampling, thus maintaining high laboratory workload during the whole study.
Phase II is the fastest-growing segment since more and more drug candidates go through the proof-of-concept stage and sponsors conduct biomarker analysis to improve dosing and recruitment. Many mid-stage trials are organized by venture-capital-backed biotechnology firms and outsourced laboratory services since the start. Adaptive design in Phase II trials increases sampling and contributes to 6.81% CAGR between 2026 and 2035. Early phases of clinical research are contracted to laboratories with fast development of methodologies, thus reducing start-up times.
By End User, Pharmaceutical Companies Dominate Central Lab Market; Biotechnology Companies to Register Fastest Growth.
Pharmaceutical companies lead because they sponsor the largest and most numerous trials and hold long-term supplier agreements with global laboratory networks. Their global programs require harmonized methods in dozens of countries, and internal budgets allow them to buy a full range of safety, biomarker, and specialty testing. Pharmaceutical sponsors accounted for 46.52% of the market in 2025. Established relationships also reduce onboarding time, and sponsors with many concurrent programs benefit from volume pricing and shared data platforms across studies.
Biotechnology companies are growing fastest as venture funding and licensing deals expand the number of early-stage programs. These firms usually lack in-house laboratories and rely on providers for protocol advice, kit design, and data delivery. As more candidates progress from discovery to clinical testing, spending rises, and this segment is expected to record a CAGR of 7.31% from 2026 to 2035. Regulatory incentives for rare disease and accelerated programs also draw smaller sponsors into early clinical testing worldwide.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
91.37% |
|
Europe |
Germany |
28.19% |
|
Asia Pacific |
China |
37.64% |
|
Middle East & Africa |
South Africa |
38.91% |
|
Latin America |
Brazil |
47.26% |
North America Central Lab Market
North America accounted for 39.46% of the global market in 2025. The region hosts the headquarters of most large sponsors and several of the biggest laboratory networks, and it runs a high volume of late-stage trials. Accredited facilities, mature courier networks, and close ties between providers and regulators support leadership. Sponsors also prefer to keep complex biomarker work in laboratories with established quality histories. Regulatory familiarity with sponsor submissions also helps, since inspectors and sponsors share a common view of acceptable data quality.
The United States contributed USD 1.65 Billion in 2025 and is projected to grow at a CAGR of 6.30% from 2026 to 2035. Large academic medical centers supply a deep pool of investigators, and biotechnology clusters in several states generate steady demand for outsourced testing. Canada adds a smaller contribution through trials run by research hospitals and by cooperative groups that rely on central specialty laboratories. Specialty laboratories across several states also supply kit production and biorepository services at scale to sponsors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Central Lab Market
Europe maintains its second largest regional presence due to a well-developed hospital infrastructure, strong scientific research, and unified clinical trial platform that simplifies submission processes from multiple countries. Germany, France, the UK, Spain, and Italy conduct the greatest number of trials, and labs in the Netherlands and Belgium act as centers for samples receipt and kit distribution. The region is attractive to sponsors because of the diversity of patients and investigators. The possibility to enroll patients with rare diseases due to cross-border studies makes work of specialty labs busy.
Strong data protection laws and accreditation increase the cost of the region, but at the same time make sponsors feel more confident because of defensibility of data necessary for submission. Sponsors utilize specialized laboratories in Europe to conduct genetic and pathology tests in rare disease and oncology studies. Laboratories continue their investments into automatization and tracking of data, and also there is a trend towards consolidation of laboratories within the region. Regional laboratories begin to combine their expertise in histology/pathology and molecular testing and become an entry point for sponsors' needs for tissue-based endpoints in oncology/immunology programs.
Asia Pacific Central Lab Market
Asia Pacific is the fastest-growing region, expected to register a CAGR of 7.66% from 2026 to 2035. Global sponsors are enrolling more participants in China, India, Japan, South Korea, and Australia because of large patient populations, faster recruitment, and supportive regulatory reforms. Laboratories in the region are expanding capacity to process samples locally and cut the time and risk of long-distance shipping. Government support for clinical research, including faster approvals for trial applications in several countries, adds further momentum for providers.
Cross-border acquisitions and new facilities show the strategic importance of the region. Local providers in China are building accredited central capabilities, while global networks add sites to serve regional studies. Japan and Australia offer mature regulatory systems for early-phase work. Differences in export rules and genetic sample regulations still require careful planning, particularly for biobanked material. India offers cost advantages and trained laboratory staff, while Singapore and Australia serve as regional hubs for specialty assays and sample consolidation before onward shipment.
Latin America Central Lab Market
Latin America is led by Brazil, where a large patient base, a growing network of research hospitals, and regulatory improvements attract international sponsors. Mexico, Argentina, and Colombia add trial activity, especially in oncology, infectious disease, and cardiovascular studies. Central laboratories in the region often work as regional hubs that prepare kits and pack samples for shipment to larger processing sites. Industry associations and ministries of health are also working to shorten ethics approval and import permit timelines, which has made the region more attractive for international sponsors.
Currency volatility and customs delays can complicate operations, so sponsors favor providers with established local partners. Demand for testing is rising as more studies include Latin American sites to broaden diversity and speed recruitment. Investment in accredited facilities remains modest compared with other regions, but steady trial growth suggests gradual expansion of local capacity. Providers that combine local sample handling with links to large processing sites in North America can manage regional regulatory differences while keeping turnaround times acceptable for sponsors.
Middle East & Africa Central Lab Market
Middle East & Africa is the smallest region, though Gulf countries are investing in clinical research infrastructure and new hospital campuses. Saudi Arabia and the United Arab Emirates are encouraging sponsors to run studies locally, and regulatory timelines have improved. Providers establish partnerships with hospital groups to offer sample handling and limited local testing before shipment to central sites. University hospital campuses in the Gulf are also being equipped with research units that can support early-phase studies and routine specimen processing.
South Africa has the most developed trial ecosystem in Africa, with accredited laboratories that serve infectious disease and vaccine studies across the continent. Elsewhere, limited cold-chain capacity and uncertain customs processes restrict activity. Donor-funded research programs help build laboratory capability, and these efforts should support a gradual rise in locally processed samples over the forecast period. Clinical research organizations in the region report growing sponsor interest in treatment-naive populations for vaccine and infectious disease studies, which raises demand for qualified specimen handling.
Competitive Landscape
The market is moderately concentrated. A small group of global laboratory networks holds a large share of sponsor contracts, while regional and specialty providers compete for specialized assays, local studies, and early-phase work. Competition depends on geographic reach, accreditation, assay breadth, turnaround time, and the quality of data delivery. Sponsors often split work between a primary global provider and smaller specialists, which keeps pricing competitive.
Vendors pursue acquisitions, capacity expansion, and technology upgrades. Purchases of regional laboratories add local testing capability and widen the service network, while new kit production and logistics hubs improve delivery to sites. Investments in laboratory software, automation, and real-time specimen tracking help providers differentiate on data quality, and partnerships with contract research organizations extend reach into outsourced trial management.
Central Lab Market Industry Leaders
1. Labcorp: Operator of a global network of central laboratories with kit production, specialty testing, biomarker services, and a biorepository.
2. IQVIA Laboratories: Provider of central laboratory and specialty biomarker services supporting global clinical trials.
3. ICON Central Laboratories: Operator of accredited laboratories in Europe, the United States, and Asia serving a wide range of studies.
4. Eurofins Central Laboratory: Provider of safety, efficacy, biomarker, and pathology testing from wholly owned sites in four countries.
5. Medpace: Contract research organization with integrated central and bioanalytical laboratories and a global logistics network.
Companies Covered in this Report
- Labcorp
- IQVIA Laboratories
- ICON Central Laboratories
- Eurofins Central Laboratory
- Medpace
- Cerba Research
- LabConnect
- ACM Global Laboratories
- Frontage Laboratories
- Precision for Medicine
Recent Industry Developments
- June 2024: Thermo Fisher Scientific expanded its clinical research laboratory in Kentucky and announced a biorepository in Covington.
- March 2025: IQVIA Laboratories launched Site Lab Navigator, an electronic requisition tool for clinical trial sites.
- June 2025: Medpace expanded its logistics hub in Leuven, Belgium, to more than 4,000 square meters with capacity for over 300,000 kits.
- March 2026: Frontage Laboratories completed its acquisition of Teddy Clinical Research Laboratory in Shanghai, adding central laboratory capacity in China.
- March 2026: LabConnect opened a facility in Wuxi, China, bringing its network to eight global locations.
- September 2026: Labcorp acquired MLM Medical Labs, a central and specialty laboratory provider with sites in the United States, Germany, and South Africa.
Scope and Research Methodology
This report defines the Central Lab Market as the commercial value of centralized laboratory services supplied to clinical trial sponsors, including safety testing, biomarker analysis, genetic and genomic testing, pathology, microbiology, specimen management, kit production, and related logistics. Services are bought by pharmaceutical, biotechnology, medical device, and research organizations. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Segmentation covers service type, therapeutic area, clinical trial phase, end user, and region, with leading countries analyzed in each region. Equipment sales and in-house hospital laboratory work are excluded, and revenue is counted only when services are sold to a trial sponsor.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement teams, and end-user stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test how demand is expected to change by phase and region. Findings from both routes are cross-referenced. Analysts also review company disclosures for laboratory capacity, accreditation, and contract information.
Market engineering follows a bottom-up build from provider revenue and trial activity data, cross-checked top-down against sponsor research spending and registered study counts. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate outsourcing trends, regulation, technology change, and macroeconomic conditions. Sensitivity checks test pricing, trial starts, and capacity assumptions, and senior analysts review every estimate and narrative section for consistency before release. Regional estimates are checked against registered study counts, hospital capacity, and national research spending so that country totals align with the global figure. Scenario analysis then stresses assumptions on trial starts, pricing, and capacity utilization.
Central Lab Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.57 Billion |
| Market Size by 2035 | USD 8.28 Billion |
| CAGR | CAGR of 6.12% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Biomarker Services, Genetic and Genomic Services, Safety Testing, Anatomic Pathology and Histology, Microbiology and Virology, and Specimen Management and Storage) • By Therapeutic Area (Oncology, Neurology, Cardiology, Infectious Diseases, and Others) • By Clinical Trial Phase (Phase I, Phase II, Phase III, and Phase IV) • By End User (Pharmaceutical Companies, Biotechnology Companies, Contract Research Organizations, Medical Device Companies, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Labcorp, IQVIA Laboratories, ICON Central Laboratories, Eurofins Central Laboratory, Medpace, Cerba Research, LabConnect, ACM Global Laboratories, Frontage Laboratories, Precision for Medicine |

Frequently Asked Questions
The market was valued at USD 4.57 Billion in 2025 and is estimated at USD 4.85 Billion in 2026. It is projected to reach USD 8.28 Billion by 2035.
North America led with a 39.46% share in 2025. Asia Pacific is the fastest-growing region, with a CAGR of 7.66% from 2026 to 2035.
The market is projected to expand at a CAGR of 6.12% from 2026 to 2035.
Biomarker services, oncology, Phase III studies, and pharmaceutical companies lead their axes. Genetic and genomic services, neurology, Phase II studies, and biotechnology companies grow fastest.
Labcorp, IQVIA Laboratories, ICON Central Laboratories, Eurofins Central Laboratory, and Medpace are the best-documented providers.
