
Change Management Consulting Market Report Scope & Overview:
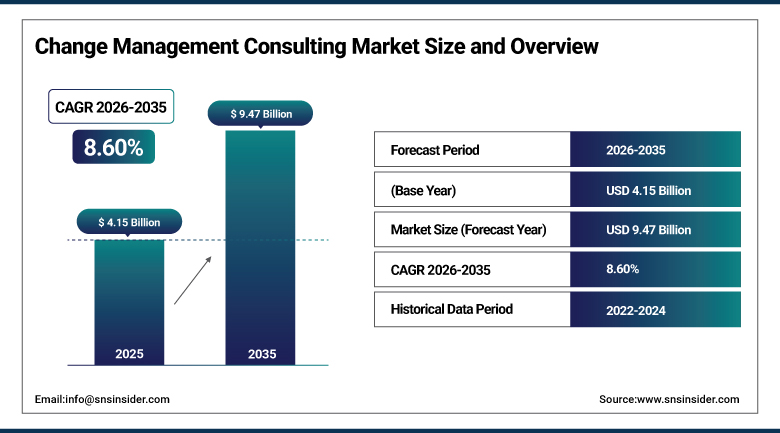
The Change Management Consulting Market was valued at USD 4.15 Billion in 2025 and is expected to reach USD 9.47 Billion by 2035, growing at a CAGR of 8.60% from 2026-2035.
In the Change Management Consulting Market, consulting services are provided to help organizations plan and implement changes in terms of technology, structures, processes, and culture such that any investment in change management brings about the expected outcome. This involves strategic advice, communication, and measuring of the impacts of changes made. Opportunities are caused by the digital transformation and artificial intelligence initiatives, mergers and restructuring of the organization, hybrid work model, and sustainability. On the other hand, the threats include resistance from management, absence of qualified consultants, and budget limitations.
⮞Consulting firms are building generative AI into workforce change services. In January 2026, Accenture expanded its generative AI-powered transformation and workforce change services. The expansion shows how large advisers are using AI to scale stakeholder analysis, communications and training for clients adopting new technology.
To Get more information Change Management Consulting Market - Request Free Sample Report
Change Management Consulting Market Trends
- Use of AI-driven analytics to measure adoption and link change activity to business results
- Integration of change management into digital, ERP and AI transformation programs from the outset
- Growth of hybrid and remote delivery supported by digital engagement platforms
- Increasing demand from small and medium enterprises for packaged and subscription-based offerings
- Sustainability and ESG-driven organizational change, particularly in Europe
U.S. Change Management Consulting Market Outlook
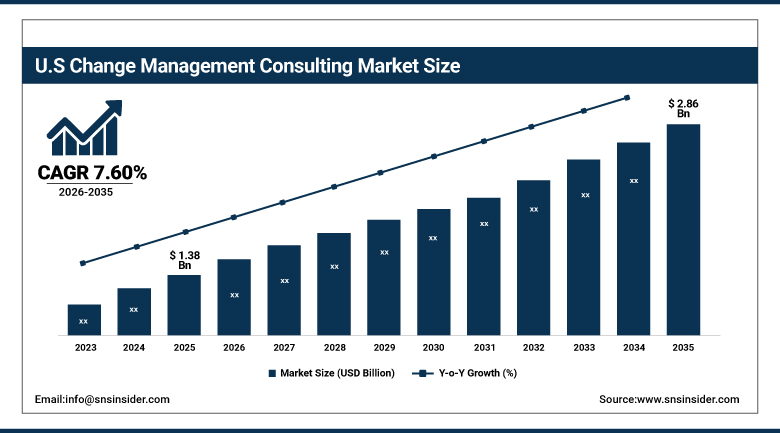
The U.S. Change Management Consulting Market was valued at USD 1.38 Billion in 2025 and is expected to reach USD 2.86 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The U.S. Change Management Consulting Market is supported by the largest concentration of large enterprises, heavy investment in cloud, ERP and AI programs, frequent mergers and restructurings, and the presence of the major advisory firms. Banks, healthcare systems, technology companies and federal agencies commission change programs to speed adoption of new systems and ways of working. Growth is moderated by market maturity, by in-house transformation offices and by sensitivity of consulting budgets to economic conditions.
⮞Alliances are linking technology platforms with change services. In November 2024, PwC and Microsoft announced an alliance to help clients apply generative AI across their organizations, combining technology deployment with workforce enablement. The partnership reflects how advisers are bundling adoption support with cloud and AI platforms for U.S. clients.
Change Management Consulting Market Segment Analysis
- By Service Type, strategy and planning segment dominated the Change Management Consulting Market in 2025 with 27.13% share; change analytics and measurement segment is the fastest-growing segment, with an estimated CAGR of 11.00% during 2026–2035.
- By Organization Size, large enterprises segment dominated the Change Management Consulting Market in 2025 with 60.86% share; small and medium enterprises segment is the fastest-growing segment, with an estimated CAGR of 9.90% during 2026–2035.
- By End-User Industry, BFSI segment dominated the Change Management Consulting Market in 2025 with an estimated 19.50% share; retail and e-commerce segment is the fastest-growing segment, with an estimated CAGR of 10.30% during 2026–2035.
- By Delivery Mode, hybrid segment dominated the Change Management Consulting Market in 2025 with 44.21% share; remote segment is the fastest-growing segment, with an estimated CAGR of 10.10% during 2026–2035.
By Service Type, Strategy and Planning Dominates Change Management Consulting Market; Change Analytics and Measurement to Register Fastest Growth.
Strategy and planning dominates the Change Management Consulting Market because organizations seek expert help at the start of transformation programs to assess readiness, map stakeholders, design roadmaps and establish governance. These engagements are high-value, often led by senior partners, and shape the scope of later training and communication work. Large firms win these assignments through reputation and frameworks, and early involvement makes it easier to sell follow-on adoption services. Standardized methodologies such as Prosci and Kotter frameworks are widely used in this phase, and clients value consistent tools across regions.
Change analytics and measurement is projected to register the fastest growth because executives want evidence that change efforts raise adoption and deliver return on investment. AI-based tools analyze survey data, system usage and sentiment to show where resistance is occurring, and consultancies are building dashboards that link adoption to business metrics. Organizational change, digital transformation and workforce training services continue to expand alongside, supported by large technology programs. Rising scrutiny of transformation failure rates is also increasing willingness to pay for measurement.
By Organization Size, Large Enterprises Dominate Change Management Consulting Market; Small and Medium Enterprises to Register Fastest Growth.
Large enterprises dominate the Change Management Consulting Market because they run complex, multi-year transformation programs involving thousands of employees, and they have the budget to hire leading advisory firms. Mergers, system replacements and cost restructuring generate recurring needs for stakeholder management and training. Many maintain internal change offices but still rely on external consultants for specialist methods, scale and an independent perspective. Their global footprints also require consultants who can coordinate programs across countries, languages and regulatory settings, which favors large networks.
Small and medium enterprises are projected to register the fastest growth as digitalization reaches smaller firms and as providers introduce packaged, shorter engagements and subscription-based platforms. Cloud software adoption, automation and workforce shifts create change needs for these companies, but limited budgets favor modular offerings. Remote delivery and digital learning tools make it economical for specialist boutiques to serve smaller clients across regions. Boutique firms and independent practitioners are partnering with software vendors to deliver change support alongside implementation projects at reasonable cost.
By End-User Industry, BFSI Dominates Change Management Consulting Market; Retail and E-commerce to Register Fastest Growth.
BFSI dominates the Change Management Consulting Market because banks and insurers undergo constant regulatory change, core system modernization and digital channel expansion, all of which require large-scale adoption by staff and customers. Mergers and cost programs add further work. The sector's tolerance for high advisory spending and its need for risk-aware governance of change make it a stable source of large engagements. IT and telecommunications is also a major contributor. Regulators in banking also expect evidence that new processes have been adopted and controls are working, which supports the need for structured change support and documentation of employee readiness.
Retail and e-commerce is projected to register the fastest growth because retailers are reorganizing around omnichannel operations, supply chain automation and data-driven merchandising, which changes roles and processes quickly. Healthcare, manufacturing and the public sector also drive demand, with hospitals adopting electronic records and factories implementing automation and sustainability programs. Each of these sectors needs support to bring frontline staff along as new technology is introduced. Public sector agencies use consultants for service redesign and digital government projects, and demand from these buyers is expected to remain supportive.
By Delivery Mode, Hybrid Dominates Change Management Consulting Market; Remote to Register Fastest Growth.
Hybrid delivery dominates the Change Management Consulting Market because it combines face-to-face leadership workshops with virtual training, surveys and coaching, which suits distributed workforces. Clients value the reduced travel cost and the ability to reach employees across sites without losing the personal contact that builds trust during change. Consultancies have invested in digital engagement platforms that support hybrid delivery at scale. Digital platforms for polls, learning and coaching also generate rich data that helps consultants adjust programs in real time.
Remote delivery is projected to register the fastest growth as video collaboration, learning platforms and analytics tools mature, allowing consultants to run entire programs without travel. Remote models lower cost and open the market to smaller clients and distant regions, while specialist boutiques can compete with global firms. Onsite delivery remains important for sensitive transformations, such as mergers and restructurings, where leadership presence strengthens credibility. Clients still use onsite sessions for critical milestones, so the distinction between delivery modes is increasingly blurred as firms mix tools to fit each project.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.00 |
|
Europe |
United Kingdom |
26.00 |
|
Asia Pacific |
China |
30.00 |
|
Latin America |
Brazil |
44.00 |
|
Middle East & Africa |
Saudi Arabia |
28.00 |
North America Change Management Consulting Market Insights
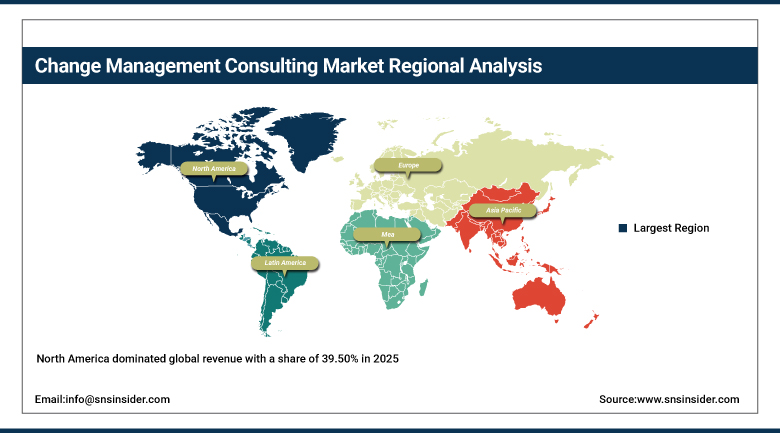
North America dominated global revenue with a share of 39.50% in 2025, supported by the highest concentration of large enterprises, strong investment in cloud and AI programs and the presence of firms such as Accenture, Deloitte, PwC, EY, McKinsey, Boston Consulting Group, Bain, Korn Ferry and Slalom. The United States accounts for largest share of regional demand, with Canada adding volume. Regional demand is expected to expand at a larger CAGR during 2026-2035. Canadian banks, utilities and public agencies add demand, and Mexican operations of multinational companies contribute to cross-border programs.
Corporate restructuring, mergers and technology adoption sustain steady demand, and clients increasingly expect measurable outcomes. In September 2025, Deloitte introduced enhanced AI-enabled workforce transformation services, and in November 2024 PwC and Microsoft announced a generative AI alliance. Maturity and economic caution moderate growth, but AI adoption and workforce reskilling continue to create new engagements. Clients also increasingly ask consultants to commit to outcome-based fees tied to adoption results, which is changing how engagements are structured and measured across large accounts.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Change Management Consulting Market Insights
Europe is the second-largest region. The United Kingdom, Germany and France lead, supported by firms such as Capgemini, PA Consulting, BearingPoint, Roland Berger and Mercer. Regulation, sustainability reporting and ESG-driven restructuring create demand for change programs, while public sector reform adds further projects. Nordic countries and the Netherlands are early adopters of agile and employee engagement approaches, and public bodies across the region commission change programs to modernize services. Spain and Italy also contribute.
Works council involvement and strong labor protections shape how change is managed in many countries, and clients seek advisers with local knowledge and language skills. In May 2025, Capgemini expanded its transformation consulting portfolio with AI-powered business change and workforce enablement solutions. Energy transition, banking consolidation and digitalization of manufacturing keep the pipeline strong. Cost sensitivity among mid-sized European clients encourages shorter, modular engagements, and boutique firms such as Sia Partners compete with global networks by offering specialist expertise at lower price points.
Asia Pacific Change Management Consulting Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 10.00% from 2026-2035. China, India, Japan, Australia and South Korea lead demand as companies digitize operations, expand globally and adopt modern management practices. Japan and South Korea add demand through engineering-led firms undertaking governance reform. Southeast Asian countries including Singapore, Indonesia and Vietnam contribute as regional headquarters and digital economies expand, and multinational firms use Singapore as a base for programs covering the region. Australia hosts mature advisers.
Rapid growth of technology, banking and retail sectors, together with foreign investment, creates large transformation programs, and local consultancies are expanding alongside global firms. Shortages of certified change practitioners in emerging markets limit capacity, so training partnerships and remote delivery are increasingly used. Cultural differences in managing change favor advisers who combine global methods with regional understanding. Governments in several countries also run public service digitization programs that require training and communication support, creating additional work for advisers with local presence.
MEA & Latin America Change Management Consulting Market Insights
In Latin America, Brazil leads on the strength of its large banking, retail and energy sectors, followed by Mexico, Chile and Colombia. Regional demand grows at faster pace annually, supported by digital transformation, privatization of services and multinational expansion. Local boutiques and global firms compete for projects in finance and telecommunications. Argentina and Peru add further demand, and multinational companies running regional shared-service centers commission programs that standardize processes and culture across markets. Peru and Colombia add steady work from mining and banking clients.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead through national transformation programs, government modernization and investment in new industries. Growth is supported by large public sector programs, although a limited supply of qualified practitioners and dependence on government spending cycles constrain the pace of expansion. Qatar and Kuwait also invest in public sector reform, while Nigeria and Kenya see demand from banks and telecom operators, though advisory budgets there remain small relative to the Gulf.
Market Dynamics
Growth Drivers: Digital and AI Transformation, Workforce Change and Measurable Outcomes
The major factor driving the Change Management Consulting Market is the digital and AI transformation projects. The new enterprise system and AI solutions can provide any benefit to the business only when people start using them. Therefore, businesses are allocating budgets to change management along with other technologies. The spread of generative AI is changing roles and skills, creating a need for communication, training and redesign of work. Investor pressure for faster realization of merger synergies also supports adoption of structured change methods. Rising complexity of regulatory change, such as new reporting and data rules, also increases demand for structured preparation of staff.
Hybrid work, mergers and restructuring add further demand, while sustainability and ESG requirements push companies to change operations and culture. AI-driven analytics that quantify adoption and return on investment make change work more credible to executives and help consultancies justify fees. Growing focus on employee experience and retention provides another reason for companies to invest in carefully managed transitions. Investment in employee upskilling programs also supports the use of structured change methods during rollout.
Restraints: Resistance, Practitioner Shortage and Budget Pressure
Resistance from the middle management layer and employees is an important obstacle because the process cannot be implemented without the sponsorship of those people. Complicated organizational structure makes the coordination of the programs difficult, and the outcomes cannot be attributed to any particular actions. This complicates the task of selling the program to the buyer because he may not want to invest money in something that does not yield clear results. The weariness of employees with the changes makes the program less effective and the need for consulting unneeded.
The lack of qualified individuals, especially in emerging markets, poses limits to the availability of resources and creates additional costs. Consulting services are an extra cost incurred, which is cut during tough economic times. Data privacy issues related to the usage of analytics tools create regulatory tasks. Other competing sources include transformation centers and software providers, as well as freelancers who are cheaply available. Uncertainty about outcomes also makes buyers cautious.
Opportunities: AI-Enabled Services, SMEs and Emerging Regions
AI-based change management services, like the ones Deloitte offers in workforce transformation services and Accenture provides through its generative AI services, make it possible for consultancies to provide more engagements per capita cost. The measuring platforms will result in recurring revenue streams through subscription fees. Providers who have advisory capabilities alongside the data platform capability can leverage the potential for recurring revenue and relationship building.
Small and medium enterprises and emerging regions are underserved, and packaged, remote offerings can reach them profitably. The learning management and people management software programs like HowNow and Leapsome incorporate AI functionality that would complement the consulting practice and enable partnerships as well. The partnerships with institutions of higher education and professional certification bodies could increase the number of practitioners available and thus resolve the issue of the lack of qualified personnel that restrains market growth. Corporate universities and learning management systems can reach out to everyone for free.
Recent Developments:
- 2026: Deloitte was named a Leader in IDC MarketScape’s Worldwide People, Organization, and Change Management Consulting Services assessment, highlighting its organizational transformation capabilities.
- 2026: EY introduced its Integrated Solutions portfolio, combining cross-functional expertise, AI platforms, and methodologies to help clients deliver enterprise transformation and adapt to changing business conditions.
- 2026: KPMG expanded its ServiceNow alliance to support HR transformation and AI-enabled employee services, with implementation, change-management, and optimization support for enterprise clients.
Change Management Consulting Market Key Players are:
- Accenture plc
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers International Limited
- Ernst & Young Global Limited
- KPMG International Limited
- McKinsey & Company, Inc.
- Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Oliver Wyman, Inc.
- Capgemini SE
- PA Consulting Group Limited
- BearingPoint Holding B.V.
- Roland Berger Holding GmbH
- Arthur D. Little International, Inc.
- AlixPartners, LLP
- Aon plc
- Korn Ferry
- Mercer LLC
- Slalom, LLC
- Protiviti Inc.
Change Management Consulting Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.15 Billion |
| Market Size by 2035 | USD 9.47 Billion |
| CAGR | CAGR of 8.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Strategy and Planning, Organizational Change, Digital Transformation, Workforce Change and Training, Change Analytics and Measurement, Others) • By Organization Size (Large Enterprises, Small and Medium Enterprises) • By End-User Industry (BFSI, IT and Telecommunications, Healthcare, Manufacturing, Energy and Utilities, Retail and E-commerce, Others) • By Delivery Mode (Onsite, Remote, Hybrid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Accenture plc, Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers International Limited, Ernst & Young Global Limited, KPMG International Limited, McKinsey & Company, Inc., Boston Consulting Group, Inc., Bain & Company, Inc., Oliver Wyman, Inc., Capgemini SE, PA Consulting Group Limited, BearingPoint Holding B.V., Roland Berger Holding GmbH, Arthur D. Little International, Inc., AlixPartners, LLP, Aon plc, Korn Ferry, Mercer LLC, Slalom, LLC, Protiviti Inc. |

Frequently Asked Questions
Key players include Accenture plc, Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers International Limited, Ernst & Young Global Limited, KPMG International Limited, McKinsey & Company, Inc., Boston Consulting Group, Inc. and Bain & Company, Inc.
Key opportunities include AI-enabled change services, change analytics, packaged offerings for small and medium enterprises and expansion in emerging regions.
The major growth factor is the spread of digital and AI transformation programs that require employee adoption to deliver value.
By Service Type, the Strategy and Planning segment dominated the market in 2025 with a 27.13% share, supported by demand for readiness assessment and roadmap design.
North America dominated the market with a share of 39.50% in 2025, driven by large enterprises, heavy technology investment and the presence of leading advisory firms.
