
Circular Packaging Market Report Scope & Overview:
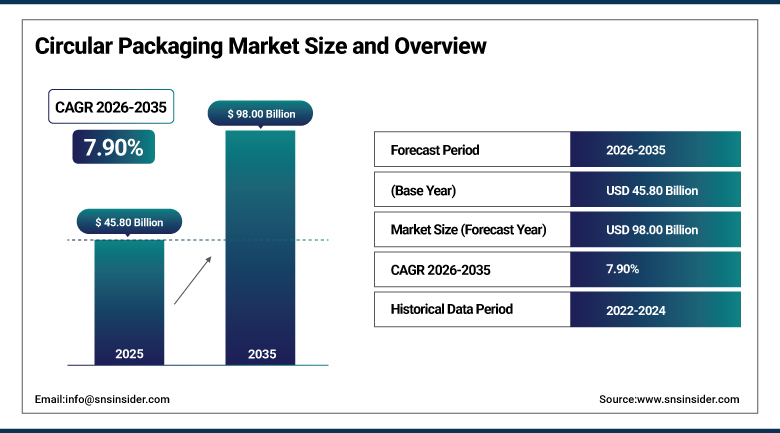
The Circular Packaging Market was valued at USD 45.80 Billion in 2025 and is expected to reach USD 98.00 Billion by 2035, growing at a CAGR of 7.90% from 2026 to 2035.
Circular Packaging Market is about designing, manufacturing, and implementing packaging systems that are either reusable, recyclable, or biodegradable in order to minimize waste and mitigate environmental damage, which marks a definite shift from the linear take-make-dispose system that has governed packaging practices during the majority of the past century. In doing so, this system becomes cyclical and helps in reducing dependence on raw materials while at the same time cutting down waste production, especially considering the fact that regulatory bodies and industry consortiums are working on creating harmonized standards that make recycling, reuse, and material tracing essential parts of package design. Manufacturing and consumer goods industries are leading the way when it comes to installation of these systems, which show impressive growth annually.
TOMRA Systems ASA strengthened its market position through continuous innovation in reverse vending machine technology and strategic partnerships with retailers, reinforcing automated return systems as a core piece of circular packaging infrastructure.
To Get more information Circular Packaging Market - Request Free Sample Report
Circular Packaging Market Trends
- Logistics applications are expanding fastest as companies implement reusable packaging systems to reduce costs and environmental impact.
- Automated return stations are gaining adoption as retailers deploy reverse vending infrastructure to support closed-loop recycling.
- Chemical recycling technology continues advancing as an emerging complement to established mechanical recycling processes.
- Harmonized sustainability standards across supply chains are becoming a regulatory and industry alliance priority.
- Recycled metal adoption is accelerating as aluminum circularity programs mature across food and beverage packaging.
The U.S. Circular Packaging Market Outlook
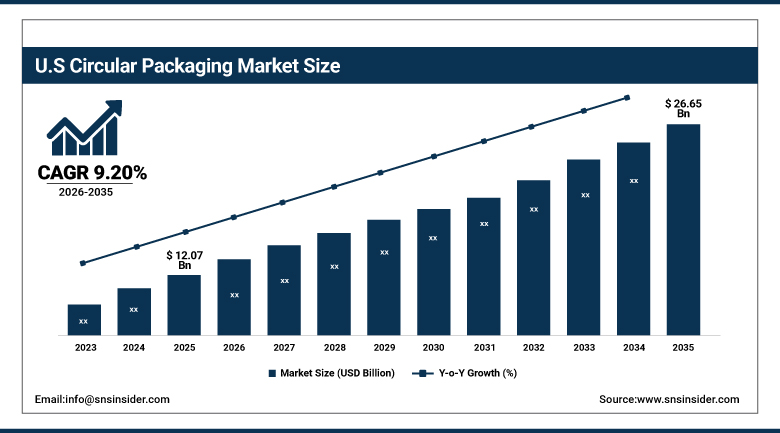
The U.S. Circular Packaging Market was valued at USD 12.07 Billion in 2025 and is projected to reach USD 26.65 Billion by 2035, growing at a CAGR of 9.20% during 2026-2035.
The U.S. holds the leading position in the North American regional market, owing to the rapid uptake of sustainable packaging options and a highly developed recycling system that includes both traditional and new chemical recycling channels. Effective regulation and high customer awareness of sustainability issues remain key factors for the continuation of such trends, with brands viewing circular packaging as an essential competitive advantage, and not just a sustainable option. High availability of packaging companies and developed recycling infrastructure at home continue driving demand, with return stations being set up at major retailers. Increasing regulatory pressure toward sustainability in packaging and growing demand among customers for green products drive demand in almost all categories of packaged goods.
In the United States, the Circular Packaging Return Stations market generated USD 0.43 billion in 2025, securing a 38.4% share of the global market, with the automated category accounting for the highest share within the station type segment.
Circular Packaging Market Segment Analysis
- By Material, the recycled plastics segment dominated the circular packaging market with approximately 35.0% share in 2025, while the recycled metal segment is the fastest growing with a CAGR of approximately 10.2%.
- By Application, the food & beverage segment dominated the circular packaging market with approximately 40.0% share in 2025, while the logistics segment is the fastest growing with a CAGR of approximately 11.9%.
- By Packaging Format, the rigid segment dominated the circular packaging market with approximately 44.0% share in 2025, while the reusable segment is the fastest growing with a CAGR of approximately 10.8%.
- By Recycling Process, the mechanical recycling segment dominated the circular packaging market with approximately 62.0% share in 2025, while the chemical recycling segment is the fastest growing with a CAGR of approximately 12.6%.
By Material, recycled plastics dominates the circular packaging market while recycled metal registers the fastest growth
Recycled Plastics dominated the circular packaging market due to the fact that established recycling infrastructure and mature reprocessing technology make recycled plastic resin the most economically accessible circular material across the widest range of packaging formats, from bottles to films to rigid containers. Decades of investment in plastic recycling collection and sorting systems continue reinforcing this material's dominant position.
Recycled Metal is the fastest-growing segment in the circular packaging market due to the fact that aluminum and steel packaging can be recycled indefinitely without meaningful quality degradation, giving brands a genuinely closed-loop material story that plastic recycling, with its quality loss over successive cycles, cannot fully match. Growing beverage industry investment in aluminum can circularity programs continues reinforcing this material's above-average growth trajectory.
By Application, food & beverage dominates the circular packaging market while logistics registers the fastest growth
Food & Beverage dominated the circular packaging market due to the fact that this category represents the largest single source of packaging volume globally, and consumer-facing food and beverage brands face the most direct, visible pressure from both regulators and shoppers to demonstrate credible circularity commitments. Established relationships between food and beverage manufacturers and circular packaging suppliers continue reinforcing this application's dominant position.
Logistics is the fastest-growing segment in the circular packaging market due to the fact that the increasing demand for efficient and sustainable packaging solutions in logistics is driving companies to implement reusable packaging systems that reduce both costs and environmental impact across increasingly complex supply chains. Growing e-commerce shipping volume continues reinforcing this application's above-average growth trajectory.
By Packaging Format, rigid dominates the circular packaging market while reusable registers the fastest growth
Rigid dominated the circular packaging market due to the fact that rigid formats have historically been easiest to collect, sort, and reprocess through established recycling infrastructure, giving this packaging format a genuine head start in circular material recovery compared to more complex flexible structures. Established manufacturing and recycling infrastructure built around rigid formats continues reinforcing this format's dominant position.
Reusable is the fastest-growing segment in the circular packaging market due to the fact that rising demand for biodegradable, flexible, and reusable solutions is pushing brands and logistics operators toward genuinely closed-loop reusable systems rather than single-use packaging that merely gets recycled after one use. Growing corporate sustainability commitments specifically targeting packaging reuse continue reinforcing this format's above-average growth trajectory.
By Recycling Process, mechanical recycling dominates the circular packaging market while chemical recycling registers the fastest growth
Mechanical Recycling dominated the circular packaging market due to the fact that this established process, physically sorting, cleaning, and reprocessing materials, remains far more cost-effective and widely deployed than newer recycling technologies at current commercial scale. Decades of infrastructure investment across municipal and industrial recycling systems continue reinforcing mechanical recycling's dominant position.
Chemical Recycling is the fastest-growing segment in the circular packaging market due to the fact that development of advanced recycling technologies increasingly addresses material streams, particularly mixed and contaminated plastics, that mechanical recycling cannot effectively process, expanding the overall share of packaging waste that can realistically be recovered. Growing investment from both packaging companies and chemical manufacturers continues reinforcing this process's above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
Germany |
29.80% |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
35.60% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
26.50% |
North America Circular Packaging Market Insights
North America is growing faster than any other region in this market, benefiting from strong regulatory frameworks and high consumer awareness regarding sustainability across the region. The presence of major packaging firms and a state-of-the-art recycling industry remains instrumental in propelling the region towards continued growth.
The U.S. is the dominant player in the region, owing to the use of sustainable packaging materials within the industry, accounting for 85.00% of the North American market. Canada makes up the other part, based on its own recycling industry and similar regulations.
Europe Circular Packaging Market Insights
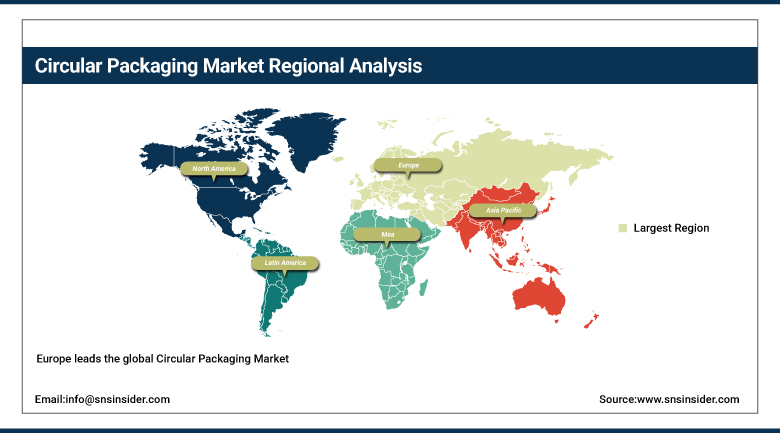
Europe leads the global Circular Packaging Market, with recycled materials, rigid formats, and primary packaging dominating the region's mature circular economy infrastructure. The continued strength in terms of regulatory framework for packaging waste and producer responsibility continues to solidify the regional leadership, facilitated by an established system of collection and recycling across member states.
Leadership will be maintained by Germany, with a 29.80% market share in 2025 and 2035 respectively, thanks to its superior environmental framework and history of recycling. Following Germany are France and the UK, whose demand is attributed to the regulatory framework on packaging waste and commitment to sustainability.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Circular Packaging Market Insights
Circular Packaging Market is projected to have significant growth prospects in Asia Pacific owing to the rising need for biodegradable, flexible and reusable packaging in the region’s flourishing manufacturing and consumer goods industry. Rising government initiatives towards sustainable packaging in key economies continue to drive regional demand.
China accounts for about 35.60% of the regional market owing to its large-scale manufacturing base as well as investments made in its recycling industry. India and Southeast Asian markets are witnessing fast growth due to environmental regulations in place while Japan and South Korea contribute owing to their advanced recycling industry.
Middle East & Africa and Latin America Circular Packaging Market Insights
The Middle East & Africa region is growing steadily as recycling infrastructure and modern retail both expand across the Gulf states, supported by rising government attention to sustainable packaging initiatives. Latin America follows a very similar trajectory, fueled by the growing packaging manufacturing industry in Brazil, as well as increased interests in adopting a circular economy in the region.
The UAE is at the top of the Middle East & Africa market share list with 17.20%, thanks to its status as the regional center for investment in sustainable packaging. Brazil constitutes 26.50% of the Latin America market share due to its strong packaging manufacturing presence.
Market Dynamics
Growth Drivers: Circular economy adoption and automation reshaping packaging specification
The increasing regulatory push for sustainable packaging and growing consumer preference for environmentally friendly products have emerged as the key factors responsible for driving the growth in this market, as more and more companies seek credibility on their sustainability pledges for staying in regulatory good books and keeping their consumers happy. Growing demand for sustainable and efficient packaging practices from the logistics industry is also supporting this trend, as companies adopt reusable packaging models to save costs and protect the environment.
Growing circular economy efforts and innovations in recycling technologies keep generating significant demand as well, as packaging companies work with technology providers to achieve circularity goals.
Restraints: Infrastructure gaps and material quality degradation limiting expansion
Recycling logistics is still quite unequal around the world, as there are well-advanced systems of collection and sorting in developed markets while many emerging markets lack capacities to implement them efficiently, limiting the actual reach of the advantages that can be achieved through the circular economy in packaging. Recycling can deteriorate the quality of materials, especially plastic, limiting the number of times they can be recycled without their properties becoming too degraded.
High implementation costs for advanced recycling technologies and reusable packaging infrastructure can create genuine barriers for smaller packaging companies and brand owners without the capital to invest at scale.
Opportunities: Advanced recycling technology and reusable system expansion creating new growth avenues
Development of advanced recycling technologies represents a significant growth opportunity, as chemical recycling and other emerging processes increasingly address material streams that mechanical recycling alone cannot effectively recover. Companies that can scale these technologies economically stand to capture meaningful share as regulatory and brand demand for circularity continues intensifying.
Expansion of reusable packaging systems, particularly automated return station infrastructure, offers a second clear opportunity, particularly as retailers and logistics operators increasingly recognize reuse as a genuine cost and sustainability advantage over single-use packaging that merely gets recycled.
Recent Developments:
- 2025: TOMRA Systems ASA strengthened its market position via continuous innovation in reverse vending machine technology and strategic partnerships with retailers across multiple regions.
- 2025: Loop Industries, Inc. continued advancing its proprietary depolymerization technology for converting waste PET plastic and polyester fiber into recycled materials suitable for food-grade packaging applications.
- 2025: ecoSPIRITS expanded its reusable packaging and refill infrastructure for the global spirits industry, targeting reduced glass bottle waste across bars and hospitality venues.
- 2025: IFCO Systems continued expanding its reusable packaging container network across grocery and fresh food supply chains in multiple regions.
Circular Packaging Market key players are:
- Amcor plc
- Smurfit Westrock plc
- Mondi Group
- Sonoco Products Company
- Sealed Air Corporation
- International Paper Company
- Stora Enso Oyj
- ecoSPIRITS
- Loop Industries, Inc.
- Ball Corporation
- Tetra Pak International S.A.
- Huhtamaki Oyj
- Reynolds Group Holdings Limited
- Coveris Holdings S.A.
- Crown Holdings, Inc.
- Greif, Inc.
- ALPLA Werke Alwin Lehner GmbH & Co. KG
- LyondellBasell Industries N.V.
- TOMRA Systems ASA
- IFCO Systems
Circular Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 45.80 Billion |
| Market Size by 2035 | USD 98.00 Billion |
| CAGR | CAGR of 7.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Recycled Plastics, Recycled Paper & Cardboard, Recycled Glass, Recycled Metal, Others) • By Application (Food & Beverage, Personal Care & Cosmetics, E-commerce, Logistics, Healthcare & Pharmaceuticals, Others) • By Packaging Format (Rigid, Flexible, Semi-Rigid, Reusable) • By Recycling Process (Mechanical Recycling, Chemical Recycling, Reuse Systems, Composting / Biological Recycling, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Smurfit Westrock plc, Mondi Group, Sonoco Products Company, Sealed Air Corporation, International Paper Company, Stora Enso Oyj, ecoSPIRITS, Loop Industries, Inc., Ball Corporation, Tetra Pak International S.A., Huhtamaki Oyj, Reynolds Group Holdings Limited, Coveris Holdings S.A., Crown Holdings, Inc., Greif, Inc., ALPLA Werke Alwin Lehner GmbH & Co. KG, LyondellBasell Industries N.V., TOMRA Systems ASA, IFCO Systems |
Frequently Asked Questions
Key players include Amcor plc, Smurfit Westrock plc, Mondi Group, Sonoco Products Company, and TOMRA Systems ASA, alongside other established circular packaging and recycling technology providers.
Key opportunities include development of advanced recycling technologies addressing previously unrecoverable material streams, expansion of reusable packaging and automated return station infrastructure, and growing chemical recycling capacity.
The market is driven by increasing regulatory pressure for sustainable packaging, rising consumer demand for eco-friendly products, and growing demand for efficient reusable packaging solutions in logistics.
The Recycled Plastics segment dominated the Circular Packaging Market in 2025.
The Europe region dominated the Circular Packaging Market in 2025, led by Germany's advanced environmental infrastructure and recycling culture.
