
Clamshell Packaging Market Report Scope & Overview:
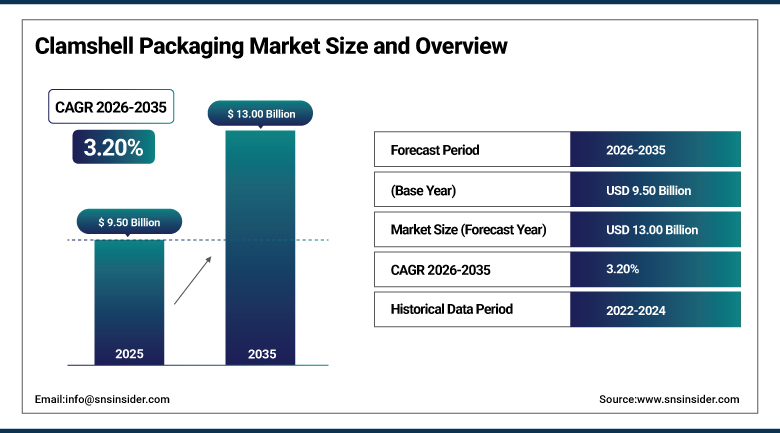
The Clamshell Packaging Market was valued at USD 9.50 Billion in 2025 and is expected to reach USD 13.00 Billion by 2035, growing at a CAGR of 3.20% from 2026–2035.
Clamshell packaging is the hinged, transparent container that lets a shopper see exactly what they're buying, berries, a rotisserie chicken, a phone charger, before it ever leaves the shelf, while still keeping the product sealed and tamper-evident. Its rigid, see-through structure has made it a default choice wherever retailers need product visibility and security to matter equally, from grocery produce sections to big-box electronics aisles. The category's biggest tension right now is between two things retailers and regulators both want at once: keeping the transparency and protection that make clamshells useful, while cutting the virgin plastic content that makes them a recycling headache.
Placon, a Madison, Wisconsin-based thermoforming company celebrating its 60th year in business, shifted its entire stock food and retail PET product line to EcoStar 50S, a recycled-content material meeting current packaging requirements in all 50 U.S. states, starting in late 2024. That's a genuinely unusual manufacturing decision, building to the strictest state's recycled-content threshold rather than customizing formulations state by state, and it reflects how quickly post-consumer recycled content rules are spreading beyond the handful of states that first adopted them.
To Get more information Clamshell Packaging Market - Request Free Sample Report
Clamshell Packaging Market Trends
-
Post-consumer recycled PET content is becoming a baseline expectation rather than a premium feature, driven by a growing number of U.S. states enacting recycled-content legislation for plastic packaging.
-
Tamper-evident features continue expanding beyond pharmaceuticals and specialty food into mainstream deli, bakery, and produce clamshells as retailers respond to product safety and shoplifting concerns simultaneously.
-
E-commerce shipping requirements continue reshaping clamshell design, pushing manufacturers toward formats that survive parcel handling and reduce void-fill packaging waste alongside their traditional retail display function.
-
Fiber-based and paperboard alternatives are emerging as genuine competitors to plastic clamshells in select applications, particularly food-to-go formats where full transparency isn't strictly required.
-
Manufacturers continue investing in in-house recycling and extrusion capacity, letting them prove genuine closed-loop post-consumer content to sustainability-focused retail and food service customers.
U.S. Clamshell Packaging Market Outlook
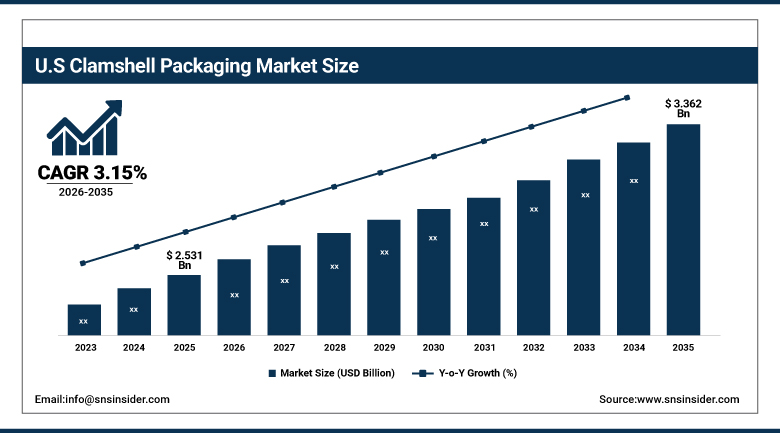
The U.S. Clamshell Packaging Market was valued at approximately USD 2.531 Billion in 2025 and is expected to reach approximately USD 3.362 Billion by 2035, growing at a CAGR of approximately 3.15%.
Demand in the United States is anchored by a large grocery retail and food service industry that relies heavily on clamshell formats for produce, deli, and bakery display, alongside meaningful consumer electronics and pharmaceutical packaging applications. A growing patchwork of state-level post-consumer recycled content legislation continues reshaping material sourcing requirements, pushing domestic manufacturers to secure reliable recycled PET supply well ahead of expanding compliance deadlines. Established American thermoforming companies with in-house recycling capability are increasingly positioned to compete on genuine sustainability credentials rather than price alone.
Genpak, a U.S. packaging manufacturer, built post-consumer recycled content directly into its Precision Hinged Deli clamshell line, committing to roughly 14 million pounds of post-consumer resin annually for its APET products. That volume commitment, made by a single mid-sized clamshell manufacturer for a single product line, gives a sense of just how much recycled plastic the broader U.S. clamshell packaging industry now needs to source reliably to keep pace with expanding state-level extended producer responsibility requirements.
Clamshell Packaging Market Segment Analysis
-
By Material Type, the Plastic segment dominated the Clamshell Packaging Market with approximately 52.40% share in 2025, while the Paperboard segment is the fastest growing with a CAGR of approximately 6.60%.
-
By Packaging Type, the Trays segment dominated the Clamshell Packaging Market with approximately 36.80% share in 2025, while the Box segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Product Type, the 2-Piece Clamshells segment dominated the Clamshell Packaging Market with approximately 41.70% share in 2025, while the 1-Piece/Hinged Clamshells segment is the fastest growing with a CAGR of approximately 5.40%.
-
By End-Use Industry, the Food segment dominated the Clamshell Packaging Market with approximately 62.80% share in 2025, while the Pharmaceuticals segment is the fastest growing with a CAGR of approximately 6.90%.
-
By Distribution Channel, the Direct/B2B Supply segment dominated the Clamshell Packaging Market with approximately 54.60% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 7.40%.
By Material Type, plastic dominates, paperboard grows fastest
Plastic held the majority share of the material-type segment in 2025, chosen overwhelmingly for its transparency, structural rigidity, and moisture resistance across PET, PP, and PS formulations that all serve slightly different clamshell applications. That combination of clarity and durability keeps plastic the default material wherever a retailer needs a shopper to see the product clearly while trusting it hasn't been tampered with in transit.
Paperboard is growing fastest as fiber-based alternatives gain traction in food-to-go and select retail applications where full product transparency isn't strictly required. Growing regulatory push for recyclable content, combined with genuine advances in structural paperboard engineering, is pulling this material category's growth well ahead of the broader, plastic-dominated clamshell market as brand owners seek credible sustainability alternatives.
By Packaging Type, trays dominates, box grows fastest
Trays held the largest share of the packaging-type segment in 2025, widely used across produce, meat, and bakery display applications where a flat, stable base and clear top combine to maximize shelf visibility. Their compatibility with high-speed automated filling and sealing equipment across grocery retail supply chains keeps trays the dominant packaging-type format across the broader clamshell category.
Box-format clamshells are growing fastest as e-commerce shipping requirements push manufacturers toward more structurally protective formats capable of surviving parcel handling and transit stress that traditional flat trays weren't designed for. Rising direct-to-consumer shipping of consumer electronics and specialty food products is reinforcing this above-average growth trajectory relative to the broader, retail-display-oriented packaging-type mix.
By Product Type, 2-piece clamshells dominates, 1-piece/hinged grows fastest
Two-piece clamshells held the largest share of the product-type segment in 2025, favored for the added structural strength and design flexibility that separate top and bottom components offer relative to single-molded alternatives. That construction approach lets manufacturers optimize each half independently for its specific function, whether that's a rigid base for stability or a clear lid for visibility.
One-piece and hinged clamshells are growing fastest as their simpler, single-mold construction offers lower per-unit manufacturing cost and faster production cycle times relative to two-piece assemblies. Rising cost pressure across the broader packaging industry, combined with continued thermoforming technology improvements that narrow the structural gap with two-piece designs, is reinforcing this above-average growth trajectory.
By End-Use Industry, food dominates, pharmaceuticals grows fastest
Food accounted for the overwhelming majority of the end-use segment in 2025, broadly used to store, transport, and display produce, bakery items, deli products, and prepared meals across both retail and food service channels. Food service and restaurants' widespread use of clamshells for takeout meals, combined with grocery retail's reliance on the format for fresh produce, keeps food the dominant end-use industry by a wide margin.
Pharmaceuticals is the fastest-growing end-use industry as tamper-evident, precisely molded clamshell packaging increasingly serves medical device and over-the-counter product applications requiring both product security and regulatory compliance. Rising global healthcare spending and expanding medical device manufacturing capacity continue reinforcing this above-average growth trajectory relative to the broader, food-dominated clamshell market.
By Distribution Channel, direct/B2B supply dominates, online retail grows fastest
Direct and B2B supply constituted the highest percentage in 2025 due to the way in which clamshell packaging volumes are generally distributed through negotiated contracts between the manufacturing firms and retail stores, restaurants, and consumer products companies instead of open retail sales. Such channels often operate with standard ordering practices within the larger context of a retail supply chain relationship.
E-retail sales constitute the fastest growing category, where smaller food service firms, specialty retailers, and consumer brands order clamshell packaging via the internet industrial supply websites, as opposed to direct manufacturer negotiations. Such a trend is common among small firms that cannot order clamshell packaging at advantageous terms under direct supply contracts.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.35% |
|
Europe |
Germany |
24.60% |
|
Asia Pacific |
India |
33.75% |
|
Latin America |
Brazil |
35.90% |
|
Middle East & Africa |
UAE |
28.20% |
North America Clamshell Packaging Market Insights
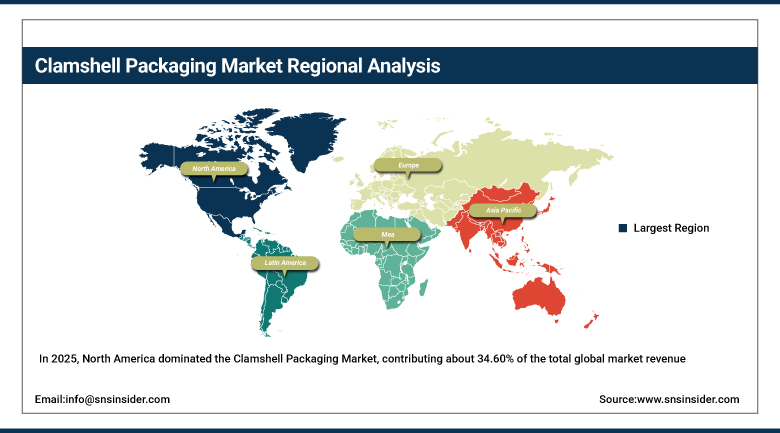
In 2025, North America dominated the Clamshell Packaging Market, contributing about 34.60% of the total global market revenue due to its well-developed grocery retail and foodservice industry, which is a big user of clamshell packages for the display of produce, deli products, and bakery items. The United States drives this dominance, which has a strong presence of existing thermoforming manufacturers and increasing capacity for recycling.
Canada adds its own contribution through its grocery retail and food processing industry, while the market in Mexico keeps growing along with growing investments in manufacturing operations driven by nearshoring. Supply links cross borders, with major manufacturers serving all three markets from a common supply chain.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Clamshell Packaging Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, with India specifically identified as the fastest-growing individual country at a CAGR of approximately 6.10%, driven by rapid expansion of organized retail, food service, and e-commerce distribution. Rising urbanization and growing packaged food consumption across the region's largest and fastest-growing economies continue reinforcing this accelerating growth trajectory.
China's large-scale food processing and consumer electronics manufacturing sectors give the region substantial baseline demand, while India's rapidly expanding organized retail and food delivery sectors are drawing significant new investment in clamshell packaging capacity. Japan and South Korea represent more mature, quality-focused markets, while Southeast Asian markets continue following a similar urbanization-driven growth trajectory.
Europe Clamshell Packaging Market Insights
Europe is characterized as a developed market that is highly regulated in terms of clamshell packaging. This region has been influenced by EU directives concerning waste from packaging and recycling needs. The main driver of demand in this region is Germany, which has a considerable number of food processing and retail businesses and also some big thermoforming producers working on developing materials for recycled content.
The contribution of France, Italy, and the UK is also significant as these regions have large grocery retailing and food service businesses complying with the increasing demands from the EU for sustainability.
MEA & Latin America Clamshell Packaging Market Insights
The Middle East and Africa represent a smaller but developing clamshell packaging market, with the UAE driving demand through growing organized retail and food service investment tied to broader economic diversification and tourism-driven consumption goals. Growth elsewhere in the region remains tied closely to the pace of broader retail and food processing infrastructure development.
Latin America is a growing market led by Brazil, where expanding organized retail and food processing sectors continue driving demand for transparent, protective clamshell packaging. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing grocery retail and consumer goods manufacturing sectors.
Market Dynamics
Growth Drivers: Retail visibility demand and food safety requirements fueling adoption
Rising focus on product safety and consumer convenience is one of the clearest forces behind rising clamshell packaging demand, as retailers and brand owners alike prioritize packaging formats that let shoppers see and trust a product before purchase. That combination of transparency and tamper-evidence has become a genuinely difficult standard for alternative packaging formats to match at comparable cost.
Expanding e-commerce and organized retail penetration adds a second major driver, as growing online and modern retail channels across both developed and emerging markets continue driving demand for protective, shelf-ready packaging formats. Rising consumer expectations around product visibility and shelf life, particularly for perishable goods, continue reinforcing this demand base across grocery and food service channels worldwide.
Restraints: Recycling infrastructure gaps and raw material cost volatility limiting broader adoption
Limited recycling infrastructure for rigid plastic clamshells remains a genuine restraint in many markets, since the material's specific plastic grade and clarity requirements make conventional mechanical recycling more complex than for simpler plastic packaging formats. That infrastructure gap limits how quickly genuine circularity can scale even as manufacturers invest heavily in post-consumer recycled content sourcing.
Fluctuating PET and other plastic resin prices add a further restraint, since clamshell manufacturers remain exposed to broader petrochemical commodity market swings that directly affect production costs and, ultimately, project budgets for retail and food service customers. Manufacturers without long-term resin supply contracts are particularly exposed to these swings, which can compress margins even when finished-packaging demand remains steady.
Opportunities: Recycled content sourcing and e-commerce format innovation opening new growth avenues
Scaling post-consumer recycled content sourcing and in-house recycling capability offers manufacturers a genuine path to capturing premium business from retail and food service customers chasing credible sustainability commitments ahead of tightening state and national packaging regulation. Companies that build strong recycled-content supply chains are positioned to capture a growing share of business from environmentally conscious brand owners.
E-commerce-optimized clamshell format innovation represents a second significant opportunity, as manufacturers develop shipping-durable designs that reduce void-fill waste while maintaining the transparency and tamper-evidence that make clamshells useful in the first place. Companies that build genuine e-commerce packaging design expertise are positioned to capture disproportionate growth as direct-to-consumer shipping continues expanding across consumer electronics and specialty food categories.
Recent Developments:
-
2025: Five U.S. states enacted post-consumer recycled content legislation for plastic packaging, with several additional states introducing similar bills, directly affecting clamshell manufacturers' material sourcing requirements.
-
August 2025: Placon received a 2025 AmeriStar award for design excellence in sustainable thermoformed food packaging.
-
February 2025: ProAmpac showcased fiber-based, recyclable food-to-go packaging solutions at Packaging Innovations 2025 in Birmingham, UK, including products aimed at replacing traditional plastic clamshell formats.
-
2025: Multiple clamshell manufacturers continued expanding tamper-evident, minimum-25%-PCR-content product lines across deli, bakery, and produce packaging categories.
Clamshell Packaging Market Key Players
-
VisiPak Inc.
-
Novolex Holdings LLC
-
Action Pak Inc.
-
Panic Plastics Inc.
-
Lacerta Group Inc.
-
Brentwood Medical
-
Placon Corporation
-
Genpak, LLC
-
Inline Plastics Corp.
-
Dordan Manufacturing Co.
-
Sonoco Products Company
-
Amcor plc
-
Berry Global Inc.
-
Sealed Air Corporation
-
Pactiv Evergreen Inc.
-
Display Pack, Inc.
-
Fabri-Kal Corporation
-
Sabert Corporation
-
Clear Lam Packaging, Inc.
-
WNA (a Novolex Company)
Clamshell Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.50 Billion |
| Market Size by 2035 | USD 13.00 Billion |
| CAGR | CAGR of 3.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Plastic (PET, PP, PS), Paperboard, Others) • by Packaging Type (Trays, Hinged Lid, Box, Others) • by Product Type (2-Piece Clamshells, 1-Piece/Hinged Clamshells, Others) • by End-Use Industry (Food, Personal Care, Electrical & Electronics, Pharmaceuticals, Others) • by Distribution Channel (Direct/B2B Supply, Retail, Online Retail) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | VisiPak Inc., Novolex Holdings LLC, Action Pak Inc., Panic Plastics Inc., Lacerta Group Inc., Brentwood Medical, Placon Corporation, Genpak, LLC, Inline Plastics Corp., Dordan Manufacturing Co., Sonoco Products Company, Amcor plc, Berry Global Inc., Sealed Air Corporation, Pactiv Evergreen Inc., Display Pack, Inc., Fabri-Kal Corporation, Sabert Corporation, Clear Lam Packaging, Inc., WNA (a Novolex Company) |
Frequently Asked Questions
Key players in the Clamshell Packaging Market include VisiPak Inc., Novolex Holdings LLC, Placon Corporation, Genpak, LLC, and Inline Plastics Corp., among others.
Key opportunities in the Clamshell Packaging Market include scaling post-consumer recycled content sourcing and in-house recycling capability and developing e-commerce-optimized clamshell formats that reduce void-fill waste.
The market is driven by rising focus on product safety and consumer convenience, combined with expanding e-commerce and organized retail penetration worldwide.
The Food segment dominated the Clamshell Packaging Market, accounting for approximately 62.80% market share.
The North America region dominated the Clamshell Packaging Market in 2025 with approximately 34.60% share, driven by a large, mature grocery retail and food service industry.
