
Corrugated Packaging Market Report Scope & Overview:
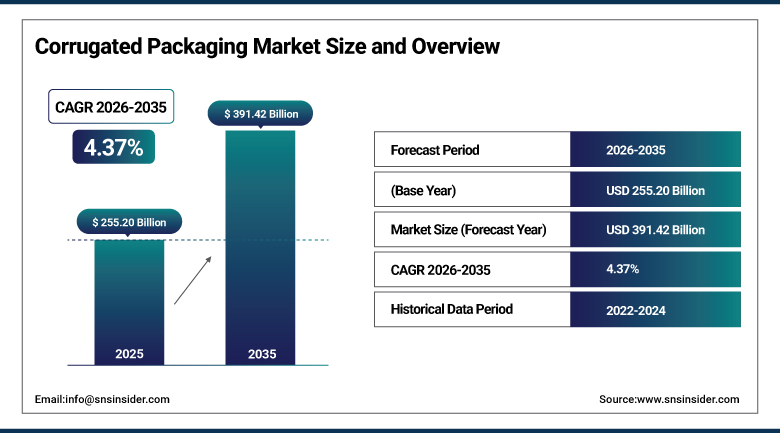
The Corrugated Packaging Market was valued at USD 255.20 Billion in 2025 and is expected to reach USD 391.42 Billion by 2035, growing at a CAGR of 4.37% from 2026-2035.
The market growth for Corrugated Packaging is driven mainly by the rapid growth of e-commerce industry along with the increase in packaging needs for last mile delivery because of the significant importance of corrugated boxes as an effective tool in secondary and tertiary packaging in more sophisticated supply chain management of retail and logistics. Corrugated packaging involves the creation of a lightweight but durable structure through layers of fluted paperboard placed between linerboards that provides protection to products while shipping and storage as well as ensures full recyclability of this type of packaging making it a preferable solution in case of more regulations concerning the environment and sustainability issues within corporations. The preference of consumers to recyclable packaging solutions together with growing trend towards lightweight boxes that minimize cost of shipment is the reason for keeping a competitive advantage over other packaging formats.
On January 31, 2025, International Paper completed its acquisition of DS Smith Plc in an all-share transaction valued at approximately USD 9.9 billion, forming one of the world's largest sustainable packaging companies with operations across Europe and North America generating approximately 90% of revenue from sustainable fiber-based packaging. The transaction reflects the continued wave of multibillion-dollar consolidation reshaping the global corrugated packaging industry, following Smurfit Kappa's combination with WestRock in 2024, and reinforces the competitive position of scale players pursuing integrated manufacturing footprints and expanded fiber-based packaging capability across major global markets.
To Get more information Corrugated Packaging Market - Request Free Sample Report
Corrugated Packaging Market Trends
-
Rising demand for lightweight, right-sized corrugated box designs that reduce shipping costs and material usage.
-
Growing adoption of digital printing technology enabling shorter print runs and enhanced retail-ready branding.
-
Expanding use of recycled and mixed-fiber materials to meet corporate sustainability and packaging waste regulation targets.
-
Increasing automation and AI-driven design optimization within corrugated box manufacturing operations.
-
Rising consolidation among global packaging suppliers through large-scale mergers and acquisitions.
-
Growing demand for e-commerce-optimized packaging designed to improve unboxing experience and reduce void fill.
U.S. Corrugated Packaging Market Outlook
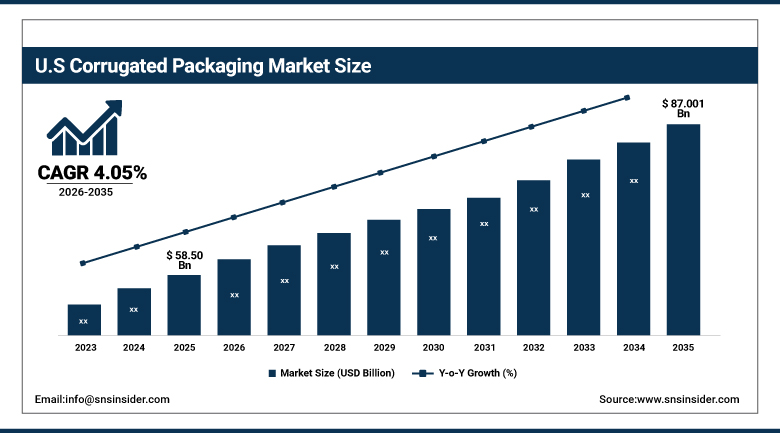
The U.S. Corrugated Packaging Market was valued at USD 58.50 Billion in 2025 and is expected to reach USD 87.001 Billion by 2035, growing at a CAGR of 4.05% from 2026-2035.
The U.S. Corrugated Packaging Market growth is being further reinforced by robust demand from the e-commerce, food & beverages, and consumer goods sectors, owing to the prominent use of corrugated boxes in secondary and tertiary packaging via the technologically advanced and mature distribution network in the U.S. country. The high rate of automation in the domestic manufacturing process coupled with warehouse-ready packaging and standard boxes continues to drive efficiency gains and scalability. Increasing consumer demands for sustainable packaging are helping the corrugated packaging to remain highly competitive against plastic alternative options. Growth in the market will be driven by investments made in domestic capacities by leading packaging companies to rationalize their manufacturing footprint post-industry consolidation.
Smurfit Westrock, formed through the 2024 combination of Smurfit Kappa and WestRock, announced plans to invest approximately USD 19.3 million in its Saltillo, Mississippi operation over the following year to expand production of corrugated cases, boxes, and trays. The investment illustrates how major packaging suppliers continue to selectively expand domestic manufacturing capacity even while rationalizing less efficient facilities elsewhere in their networks, reflecting the broader industry pattern of post-merger capacity optimization following a decade of sustained consolidation across the corrugated packaging sector.
Corrugated Packaging Market Segment Analysis
-
By Product Type, the Slotted Boxes segment dominated the Corrugated Packaging Market with approximately 36.60% share in 2025, while the Die-Cut Boxes segment is the fastest growing with a CAGR of approximately 6.40%.
-
By Material, the Recycled Fiber segment dominated the Corrugated Packaging Market with approximately 52.60% share in 2025, while the Mixed Fiber segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Wall Construction, the Single Wall segment dominated the Corrugated Packaging Market with approximately 71.40% share in 2025, while the Double Wall segment is the fastest growing with a CAGR of approximately 6.20%.
-
By End-Use, the Food & Beverage segment dominated the Corrugated Packaging Market with approximately 28.60% share in 2025, while the E-Commerce & Logistics segment is the fastest growing with a CAGR of approximately 8.80%.
By Product Type, Slotted Boxes Dominates the Corrugated Packaging Market and Die-Cut Boxes Grows Fastest
Slotted boxes dominate the market because their simple, cost-effective construction offers a favorable balance of strength, material efficiency, and manufacturing speed that has made them the default specification across the large majority of shipping, storage, and general-purpose packaging applications. Their compatibility with high-speed automated manufacturing and folding equipment continues to reinforce slotted boxes' position as the largest product type category across food and beverage, industrial, and e-commerce shipping applications.
Die-cut boxes are the fastest-growing product type as retailers and brands increasingly specify custom-shaped, precision-cut packaging designs that enhance shelf presentation, unboxing experience, and product protection for specialty and premium goods. This growth is reinforced by rising e-commerce brand investment in differentiated packaging design, as direct-to-consumer companies increasingly treat packaging as a marketing and customer experience touchpoint rather than a purely functional shipping container.
By Material, Recycled Fiber Dominates the Corrugated Packaging Market and Mixed Fiber Grows Fastest
Recycled fibers have dominated the market due to the existing recycling facilities for corrugated packaging as well as the closed-loop fiber recovery systems which still make sure that the recycled fiber content is maintained in most of the worldwide production of corrugated paper. Corporate sustainability goals and the packaging regulations continue to favor recycled fibers as a choice of material for standard shipping and general packaging applications, where extra strength provided by virgin fibers is not necessary.
Mixed fiber-based materials have been growing rapidly among all material types as companies continue to combine virgin and recycled fiber contents in order to find an optimal balance between strength, price and sustainability for specialized packaging applications such as heavy industrial and multi-cycle reusable shipping containers.
By Wall Construction, Single Wall Dominates the Corrugated Packaging Market and Double Wall Grows Fastest
Single wall corrugated board dominates the market due to its optimal balance between strength, cost efficiency, and material usage, making it the default specification across the large majority of general-purpose shipping and retail packaging applications. Its established manufacturing processes and broad compatibility with standard automated packing equipment continue to sustain single wall's position as the largest wall construction category across global corrugated packaging production.
Double wall corrugated board is the fastest-growing wall construction category as e-commerce shipping and heavy-duty industrial applications increasingly require enhanced puncture resistance and stacking strength beyond what single wall construction can reliably provide. This growth is reinforced by rising e-commerce shipment volumes, where double wall construction's superior protection reduces product damage and associated return costs for higher-value or fragile shipped goods.
By End-Use, Food & Beverage Dominates the Corrugated Packaging Market and E-Commerce & Logistics Grows Fastest
The use of corrugated packaging is prevalent in the food and beverages industry due to the sector’s requirement for a packaging material that is not only strong but also environmentally sustainable to protect the goods during the distribution process within complicated cold chain and ambient distribution chains. The size of the market and its stable demand cycle help ensure that food and beverages remains the largest end-use application of corrugated packaging worldwide.
E-commerce and logistics remain the fastest growing end-use application owing to the rapidly rising popularity of online shopping not only in the developed nations but also in the developing nations, thus, increasing the demand for packaging that not only protects but enhances the unboxing experience of the consumer. This trend remains supported by the growing penetration of e-commerce in underdeveloped economies.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.60% |
|
Europe |
Germany |
28.60% |
|
North America |
United States |
86.60% |
|
Latin America |
Brazil |
29.80% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Corrugated Packaging Market Insights
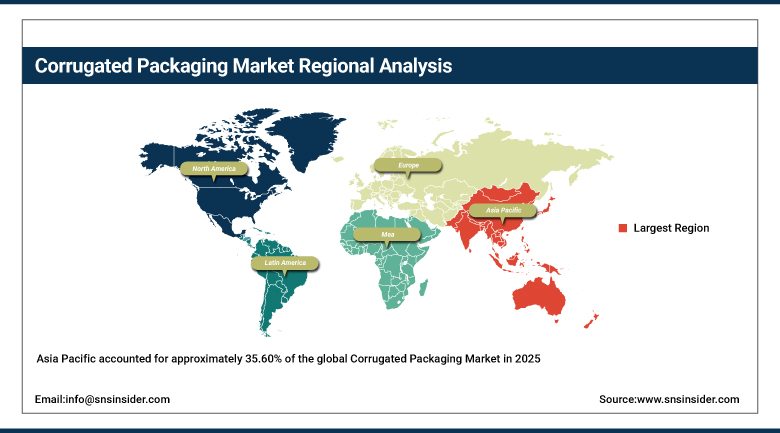
Asia Pacific accounted for approximately 35.60% of the global Corrugated Packaging Market in 2025, making it the largest regional market, driven mainly by China and India's manufacturing scale and rapidly expanding e-commerce ecosystems. China's mature manufacturing base and rising e-commerce ecosystem continue to serve as significant contributors to regional demand, while rapid industrialization and increasing consumer demand across the broader region sustain Asia Pacific's leading market position.
India's corrugated packaging market is expected to grow at a CAGR exceeding 7% through the forecast period, reflecting the country's rapidly expanding e-commerce and organized retail sectors. Japan and South Korea contribute additional scale through established food and beverage and electronics manufacturing sectors. This combination of manufacturing scale and e-commerce growth is expected to sustain Asia Pacific's position as the largest market through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Corrugated Packaging Market Insights
North America is the fastest growing market, which will grow at a CAGR of around 5.40% from 2026 to 2035, and the U.S. is considered one of the most mature and technologically advanced markets for corrugated packaging in the world. The strong demand is attributed to e-commerce, food & beverages, and consumer goods industries where corrugated boxes find their application in secondary and tertiary packaging solutions.
The high level of automation in manufacturing processes, as well as warehouse-ready design solutions for corrugated packaging, is still a factor supporting efficiency and scalability in the region. Canada and Mexico bring additional growth potential for the region's supply chain as they increasingly incorporate corrugated packaging manufacturing capabilities into the regional supply chains.
Europe Corrugated Packaging Market Insights
Europe represents a significant share of the global Corrugated Packaging Market, anchored by Germany's large food and beverage and industrial manufacturing base alongside the region's stringent packaging waste and recyclability regulation. European packaging suppliers continue to lead in developing renewable, fully recyclable corrugated formats in response to the European Union's packaging waste directives and broader circular economy initiatives.
France, the United Kingdom, and Italy are contributing steady demand growth as regional brands extend sustainable corrugated packaging adoption from premium segments into broader mass-market applications. Regional consolidation among major packaging suppliers, including recent large-scale mergers and acquisitions, continues to reshape the competitive landscape across the region's corrugated packaging manufacturing base.
MEA & Latin America Corrugated Packaging Market Insights
The Middle East & Africa market continues to remain relatively small, but continues to grow due to increasing investments in the food and beverages industry and increasing use of e-commerce platforms within the UAE and Saudi Arabia, which drive demand for corrugated packaging. Manufacturing capacity in the region continues to increase to cater to increasing local consumption, due to the economic benefits of regional manufacturing of such bulk, low value products compared to shipping costs.
The Latin American market is driven by Brazil, which continues to have high demand for corrugated packaging due to its large domestic manufacturing capacity of food and beverages industry. Mexico continues to be a major contributor in the region to growth due to increasing nearshoring and investment in regional manufacturing capacity to cater to North American supply chain needs.
Market Dynamics
Growth Drivers: E-Commerce Expansion and Sustainability Regulation Fuel Market Expansion
Rapid e-commerce expansion and rising last-mile delivery packaging demand represent the primary driver of Corrugated Packaging Market growth, as corrugated boxes continue to serve as the preferred packaging format for online retail shipping given their combination of strength, lightweight structure, and cost efficiency. Rising online shopping adoption across developing and underdeveloped economies continues to extend this demand into previously underserved markets, reinforcing corrugated packaging's structural growth trajectory independent of broader economic cycles.
Environmental regulations, as well as increased sustainability efforts from corporations, act as a second significant factor driving growth in the industry since manufacturers and retailers are beginning to move away from traditional plastic packaging and instead embrace sustainable and recyclable fiber-based solutions. The recyclability and durability of corrugated solutions help position the segment in a favorable light in light of stricter regulations of packaging waste in key global markets.
Restraints: Raw Material Cost Volatility and Post-Merger Capacity Rationalization Hampers the Market Growth
Volatility in the cost of raw materials, especially recycled and virgin paper fiber, is another significant constraint on growth in the market, since manufacturers have to deal with competition and cost volatility related to global pulp and paper commodities markets in their price negotiations with customers. Fuel and material costs, together with shipping disruptions, put pressure on margins in the corrugated packaging supply chain.
Facility rationalization driven by recent mergers and acquisitions is another constraint. Major manufacturers have been closing plants that are inefficient or unnecessary due to the synergy of mergers in order to capitalize on the cost savings, thus creating temporary constraint of capacity regionally, even though capacity in the industry overall is sufficient. It is the consolidation-driven facility rationalization, driven by redundancy of facilities after years of mergers and acquisitions in the global corrugated packaging industry.
Opportunities: Digital Printing Innovation and E-Commerce-Optimized Design Create Lucrative Opportunities
Adoption of digital printing technology presents a significant potential, with suppliers that are able to provide print runs, better branding, and faster design changes being able to attract interest of brands that seek unique packaging but do not want to invest into expensive setup needed for conventional flexographic printing. These services are especially interesting for online retailers and brands that sell directly to consumers who are looking for ways to turn their packaging into marketing tool.
Further evolution of e-commerce-friendly packaging design provides an additional field for development, as suppliers create designs of boxes that would help to enhance shipping and unboxing processes of online stores. Suppliers that are capable of designing lightweight yet highly protective boxes will be able to attract the attention of customers that are interested in reducing costs of shipping and improving protection of their products.
Recent Developments:
-
In July 2024, Smurfit Kappa completed its combination with WestRock, forming Smurfit Westrock, which began trading as the new combined entity on the New York Stock Exchange and the London Stock Exchange.
-
On July 1, 2025, International Paper completed the divestiture of five European corrugated box plants, located in France, Portugal, and Spain, to PALM Group of Germany, satisfying regulatory commitments required by the European Commission for its acquisition of DS Smith Plc.
-
In 2025, Packaging Corporation of America announced the closure of two corrugated sheet and box production facilities, including one in Allentown, Pennsylvania, as part of broader industry-wide facility rationalization.
Corrugated Packaging Market Key Players
-
International Paper Company
-
Smurfit Westrock plc
-
Mondi Group
-
Oji Holdings Corporation
-
Georgia-Pacific LLC
-
Rengo Co., Ltd.
-
Cascades Inc.
-
Klabin S.A.
-
Packaging Corporation of America
-
Nine Dragons Paper Holdings Limited
-
Stora Enso Oyj
-
Sonoco Products Company
-
Pratt Industries, Inc.
-
Saica Group
-
VPK Packaging Group
-
Greif, Inc.
-
Menasha Corporation
-
GWP Group
-
Cascades Containerboard Packaging
-
Hexacomb Corporation
Corrugated Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 255.20 Billion |
| Market Size by 2035 | USD 391.42 Billion |
| CAGR | CAGR of 4.37% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Slotted Boxes, Folded Cartons, Rigid Boxes, Corrugated Trays, Die-Cut Boxes, Sheets) • By Material (Recycled Fiber, Virgin Fiber, Mixed Fiber) • By Wall Construction (Single Wall, Double Wall, Triple Wall) • By End-Use (Food & Beverage, Electronics, Personal Care & Household Products, Healthcare, Industrial Goods, E-Commerce & Logistics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | International Paper Company, Smurfit Westrock plc, Mondi Group, Oji Holdings Corporation, Georgia-Pacific LLC, Rengo Co., Ltd., Cascades Inc., Klabin S.A., Packaging Corporation of America, Nine Dragons Paper Holdings Limited, Stora Enso Oyj, Sonoco Products Company, Pratt Industries, Inc., Saica Group, VPK Packaging Group, Greif, Inc., Menasha Corporation, GWP Group, Cascades Containerboard Packaging, Hexacomb Corporation |
Frequently Asked Questions
Key players include International Paper Company, Smurfit Westrock plc, Mondi Group, Oji Holdings Corporation, Packaging Corporation of America, and Stora Enso Oyj, among other global fiber-based packaging suppliers.
Continued adoption of digital printing technology for shorter, customizable print runs and continued expansion of e-commerce-optimized, right-sized packaging design represent the primary opportunities.
Growth is primarily driven by rapid e-commerce expansion and last-mile delivery packaging demand combined with rising environmental regulation favoring recyclable, fiber-based packaging alternatives.
By Wall Construction, Single Wall dominated the market with approximately 71.40% share in 2025, reflecting its optimal balance between strength, cost efficiency, and material usage.
Asia Pacific dominated the market with approximately 35.60% share in 2025, driven mainly by China and India's manufacturing scale and expanding e-commerce ecosystems.
