
Crown Closure Market Report Scope & Overview:
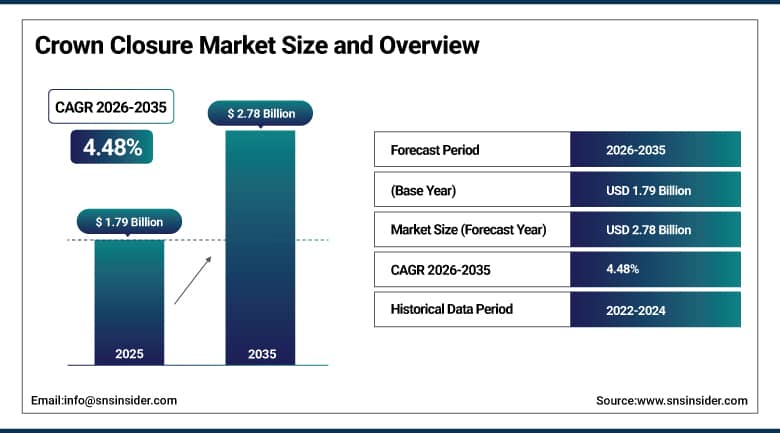
The Crown Closure Market was valued at USD 1.79 Billion in 2025 and is expected to reach USD 2.78 Billion by 2035, growing at a CAGR of 4.48% from 2026 to 2035.
A crown closure has barely changed in basic design since it was patented, a crimped metal disc holding a liner tight against a glass bottle rim, but the market around that simple mechanism keeps evolving. Beer remains the closure's stronghold, since carbonated beverages need the airtight seal a crown cap delivers better than most screw-cap alternatives, and the ongoing craft brewery boom in markets like the U.S. has kept demand steady even as some categories shift toward cans. What is genuinely changing is liner chemistry, PVC-based compounds that dominated for decades are giving way to PVC-free alternatives as food-contact regulation tightens, and manufacturers are increasingly adding QR codes and smart print stations to closures that used to be purely functional.
In 2025, Crown Holdings, Inc. announced a USD 150 million Asia-Pacific expansion embedding PVC-free liner capability and smart code print stations across its regional manufacturing footprint.
To Get More Information On Crown Closure Market - Request Free Sample Report
Crown Closure Market Trends
- PVC-free liner adoption is accelerating as food-contact chemical migration regulations tighten across major markets.
- Lightweight aluminum crown caps are gaining share as bottlers look to reduce material use and shipping weight.
- Craft breweries are driving demand for custom-printed, small-batch crown cap runs with digital inkjet capability.
- Smart closures featuring QR or NFC codes are expanding for anti-counterfeiting and consumer brand engagement purposes.
- Consolidation among metal packaging manufacturers is reshaping regional capacity and raw material bargaining power.
U.S. Crown Closure Market Outlook
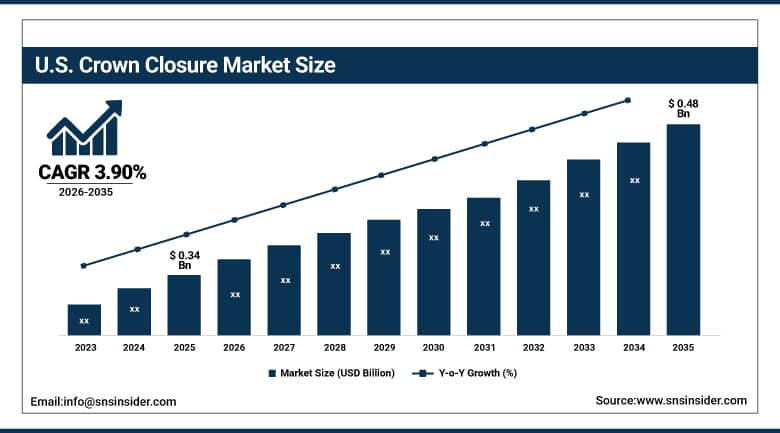
The U.S. Crown Closure Market was valued at USD 0.34 Billion in 2025 and is projected to reach USD 0.48 Billion by 2035, growing at a CAGR of 3.90% during 2026-2035.
The sheer scale of American craft brewing, more than 9,000 breweries at last count, gives the U.S. crown closure market a demand base unlike almost anywhere else, even as some craft producers shift a portion of their packaging toward cans. Regulatory pressure around PVC-based liner compounds is prompting early adoption of PVC-free alternatives among domestic suppliers positioning themselves ahead of anticipated enforcement deadlines, which is reshaping which manufacturers win contracts with major breweries. Premium and imported glass-bottled beverage categories continue to rely on crown closures for both their sealing performance and the traditional aesthetic many beer and specialty beverage brands still want. Consolidation among metal packaging suppliers, including recent acquisition activity in the broader closures space, is also concentrating domestic manufacturing capacity among fewer, larger players.
In March 2025, Sonoco Products Company completed a USD 3.87 billion acquisition of Eviosys, expanding its European metal packaging and closures footprint and diversifying its lid and closure format portfolio.
Crown Closure Market Segment Analysis
- By Material Type, steel & tinplate segment dominated the crown closure market in 2025 with 58% share; aluminum segment is the fastest-growing segment, registering a CAGR of 5.56% from 2026 to 2035.
- By Application, beverages segment dominated the crown closure market in 2025 with 89% share; food segment is the fastest-growing segment, registering a CAGR of 6.20% from 2026 to 2035.
- By Beverage Type, beer segment dominated the crown closure market in 2025 with 46% share; craft & specialty beverages segment is the fastest-growing segment, registering a CAGR of 6.80% from 2026 to 2035.
- By Liner Type, PVC-based liners segment dominated the crown closure market in 2025 with 54% share; PVC-free liners segment is the fastest-growing segment, registering a CAGR of 7.20% from 2026 to 2035.
By Material Type, steel & tinplate dominated the crown closure market while aluminum grows fastest
Steel & Tinplate holds 58% of the Crown Closure Market, remaining the standard material choice largely because it offers the rigidity and consistent crimping performance that high-speed bottling lines depend on, along with lower material costs than aluminum alternatives. Tinplate closures also support the kind of detailed embossing and printing that craft and premium beverage brands favor for limited-edition or branded promotional runs, giving the material a design advantage that partly offsets its weight disadvantage.
Aluminum is growing at a 5.56% CAGR, the fastest pace among materials, as bottlers increasingly prioritize lightweighting to cut shipping costs and reduce material use per unit. Aluminum's corrosion resistance also makes it a more durable long-term choice for beverages stored or transported in humid conditions, an advantage that is becoming more relevant as global beverage trade volumes keep expanding into new climates and markets.
By Application, beverages dominated the crown closure market while food grows fastest
Beverages account for 89% of application demand, reflecting how fundamental crown closures remain to carbonated soft drinks, bottled water, and above all beer, where the airtight seal a crown cap provides directly protects the carbonation that defines the product experience. Few alternative closure types can match the combination of sealing reliability, tamper evidence, and low per-unit cost that crown caps deliver at the high production speeds beverage bottling requires.
Food is the fastest-growing application, expanding at a 6.20% CAGR, as specialty and premium food producers, sauces, preserves, pickled and fermented products, increasingly adopt crown-style metal closures for their tamper-evident sealing and shelf-stable barrier performance. Growing demand for artisanal and small-batch food products has reinforced this trend, since crown closures pair well with the glass jar formats these categories typically favor.
By Beverage Type, beer dominated the crown closure market while craft & specialty beverages grows fastest
Beer accounts for 46% of demand by beverage type, the largest single category, reflecting the format's deep historical association with bottled beer and the practical reality that crown caps still deliver the most reliable, cost-effective seal for a carbonated, glass-bottled product at scale. The ongoing craft brewery boom across multiple regions has reinforced this category's lead even as some large commercial breweries have shifted a portion of their packaging mix toward cans.
Craft & Specialty Beverages is the fastest-growing beverage type, expanding at a 6.80% CAGR, as small-batch producers value the custom embossing, limited-run printing flexibility, and premium aesthetic that crown closures offer over standardized screw caps. Digital inkjet printing capability has made low-minimum-order custom crown cap runs increasingly accessible to smaller producers who previously could not justify the tooling cost of custom closures.
By Liner Type, PVC-based liners dominated the crown closure market while PVC-free liners grows fastest
PVC-Based Liners still hold 54% of the liner-type market, largely because they remain a proven, cost-effective sealing technology with decades of manufacturing history behind it across the closure industry. Many bottlers, particularly in regions without immediate regulatory pressure to switch, have been slower to transition away from PVC given the retooling and requalification costs involved in adopting alternative liner chemistries.
PVC-Free Liners are growing fastest, at a 7.20% CAGR, as food-contact chemical migration regulations tighten across Europe and increasingly in North America, pushing bottlers toward compliant alternatives ahead of enforcement deadlines rather than waiting until compliance becomes mandatory. Manufacturers who have already scaled PVC-free liner production are winning early contracts with beverage brands looking to get ahead of regulatory risk rather than retrofit their packaging under time pressure.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.20% |
|
Asia Pacific |
China |
38.40% |
|
Europe |
Germany |
24.90% |
|
Middle East & Africa |
UAE |
16.70% |
|
Latin America |
Brazil |
27.60% |
Asia Pacific Crown Closure Market Insights
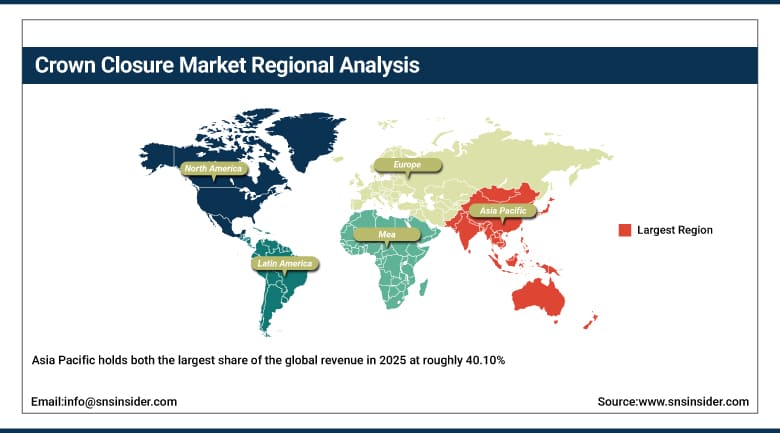
Asia Pacific holds both the largest share of the global revenue in 2025 at roughly 40.10%, and the fastest growth rate in the global crown closure market, driven by expanding brewery capacity and rising packaged beverage consumption across China, India, and Southeast Asia. Rising disposable incomes and continued urbanization are expanding both domestic beer consumption and the modern retail infrastructure needed to distribute bottled beverages at scale.
China holds roughly 38.40% of the regional market, supported by its large domestic brewing industry and expanding beverage bottling capacity. India is growing quickly as brewery expansion and premium beverage consumption both accelerate, while Japan and South Korea contribute through their established premium and craft beer sectors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Crown Closure Market Insights
North America's crown closure market is mature and steady, anchored by a craft brewing industry unlike any other in scale, more than 9,000 breweries across the U.S. alone, even as demand growth has moderated compared to the region's craft beer boom years. Regulatory pressure around PVC-free liner adoption is reshaping which suppliers win contracts more than any change in overall closure volume.
The United States accounts for approximately 85.20% of the North American market, reflecting its large craft brewing base and established beverage bottling infrastructure. Canada contributes a smaller but steady share, tied to its own craft beer culture and premium beverage import market.
Europe Crown Closure Market Insights
Europe's crown closure market is mature and shaped heavily by regulatory pressure around liner chemistry, particularly REACH enforcement on PVC-based compounds, which is accelerating the region's transition to PVC-free alternatives faster than almost anywhere else. Strong beer consumption traditions across the region continue to support steady demand even as growth in absolute volume terms remains modest.
Germany leads the European market with a 24.90% share, supported by its large brewing industry and advanced closures manufacturing base. The United Kingdom and France follow, with demand in both countries tied to established beer and premium beverage bottling traditions.
Middle East & Africa and Latin America Crown Closure Market Insights
Middle East & Africa is expanding at a steady pace with the rise in packaged beverages consumption in larger cities in the region, albeit from a relatively lower base considering the impact of culture and regulations on alcoholic beverages consumption in some countries in the region. Latin America has a stronger growth trajectory fueled by increasing brewery production in Brazil and increase in packaged beverages consumption in major cities in the region.
United Arab Emirates holds the largest share in Middle East & Africa market, accounting for 16.70%, while in Latin America, the largest share of 27.60% is held by Brazil owing to its large brewing sector. Mexico has a sizeable share in the market due to beer exports.
Market Dynamics
Growth Drivers: Craft Brewery Expansion and Liner Regulation Fueling Market Growth
Continued expansion of craft and specialty brewing, particularly across North America and increasingly in Asia Pacific, is the clearest driver behind steady crown closure demand, as small-batch producers favor the format's traditional aesthetic and custom printing flexibility. Tightening food-contact liner regulation is reinforcing that demand by pushing bottlers toward newer, compliant PVC-free closures rather than continuing to use older liner chemistries.
Rising packaged beverage consumption across emerging Asia Pacific and Latin American markets is creating meaningful volume growth as brewing capacity and modern retail infrastructure both expand in tandem.
Restraints: Can Substitution and Aluminum Price Volatility Limiting Market Expansion
Substitution toward aluminum cans, particularly among large commercial breweries and carbonated soft drink producers, remains a structural headwind for crown closure demand, since cans offer comparable sealing performance with different logistical and branding advantages. Aluminum price volatility, tied to broader commodity market swings, also makes it difficult for closure manufacturers to hold pricing steady with beverage bottling customers on long-term supply contracts.
Limited recycling infrastructure for metal closures in parts of Africa and Southeast Asia can also complicate sustainability positioning for crown caps in markets where regulatory pressure toward recyclable packaging is beginning to build.
Opportunities: Smart Closures and Craft Beverage Customization Creating New Growth Avenues
Smart closures featuring QR or NFC codes represent a genuine opportunity for manufacturers to differentiate on brand engagement and anti-counterfeiting capability rather than sealing performance alone, particularly for premium and export-oriented beverage brands concerned about product authentication. Beverage brands managing complex, geographically dispersed supply chains are increasingly willing to pay a premium for that traceability.
Custom, low-minimum-order crown cap printing for craft and small-batch producers offers a second clear opportunity, particularly as digital inkjet technology continues to lower the cost of short production runs that would have been economically unfeasible with traditional printing methods just a few years ago.
Recent Developments:
- 2025: Crown Holdings, Inc. announced a USD 150 million Asia-Pacific expansion embedding PVC-free liner capability and smart code print stations across its regional manufacturing footprint.
- 2025: Pelliconi & C. S.p.A. implemented an AI-driven quality inspection system that cut liner defects by 15% across its crown cap production lines.
- March 2025: Sonoco Products Company completed a USD 3.87 billion acquisition of Eviosys, expanding its European metal packaging and closures footprint and diversifying its lid and closure format portfolio.
- 2024: Finn-Korkki Oy achieved carbon-neutral operations at its Finnish crown cap manufacturing facility by installing 325 kWp of rooftop solar capacity and switching to 100% fossil-free electricity.
Crown Closure Market key players are:
- Crown Holdings, Inc.
- Ball Corporation
- Silgan Holdings Inc.
- BERICAP Holding GmbH
- Nippon Closures Co., Ltd.
- AptarGroup, Inc.
- Sonoco Products Company
- Amcor plc
- Closure Systems International, Inc.
- Astir Vitogiannis Bros S.A.
- PELLICONI & C. S.p.A.
- Guala Closures Group S.p.A.
- Tapón Corona de México, S.A. de C.V.
- Vinca Metal Closures Pvt. Ltd.
- Manaksia Limited
- G3 Enterprises, Inc.
- Torishima Packaging Industry Co., Ltd.
- Tecnocap Group
- Finn-Korkki Oy
- Grupo Convermex, S.A. de C.V.
Crown Closure Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.79 Billion |
| Market Size by 2035 | USD 2.78 Billion |
| CAGR | CAGR of 4.48% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Steel & Tinplate, Aluminum, Plastic) • By Application (Beverages, Food) • By Beverage Type (Beer, Carbonated Soft Drinks, Craft & Specialty Beverages, Others) • By Liner Type (PVC-Based Liners, PVC-Free Liners) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Crown Holdings, Inc., Ball Corporation, Silgan Holdings Inc., BERICAP Holding GmbH, Nippon Closures Co., Ltd., AptarGroup, Inc., Sonoco Products Company, Amcor plc, Closure Systems International, Inc., Astir Vitogiannis Bros S.A., PELLICONI & C. S.p.A., Guala Closures Group S.p.A., Tapón Corona de México, S.A. de C.V., Vinca Metal Closures Pvt. Ltd., Manaksia Limited, G3 Enterprises, Inc., Torishima Packaging Industry Co., Ltd., Tecnocap Group, Finn-Korkki Oy, Grupo Convermex, S.A. de C.V. |
Frequently Asked Questions
Key players include Crown Holdings, Inc., Ball Corporation, Silgan Holdings Inc., BERICAP Holding GmbH, and Nippon Closures Co., Ltd., alongside other established closure and metal packaging manufacturers.
Key opportunities include smart closures with QR or NFC codes for brand engagement and anti-counterfeiting, custom low-minimum-order printing for craft and specialty beverage producers, and expanding PVC-free liner adoption ahead of tightening food-contact regulation.
The market is driven by continued craft and specialty brewery expansion, tightening food-contact liner regulation, and rising packaged beverage consumption across emerging markets.
The Steel & Tinplate segment dominated the Crown Closure Market in 2025.
The Asia Pacific region dominated the Crown Closure Market in 2025, accounting for approximately 40.10% of global market share.
