
Dietary Fibers Market Report Scope & Overview:
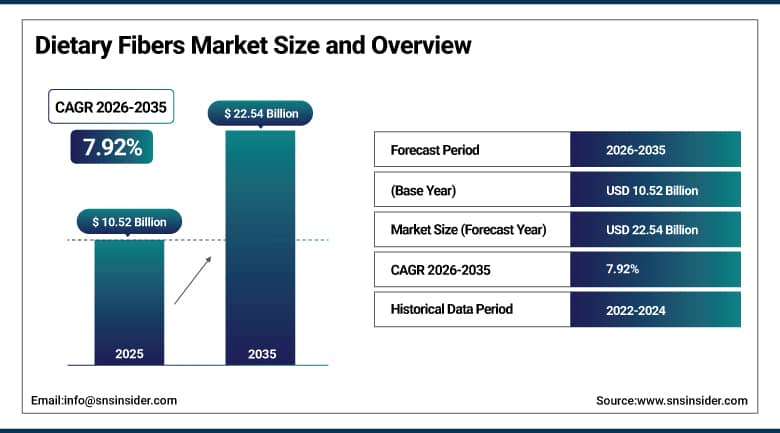
Dietary Fibers Market size was valued at USD 10.52 Billion in 2025 and is estimated to reach USD 22.54 Billion by 2035 with a CAGR of 7.92% between 2026 and 2035.
Dietary fibers are carbohydrates from plant origins that cannot be broken down in the human body and help maintain digestive systems through promoting proper gut health, blood glucose levels and cholesterol, serving to maintain the health of our digestive system by regulating blood sugar levels. They serve different industries like food and beverages, pharmaceutical, animal feed, and specialty nutrition, with manufactures focusing on improving the fiber functionalities, solubilities, and neutral tastes in order to increase their incorporations in the products.
In 2026, Ingredion Incorporated declared an all-cash acquisition deal worth approximately USD 5 billion for Tate & Lyle PLC, to create a scalable supplier of specialty ingredients across texturants, sugar reduction and fortification solutions, as well as completing another deal for the acquisition of Benicaros, which is a prebiotic fiber extracted from upcycled carrot pomace, representing the ongoing wave of acquisitions taking place in the dietary fiber ingredients industry landscape.
To Get More Information On Dietary Fibers Market - Request Free Sample Report
Dietary Fibers Market Trends
- Growing scientific expertise and reformulation capabilities are becoming as valuable as production scale amid accelerating ingredient industry consolidation.
- Rising demand for gluten-free and plant-based dietary fiber ingredients continues to reshape formulation priorities across food and beverage manufacturers.
- Expanding sustainability initiatives and circular economy practices are driving adoption of fibers extracted from fruit peels, vegetable pomace, and cereal husks.
- Increasing prebiotic certification activity, including NutraStrong Prebiotic Verified status, continues to validate functional claims across leading fiber portfolios.
- Growing GLP-1 medication adoption is creating fresh opportunities for fiber ingredients that help manufacturers develop more nutrient-dense, satiety-supporting foods.
U.S. Dietary Fibers Market Outlook
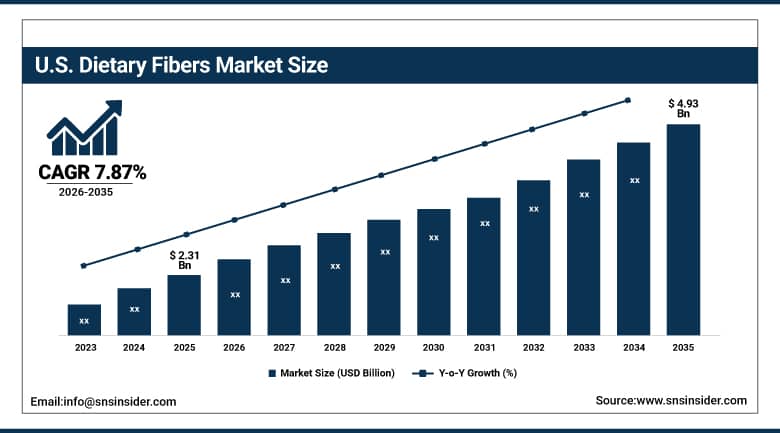
The U.S. Dietary Fibers Market was valued at USD 2.31 Billion in 2025 and is projected to reach USD 4.93 Billion by 2035, growing at a CAGR of 7.87% during 2026-2035.
Rising health awareness, increasing prevalence of chronic illnesses, and the ongoing shift toward plant-based eating habits continue to support robust market growth across the United States. Leading manufacturers continue to expand specialized fiber portfolios addressing rising consumer demand for functional, health-oriented ingredients. Growing GLP-1 medication-driven demand for nutrient-dense, high-fiber food formulations continues to reinforce sustained domestic market development nationwide.
Ingredion Incorporated, which operates one of the largest corn wet milling operations in the world at its Cedar Rapids, Iowa facility, continues to anchor its North American production capacity amid the integration of its Tate & Lyle acquisition, positioning the combined company as a scaled provider of specialty ingredient solutions with the innovation expertise and geographic reach to shape the future of American food formulation.
Dietary Fibers Market Segment Analysis
- By Type, soluble led the dietary fibers market share in 2025, while insoluble is the fastest-growing type segment with a CAGR of 8.60% from 2026-2035.
- By Category, prebiotic led the dietary fibers market with around 66.50% share in 2025, while non-prebiotic is the fastest-growing category segment with a CAGR of 8.80% from 2026-2035.
- By Source, cereals & grains led the dietary fibers market with approximate 44.76% share in 2025, while waste products is the fastest-growing source segment with a CAGR of 9.20% from 2026-2035.
- By Application, food & beverage led the dietary fibers market with around 48.60% share in 2025, while pharmaceuticals & dietary supplements is the fastest-growing application segment with a CAGR of 8.90% from 2026-2035.
By Type, Soluble Dominated the Market While Insoluble Is the Fastest-Growing Segment
The soluble segment dominated the global dietary fibers market in terms of revenue in 2025 owing to its various benefits, including health benefits, and wide range of food applications in managing gastrointestinal issues, blood cholesterol, and controlling glycemia. Soluble fibers remain highly popular ingredients in beverages, dairy substitutes, and functional foods focused on maintaining heart and metabolic health, ensuring continued dominance of this type in the entire dietary fibers market across the globe.
The insoluble segment is projected to register the highest CAGR of 8.60% in the coming forecast period of 2026-2035 owing to growing awareness among consumers regarding digestive health and the importance of insoluble fibers in regulating bowel movements. Continued integration in bakery products, cereals, and snacks to cater to the rising need for healthy, fiber-rich products on-the-go is further boosting the above-average growth trajectory of this segment compared to soluble fibers.
By Category, Prebiotic Dominated the Market While Non-Prebiotic Is the Fastest-Growing Segment
Prebiotic dietary fibers accounted for the highest revenue share of approximately 66.50% in 2025 on account of growing customer preference towards nutraceutical dietary fibers that offer clinically proven benefits to the human gut microbiota. The increasing investment in nutraceutical ingredients and the rising trend of prebiotic certification would further support the dominance of prebiotic dietary fibers in the overall dietary fibers market.
The non-prebiotic segment is estimated to be the fastest-growing segment at a CAGR of 8.80% during the forecast period from 2026 to 2035 owing to increased fiber fortification applications without any health benefits claims of prebiotics, which would help improve texture and nutrition profiles of food formulations. Increasing demand for fiber fortification without health benefits claims of prebiotics would further drive the growth of the segment.
By Source, Cereals & Grains Dominated the Market While Waste Products Is the Fastest-Growing Segment
The cereals & grains segment led the dietary fibers market with a revenue share of approximately 44.76% in 2025, attributed to their high fiber content and adaptability in various food products spanning bakery, cereals, and snack applications. Cereals and grains continue to offer manufacturers established, cost-effective fiber sourcing infrastructure, sustaining this source category's dominant position across the broader dietary fibers market worldwide.
The waste products segment is expected to register the fastest CAGR of 9.20% during the forecast period 2026-2035, fueled by sustainability initiatives and the growing adoption of circular economy practices. Fibers extracted from by-products such as fruit peels, vegetable pomace, and cereal husks continue gaining traction among eco-conscious consumers and manufacturers aiming to reduce food waste while providing functional benefits, reinforcing this segment's above-average growth trajectory.
Regional Analysis
|
Region |
Country |
Regional Share (2025) |
|---|---|---|
|
Asia Pacific |
China |
34.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
22.80% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
24.60% |
Asia Pacific Dietary Fibers Market Insights
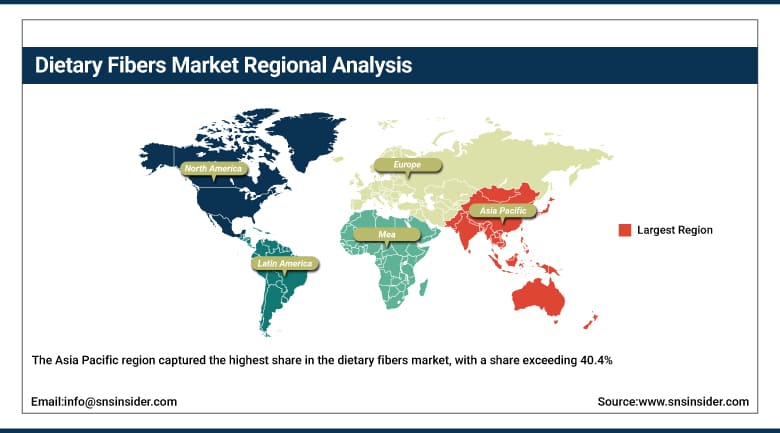
The Asia Pacific region captured the highest share in the dietary fibers market, with a share exceeding 40.4%, owing to growing health consciousness, presence of chronic conditions, and growing consumption of functional food & supplements across the region. Continued innovations in fiber extraction techniques further strengthen the dominance of the Asia Pacific region within the wider dietary fibers industry.
China contributed around 34.60% towards the Asia Pacific region in 2025, owing to the growing food processing industry in the country as well as growing consumer health consciousness. Other emerging countries in the region that contribute to the overall growth of the region include Japan, India, and South Korea, with the latter being a beneficiary of growing foodgrain production and wellness retailing infrastructure.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Dietary Fibers Market Insights
North America market is anticipated to follow an accelerated growth trend over the forecast period 2026-2035 owing to the rising chronic diseases incidence rate, preference for plant-based diet, and rising requirement of functional foods and supplements. Increasing use of GLP-1 drugs and creating new possibilities for nutrient-rich foods further fueling the growth of the region.
In 2025, the United States held nearly 84.60% share of the total North America market owing to its presence of top dietary fiber producers like Cargill, ADM, Ingredion, and Tate & Lyle. Canada is making a valuable contribution to regional growth through adoption of functional foods and rising consumer inclination towards fiber-rich foods.
Europe Dietary Fibers Market Insights
Europe represented a meaningful share of the global dietary fibers market in 2025, supported by a dense concentration of leading ingredient companies headquartered across the region and strong regulatory frameworks supporting fiber health claims. Growing prebiotic certification activity and specialty fiber portfolio expansion continue to reinforce steady regional demand across the broader European dietary fibers landscape.
Germany led the European market with a 22.80% regional share in 2025, supported by its strong food processing industry and consumer demand for functional nutrition products. The United Kingdom, France, and Belgium are also contributing meaningfully to regional growth, supported by leading dietary fiber manufacturers headquartered across the region.
Middle East & Africa and Latin America Dietary Fibers Market Insights
The Middle East & Africa region is exhibiting steady growth as health and wellness awareness expands across the Gulf states, supported by growing modern retail infrastructure. Latin America is similarly benefiting from rising disposable income and growing consumer interest in functional, high-fiber food products across major regional urban centers.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by growing health-conscious consumer demand and expanding modern retail penetration. Brazil represented 24.60% of the Latin American market in 2025, driven by expanding functional food consumption, with Mexico also contributing to regional growth through rising interest in fiber-fortified products.
Market Dynamics
Growth Drivers: Chronic Disease Prevention and Functional Food Fortification Driving Market Growth
The Dietary Fibers Market is experiencing significant impetus on account of rising awareness regarding health, increasing incidences of chronic diseases, the transition to a plant-based diet regimen, favorable government policies for encouraging fiber consumption, and technological advancements in the process of extracting fiber. Consumer inclination towards nutraceutical products from pharmaceutical products, along with increasing investments in the nutraceutical ingredients market, has continued to act as a major catalyst for dietary fibers market growth.
Expertise in science and formulation is equally important as production volumes in view of ongoing consolidation in the ingredient market industry. Increasing demand for gluten-free and plant-based dietary fiber ingredients has continued to redefine formulation considerations. Initiatives around sustainability and the circular economy have further spurred the adoption of fibers obtained from waste materials.
Restraints: Taste Impact and High Processing Costs Limiting Market Expansion
In spite of the positive underlying demand scenario, the market has some major limitations in terms of the adverse effect that fiber has on taste, texture, and mouthfeel, which negatively affects consumer acceptance in some formulation types. The high cost associated with fiber extraction and production is continually driving up prices, thus limiting wider acceptance due to high cost sensitivities on both the supplier and consumer ends.
The increased competition in the growing number of global suppliers of ingredients, especially with the consolidation trend becoming more evident in the sector, has continued to squeeze margins in most fiber ingredient categories. There is also the problem of regulatory differences in terms of the prebiotic claims associated with dietary fibers.
Opportunities: GLP-1 Nutrient Density Innovation and Upcycled Ingredient Development Creating New Growth Avenues
Substantial opportunity exists in continued development of nutrient-dense, satiety-supporting fiber formulations addressing rising GLP-1 medication adoption and evolving consumer nutritional needs. Companies that successfully commercialize differentiated, functionally validated fiber ingredients stand to capture significant share of category growth as manufacturers seek to develop more nutrient-dense foods for an increasingly health-conscious consumer base.
Growing upcycled and by-product-derived fiber ingredient development presents a further significant growth avenue, as sustainability-focused brands increasingly seek circular economy-aligned sourcing options. Expanding prebiotic certification activity and clean-label fiber innovation across emerging markets in Asia Pacific and Latin America also represent meaningful untapped opportunity for dietary fiber manufacturers.
Recent Developments:
- 2026: Roquette's NUTRIOSE soluble fibers gained NutraStrong Prebiotic Verified certification from SGS Nutrasource.
- 2025: BENEO received Thai Food and Drug Administration approval for an exclusive prebiotic claim for its Orafti Inulin ingredient.
- 2024: Tate & Lyle completed its combination with CP Kelco, adding pectin and specialty gums to its ingredient portfolio.
Dietary Fibers Market key players are:
- Cargill, Incorporated
- Archer Daniels Midland Company
- Ingredion Incorporated
- Tate & Lyle PLC
- DSM-Firmenich AG
- Kerry Group plc
- Roquette Frères
- J. Rettenmaier & Söhne GmbH + Co KG
- BENEO GmbH
- Nexira SAS
- Sensus B.V.
- Emsland Group
- Grain Processing Corporation
- Fiberstar, Inc.
- International Flavors & Fragrances Inc.
- AGT Food and Ingredients Inc.
- SunOpta Inc.
- Baolingbao Biology Co., Ltd.
- Church & Dwight Co., Inc.
- CP Kelco U.S., Inc.
Dietary Fibers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 10.52 Billion |
| Market Size by 2035 | USD 22.54 Billion |
| CAGR | CAGR of 7.92% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Soluble, Insoluble) • By Category (Prebiotic, Non-Prebiotic) • By Source (Cereals & Grains, Legumes, Nuts & Seeds, Fruits, Vegetables, Waste Products) • By Application (Food & Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cargill, Incorporated; Archer Daniels Midland Company; Ingredion Incorporated; Tate & Lyle PLC; DSM-Firmenich AG; Kerry Group plc; Roquette Frères; J. Rettenmaier & Söhne GmbH + Co KG; BENEO GmbH; Nexira SAS; Sensus B.V.; Emsland Group; Grain Processing Corporation; Fiberstar, Inc.; International Flavors & Fragrances Inc.; AGT Food and Ingredients Inc.; SunOpta Inc.; Baolingbao Biology Co., Ltd.; Church & Dwight Co., Inc.; CP Kelco U.S., Inc. |
Frequently Asked Questions
The Dietary Fibers Market is expected to grow at a CAGR of 7.92% from 2026 to 2035.
The Dietary Fibers Market was valued at USD 10.50 Billion in 2025.
The market is driven by growing health consciousness, the rise in chronic illnesses, the ongoing shift toward plant-based eating habits, and supportive government policies.
The Asia Pacific region dominated the Dietary Fibers Market in 2025, accounting for over 40.4% market share.
