
Digital Shipyard Market Report Scope & Overview:
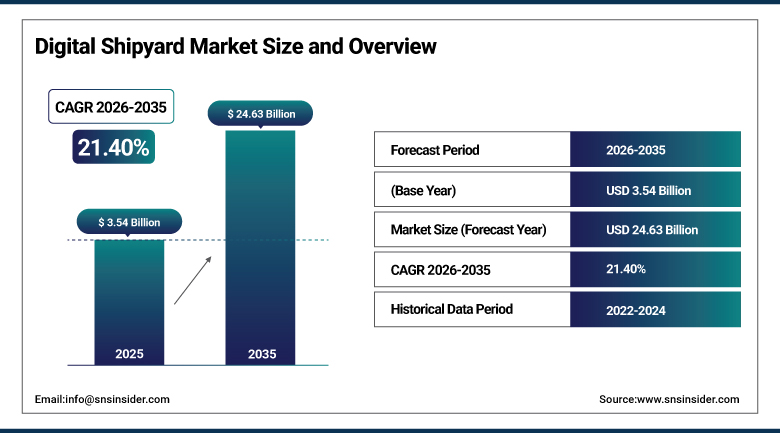
The Digital Shipyard Market was valued at USD 3.54 Billion in 2025 and is expected to reach USD 24.63 Billion by 2035, growing at a CAGR of 21.40% from 2026-2035.
Digital Shipyard Market is being fueled largely due to the increasing uptake of digital twins, automation, and data analytics by shipbuilders to enhance their efficiency, cut costs, and cope with the complexities of shipbuilding. Increasing international maritime trade activities are creating higher demands for commercial ships and thus are encouraging shipyards to upgrade their infrastructure and adopt integrated digital solutions covering the whole life cycle of ship construction from design to manufacture. Higher demand is further encouraged by persistent modernization initiatives within the world’s navies requiring rigorous validation of digital twins and advanced manufacturing processes to cope with tough production deadlines. Increasing use of artificial intelligence in robotic manufacturing processes, along with the growing implementation of additive manufacturing in manufacturing tools and spare parts, is making this market a strong candidate for high growth during the coming years.
In November 2025, Siemens Digital Industries Software signed a memorandum of understanding with HD Hyundai to drive the modernization of the commercial shipbuilding industry in the United States, positioning Siemens Xcelerator as the digital backbone for integrating digital twin, model-based systems engineering, and product lifecycle management technologies into shipyard automation.
To Get more information Digital Shipyard Market - Request Free Sample Report
Digital Shipyard Market Trends
- Rising adoption of digital twin technology providing unified data flow across design, engineering, and production.
- Growing integration of artificial intelligence and big data analytics into automated production processes.
- Increasing use of AR/VR simulation solutions for workforce training and shipboard operations preparation.
- Continued shipyard modernization driven by naval modernization programs and commercial fleet renewal.
- Expanding adoption of additive manufacturing for tooling, jigs, fixtures, and selected spare parts.
U.S. Digital Shipyard Market Outlook
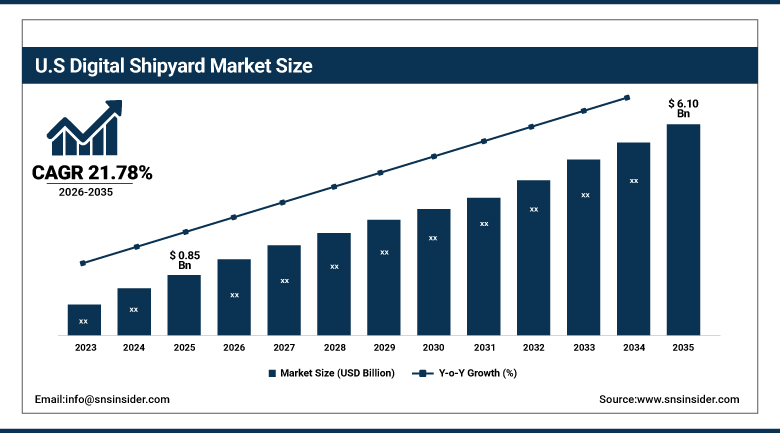
The U.S. Digital Shipyard Market was valued at USD 0.85 Billion in 2025 and is expected to reach USD 6.10 Billion by 2035, growing at a CAGR of 21.78% from 2026-2035.
The U.S. Digital Shipyard Market growth continues to be reinforced by renewed policy emphasis on revitalizing domestic commercial and naval shipbuilding capacity, growing cross-border technology partnerships aimed at modernizing legacy shipyard infrastructure, and sustained defence modernization spending supporting cyber-hardened, digitally validated production lines. Domestic demand also benefits from the country's concentration of leading digital engineering software providers driving continued innovation in digital twin and product lifecycle management technology. Continued workforce development initiatives further support demand as shipyards seek to rebuild engineering and skilled trade capacity alongside their digital transformation investments.
In 2025, The U.S. Navy expanded its use of digital twin technology for fleet resilience, with digital-twin capabilities being incorporated into next-generation SSN(X) submarine design to support predictive maintenance, performance monitoring, and lifecycle optimization.
Digital Shipyard Market Segment Analysis
- By Solution, the Hardware segment dominated the Digital Shipyard Market with approximately 45.90% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 24.50%.
- By Shipyard Type, the Commercial segment dominated the Digital Shipyard Market with approximately 67.30% share in 2025, while the Military segment is the fastest growing with a CAGR of approximately 18.91%.
- By Technology, the Digital Twin segment dominated the Digital Shipyard Market with approximately 39.86% share in 2025, while the AI & Big Data Analytics segment is the fastest growing with a CAGR of approximately 25.90%.
- By Capacity, the Large Shipyards segment dominated the Digital Shipyard Market with approximately 62.0% share in 2025, while the Large Shipyards segment is also expected to be the fastest growing, registering a CAGR of approximately 16.7% during the forecast period.
By Solution, Hardware dominates and Software grows fastest
The Hardware Solutions Segment is still the leader of the Digital Shipyard Market because of the huge amount of money that the shipyards need to invest in sensors, robots, automation machinery, and supercomputing equipment to enable digital transformation projects at their yards. The development of this segment continues because of ongoing modernization of naval fleets and fleet renewals, which require investment in hardware infrastructure before proceeding to software solutions.
Software Solutions Segment is currently the fastest-growing segment due to increasing needs of the shipyards in the development of digital twins, product life cycle management software, and analytical software based on artificial intelligence that makes use of the current hardware infrastructure. This segment specializes in the development of platforms that integrate data about design, production, and maintenance in one data flow.
By Shipyard Type, Commercial dominates and Military grows fastest
Commercial shipyards remain the dominant shipyard type segment within the Digital Shipyard Market, reflecting the sheer scale of global commercial vessel production driven by expanding international maritime trade. This segment benefits from sustained demand for new commercial vessels and ongoing maintenance and repair of existing fleets, both of which continue to push shipyards toward digital transformation to improve production efficiency and reduce delivery timelines.
Military shipyards are emerging as the fastest-growing shipyard type segment, driven by sustained naval modernization programs that require rigorous digital-twin validation and additive manufacturing capabilities to meet demanding defence production and deployment timelines. This segment focuses on cyber-hardened production lines and secure digital infrastructure suited to defence program requirements, positioning military shipyards to capture a rapidly growing share of overall digital shipyard investment as navies fund modernization initiatives.
By Technology, Digital Twin dominates and AI & Big Data Analytics grows fastest
The Digital Twin technology continues to lead the way in the technology segments dominating the Digital Shipyard Market. The technology provides the basis upon which shipyards can develop virtual models of ships and their manufacturing processes for purposes of validating the designs, planning production, and managing the whole lifecycle. It stands to benefit from being present throughout the value chain of ship manufacturing, providing the digital thread tying together all design, engineering, and manufacturing data.
The AI & Big Data Analytics technology segment will be the fastest-growing among the various technology segments in the market. It arises from the increasing adoption of artificial intelligence in robot manufacturing processes where there is no human involvement at all. The technology segment involves predictive analytics and the ability to make automated decisions from the large data streams provided by digital twin and sensors technologies.
By Capacity, Large Shipyards dominate and grow fastest
Large Shipyards dominated the Digital Shipyard Market in 2025, supported by their substantial capital investments, complex vessel production requirements, and greater adoption of advanced digital technologies. Large shipyards are increasingly deploying digital twins, AI-driven analytics, automation, robotics, and integrated ship design and production platforms to improve operational efficiency, reduce production costs, and optimize complex shipbuilding workflows.
Large Shipyards are also expected to be the fastest-growing capacity segment during the forecast period. Growth is driven by increasing digital transformation initiatives, modernization of shipbuilding infrastructure, and rising investments in automated and data-driven manufacturing systems. The need to manage complex production processes and improve lifecycle management is further accelerating digital technology adoption among large-scale shipyards.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
South Korea |
42.60% |
|
North America |
United States |
85.50% |
|
Europe |
Germany |
34.80% |
|
Latin America |
Brazil |
38.90% |
|
Middle East & Africa |
United Arab Emirates |
44.60% |
Asia Pacific Digital Shipyard Market Insights
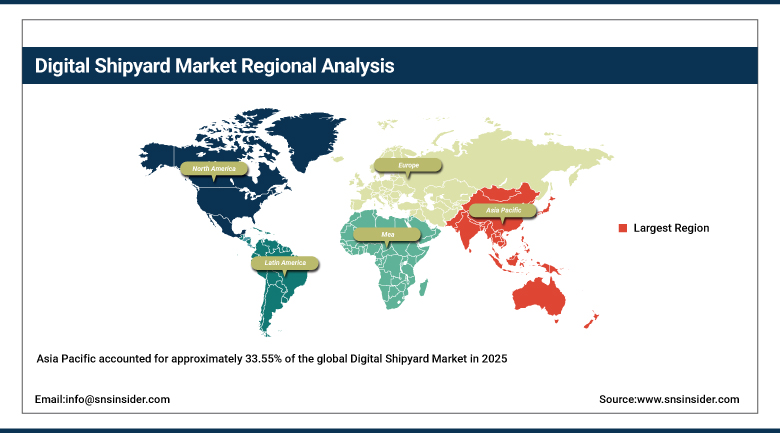
Asia Pacific accounted for approximately 33.55% of the global Digital Shipyard Market in 2025 and is also projected to expand at the fastest pace registering a CAGR of approximately 23.80% during the 2026–2035 forecast period. This is supported by sustained naval modernization programs and commercial fleet renewal across the region's dominant shipbuilding industry. South Korea represents a particularly significant contributor within the region, home to major shipbuilders including HD Hyundai, Hanwha Ocean, and Samsung Heavy Industries that continue investing heavily in digital shipyard transformation.
China contributes substantial additional regional volume through its massive domestic shipbuilding capacity and growing government investment in smart manufacturing infrastructure. Japan's established shipbuilding sector, with government reporting that a significant share of domestic shipyards are implementing digital technologies to improve efficiency, further reinforces Asia Pacific's position as both the largest and fastest-growing global market for digital shipyard technology.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Digital Shipyard Market Insights
North America region is a major market segment for digital shipyard technologies, driven by policy attention to rejuvenation of domestic shipbuilding capacities for military and civilian ships, along with international cooperation in technology transfer. In terms of demand, the majority of regional demand comes from the USA owing to ongoing military expenditures, as well as presence of leading suppliers of digital engineering software.
Another country contributing to regional demand is Canada due to its involvement in North American shipbuilding and defence industries. Investments in local shipyards' development and initiatives to develop engineering and skill sets among employees are another factor contributing to increasing demand for digital shipyard technology.
Europe Digital Shipyard Market Insights
Europe serves as an important regional market for digital shipyard technology, led by Germany's rich tradition of engineering, coupled with its leadership in digital shipyard technology in the region. The contribution of Germany towards European demand can be seen through the presence of leading shipbuilders like Meyer Werft and Lürssen in the domestic market and their ongoing utilization of digital twins, Internet of Things, and artificial intelligence for better quality production and reduced environmental impacts.
The United Kingdom and France provide extra demand in the region due to their established naval and commercial shipyards. The ongoing investments in Europe in terms of naval upgrades and sustainable shipbuilding drive continued demand in the region for digital shipyard technology.
MEA & Latin America Digital Shipyard Market Insights
The MEA region is growing in importance strategically with demand centered in markets of the Gulf Cooperation Council, particularly the UAE. Investments in marine infrastructure development, as well as naval modernization, have helped increase the adoption of Digital Shipyard technology gradually in the region. Overall demand in the region is relatively low compared to that of Asia Pacific, North America, and Europe due to the concentration of this technology in shipbuilding hot spots.
Brazil dominates the Digital Shipyard Market in Latin America because the country meets most of the regional demand, mainly owing to its strong shipbuilding industry, which builds offshore oil and gas production facilities. Demand in the region has been gradually rising as a result of facility modernizations within the region.
Market Dynamics
Growth Drivers: Naval Modernization and Commercial Fleet Renewal
Sustained naval modernization programs represent a primary growth driver for the Digital Shipyard Market, as navies worldwide fund cyber-hardened production lines requiring rigorous digital-twin validation and advanced manufacturing capabilities to meet demanding defence production timelines. This dynamic is reinforced by rising global maritime trade, which continues to increase demand for new commercial vessels and push shipyards to modernize legacy infrastructure through integrated digital platforms.
Growing complexity in vessel design and construction, including alternative fuel systems and lower-emissions requirements, provides an additional significant source of demand, as these increasingly sophisticated requirements necessitate digital design and simulation tools beyond traditional shipbuilding methods. Continued need to reduce project delays and improve vessel quality further supports market growth as shipbuilders pursue digital transformation to remain competitive in an increasingly complex production environment.
Restraints: High Implementation Costs and Legacy Infrastructure Integration
The high initial cost of transforming a shipyard into a fully digital one can be seen as an important constraint for the Digital Shipyard market, especially considering those shipyards that have already invested a lot of money into their existing production systems. This situation is further exacerbated by the technical difficulties of combining the new digital systems with the long-established manufacturing systems and methods.
A lot of shipyards in the world continue functioning using partially digital capacities, meaning that some departments use digital tools while others continue using the legacy ones. Moreover, the shortage of qualified engineers in the shipbuilding industry poses additional challenges to the complete digital transformation of a shipyard.
Opportunities: AI-Powered Automation and Workforce Development Integration
The continued use of AI in robotic production processes in the market represents a significant growth potential as this will lead to increased autonomous production which is able to function efficiently while requiring little human interaction. The suppliers that are able to provide validated solutions that are competitively priced will be able to capture market share based on the efficiencies that shipyards seek to gain from their operations.
The increasing importance of workforce development and training simulation represent a strategic opportunity for suppliers to extend their platforms from being production technology suppliers to human capital development tools for overcoming skills shortages in the shipbuilding sector. Suppliers that have already developed solutions for training and simulations using augmented reality and virtual reality are well-positioned to capture an outsized market share in this developing market.
Recent Developments:
- 2025: The U.S. Navy announced a USD 448 million investment in Ship OS, aimed at accelerating adoption of AI and autonomous technologies across the Navy shipbuilding industrial base and improving schedules, capacity, and cost efficiency.
- 2022: Wärtsilä introduced virtual and augmented reality simulation solutions leveraging AR and VR technologies to create immersive environments simulating real-life shipboard operations, improving learning retention, job performance, and team collaboration among shipyard and vessel crews.
Digital Shipyard Market Key Players are:
- Siemens AG
- Dassault Systèmes SE
- Accenture plc
- SAP SE
- BAE Systems plc
- iBase-t
- Hexagon AB
- Autodesk, Inc.
- ESI Group
- Wärtsilä Corporation
- Kongsberg Gruppen ASA
- Navantia S.A.
- Huntington Ingalls Industries, Inc.
- General Dynamics Electric Boat
- Fincantieri S.p.A.
- Hyundai Heavy Industries Co., Ltd.
- Hanwha Ocean Co., Ltd.
- Samsung Heavy Industries Co., Ltd.
- Meyer Werft GmbH & Co. KG
- Lürssen
Digital Shipyard Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.54 Billion |
| Market Size by 2035 | USD 24.63 Billion |
| CAGR | CAGR of 21.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Solution (Hardware, Software, and Services) • By Shipyard Type (Commercial and Military) • By Technology (Digital Twin, AI & Big Data Analytics, AR/VR, Automation & Robotics, Others) • By Capacity (Small Shipyards, Medium Shipyards, Large Shipyards) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens AG; Dassault Systèmes SE; Accenture plc; SAP SE; BAE Systems plc; iBase-t; Hexagon AB; Autodesk, Inc.; ESI Group; Wärtsilä Corporation; Kongsberg Gruppen ASA; Navantia S.A.; Huntington Ingalls Industries, Inc.; General Dynamics Electric Boat; Fincantieri S.p.A.; Hyundai Heavy Industries Co., Ltd.; Hanwha Ocean Co., Ltd.; Samsung Heavy Industries Co., Ltd.; Meyer Werft GmbH & Co. KG; Lürssen |

Frequently Asked Questions
Leading companies in the Digital Shipyard Market include Siemens, Dassault Systèmes, Accenture, SAP, and BAE Systems, among others.
Key opportunities include continued integration of artificial intelligence into robotic production processes, and rising emphasis on workforce development and training simulation to address skilled-labor shortages.
Sustained naval modernization programs, combined with rising global maritime trade and growing complexity in vessel design and construction, is the major factor driving market growth.
The Commercial segment dominated the Digital Shipyard Market with approximately 67.30% share in 2025.
Asia Pacific dominated the Digital Shipyard Market in 2025 with approximately 33.55% share, supported by sustained naval modernization programs and commercial fleet renewal, led by South Korea.
