
Drill Pipe Market Report Scope & Overview:
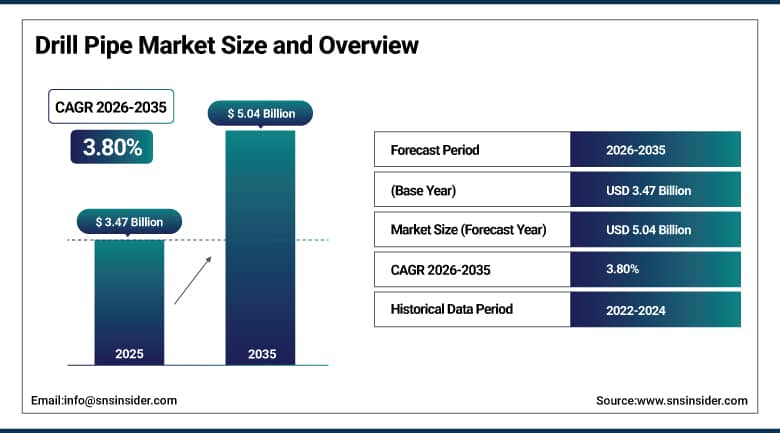
The global Drill Pipe Market was valued at USD 3.47 Billion in 2025 and is expected to reach USD 5.04 Billion by 2035, growing at a CAGR of 3.80% from 2026 to 2035.
The increase in the demand for oil and gas exploration and the increasing mining activities all around the world have been fueling the growth in this market, where there has been an observable trend in the use of lightweight and high strength drill pipes through the advancements in material science which includes carbon fiber composite and improved steel alloys.
Vallourec won a major contract with Petrobras in the year 2025 that will be worth up to 1 billion US dollars in supplying offshore oil country tubular goods such as seamless pipes and premium connections from 2026 to 2029, which is the largest award ever in volumes and value since the open tender policy was implemented by Petrobras.
Market Size and Forecast
-
Market Size in 2026E: USD 3.60 Billion
-
Market Size by 2035: USD 5.04 Billion
-
CAGR: 3.80% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On Drill Pipe Market - Request Free Sample Report
Drill Pipe Market Trends
-
Growing digitally integrated supply chain models are streamlining tubular delivery, providing pipe inspected and ready-to-run directly to the rig site.
-
Rising demand for lightweight, high-strength drill pipes is driven by material science innovations including carbon fiber composites and enhanced steel alloys.
-
Expanding dope-free connection solutions are enhancing safety in the rig's red zone, one of the industry's highest-risk operational areas.
-
Increasing adoption of digital traceability tools, including full tube-level tracking systems, is streamlining installation and inventory operations.
-
Growing exploration of untapped oil reserves and unconventional resources, including shale and tight gas, continues to expand drilling program scope.
U.S. Drill Pipe Market Outlook
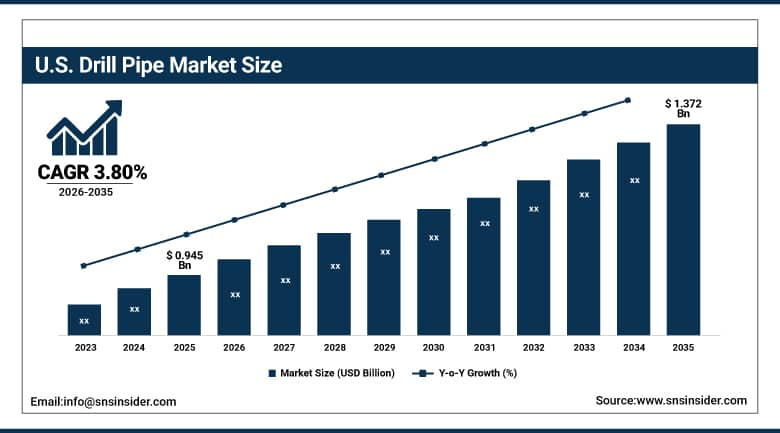
The U.S. Drill Pipe Market was valued at USD 0.945 Billion in 2025 and is projected to reach USD 1.372 Billion by 2035, growing at a CAGR of 3.80% during 2026-2035.
Rising domestic exploration and production activity, combined with growing unconventional shale and tight gas drilling programs, continues to support robust market growth across the United States. Leading manufacturers continue to expand premium connection and mill-to-well digital supply models addressing operator demand for reduced third-party staging and faster rig deployment. Growing gas drilling activity, partially offsetting weaker oil price-driven activity, continues to reinforce sustained domestic drill pipe demand nationwide.
Tenaris celebrated its tenth anniversary of Rig Direct in the US in 2025, which was an approach that combined digital integration from the mill through the well for OCTG pipe and fittings, and this had continued to evolve in response to the changing industry requirements, reflecting the ongoing move towards digitally integrated and efficient delivery systems in the domestic tubular chain.
Drill Pipe Market Segment Analysis
-
By Grade, API Grade led the Drill Pipe Market with a 51.70% share in 2025, while Premium Grade is the fastest-growing grade segment with a CAGR of 6.34% from 2026-2035.
-
By Material, Steel led the Drill Pipe Market with a 43.70% share in 2025, while Premium Alloy & High-Strength Steel is the fastest-growing material segment with a CAGR of 5.50% from 2026-2035.
-
By Application, Onshore led the Drill Pipe Market with a 56.80% share in 2025, while Offshore is the fastest-growing application segment with a CAGR of 6.50% from 2026-2035.
-
By End User, Oil & Gas Exploration led the Drill Pipe Market with a 62.60% share in 2025, while Geothermal is the fastest-growing end user segment with a CAGR of 6.80% from 2026-2035.
By Grade, API Grade Dominated the Market While Premium Grade Is the Fastest-Growing Segment
The API Grade category was the largest revenue generator for the Drill Pipe Market in 2025 at 51.70%, owing to the well-established standardized nature and wide compatibility of API drill pipe for conventional onshore drilling in drilling areas around the globe. The API graded drill pipe continues to provide operators effective performance for standard drilling projects and hence holds the top spot within the drill pipe market due to its extensive use in easily accessible drilling areas.
The Premium Grade category will exhibit the fastest growth CAGR of 6.34% for the period between 2026 and 2035, owing to requirements for superior performance and robustness in deep water and high pressure conditions. Improved connections and materials would ensure quicker drilling operations and reduced downtime, and this category is likely to grow rapidly in future with increasing preference for premium grade pipes that can function in deep water and ultra-deep water exploration.
By Material, Steel Dominated the Market While Premium Alloy & High-Strength Steel Is the Fastest-Growing Segment
The Steel segment dominated the Drill Pipe Market with a market share of 43.70% in 2025 due to the cost efficiency and mechanical reliability of conventional steel in almost all drilling operations globally. Steel drill pipes still boast the most developed manufacturing scale and supply chain infrastructure, thereby helping maintain the superiority of this material in the overall drill pipe market despite an increasing demand for high-end alloy drill pipes.
Premium Alloy & High-Strength Steel is anticipated to witness the fastest CAGR of 5.50% over the forecast period of 2026-2035 due to a rising preference for light and strong drill pipes thanks to advancements in the field of material science such as carbon fiber composites and improved steel alloys. The metallurgical and anti-corrosive properties of such products increase drilling efficiency, robustness, and safety, thus supporting the growth of the segment in excess of that of steel drill pipe.
By Application, Onshore Dominated the Market While Offshore Is the Fastest-Growing Segment
The Onshore category was the leading category of the Drill Pipe Market and accounted for a share of 56.80% in terms of revenue in 2025. The reliability of the onshore category coupled with its proven technology in easily available terrains contributed to its leading position in the drill pipe market. It is best suited for traditional oil and gas production and thus has an increasing demand for conventional pipes in all major parts of the world.
The Offshore category is estimated to exhibit the fastest CAGR of 6.50% during the forecast period 2026-2035 due to the rising investments for ultra-deep offshore drilling and adoption of technological advancements to make complex deepwater drilling operations easy. Rising developments of deepwater and presalt fields, especially in Brazil's offshore basins, contribute to the above average growth of the offshore category.
By End User, Oil & Gas Exploration Dominated the Market While Geothermal Is the Fastest-Growing Segment
Oil & Gas Exploration was the largest Drill Pipe Market shareholder in 2025, with a revenue share of 62.60%, based on the large scope of exploration and production activities that require significant drill pipe purchases for conventional and unconventional reservoir developments. Global unexplored oil reserve expansion and an increasing number of recoverable reserves will further enhance the oil and gas exploration dominance in the overall drill pipe market.
The Geothermal Developers and Specialty Users will be the fastest-growing segments with a CAGR of 6.80% for the forecast period 2026-2035, based on the demand for special drill pipe in geothermal wells that can withstand high temperatures. Geothermal energy development will further increase the growth of this segment, which outperforms conventional oil and gas exploration applications.
Regional Analysis
|
Region |
Country |
Share (2025) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
22.80% |
|
Asia Pacific |
China |
36.60% |
|
Middle East & Africa |
Saudi Arabia |
32.60% |
|
Latin America |
Brazil |
26.40% |
North America Drill Pipe Market Insights
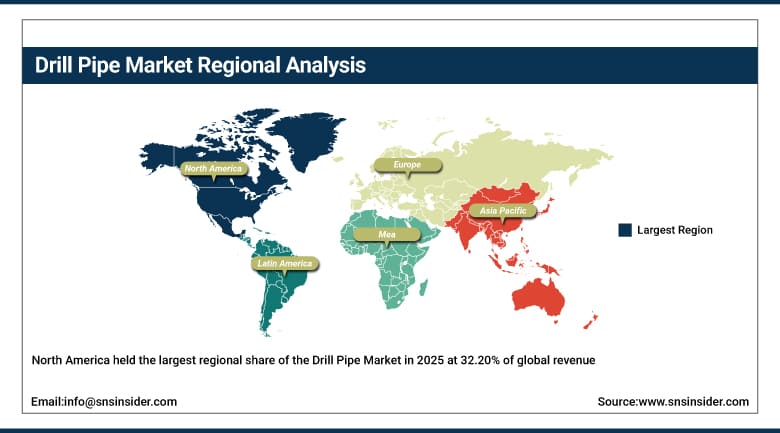
North America held the largest regional share of the Drill Pipe Market in 2025 at 32.20% of global revenue, driven by extensive unconventional shale and tight gas drilling activity alongside a dense concentration of leading drill pipe manufacturers headquartered across the region. Continued investment in upstream exploration and production, reinforced by digitally integrated mill-to-well supply models, continues to reinforce the region's leadership position.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its large domestic drilling program base and concentration of leading tubular goods manufacturers. Canada is contributing to regional growth through steady oil sands and conventional drilling activity, supported by growing demand for premium-grade drill pipe across its national energy sector.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Drill Pipe Market Insights
Europe made up an important share of the Global Drill Pipe Market in 2025 due to North Sea offshore drilling operations, as well as presence of large numbers of premium tubulars manufacturers in the region. The increasing trend of geothermal energy projects further strengthens regional demand for specific drill pipes in key European markets.
Germany was the leader among European countries with a regional share of 22.80% in 2025 due to its advanced manufacturing sector and large presence of steel and alloys manufacturing firms in the region. Norway, France, and UK are also making valuable contributions to the growth of the region, aided by North Sea offshore drilling operations.
Asia Pacific Drill Pipe Market Insights
Asia Pacific is expected to be the fastest growing market during the forecast period 2026-2035 owing to increasing activities of oil and gas exploration and initiatives taken by governments to increase production of hydrocarbons in China, India, and Southeast Asia. The energy ministry of Indonesia has announced its second round of bidding for exploration blocks that hold high hydrocarbon potential.
China held around 36.60% of the Asia Pacific market in 2025 due to an increasing number of drilling projects in the country and increasing production capacity of tubular products in the country. India, Indonesia, and Malaysia are also playing a significant role in the growth of the region. Indonesia is making a huge contribution due to new exploration blocks that hold high oil equivalent potential.
Middle East & Africa and Latin America Drill Pipe Market Insights
The Middle East & Africa region is witnessing consistent growth owing to the investment made in drilling programs by large national oil companies in the Gulf region countries. The Latin America region is gaining from the rising presalt deepwater developments in the region with Brazil leading in offshore drilling owing to its large base of production.
In 2025, Saudi Arabia emerged as the market leader in the Middle East & Africa with a regional share of 32.60%, backed by huge investment in drilling programs and expansion in deepwater development projects. Brazil captured a regional share of 26.40% in the Latin America market in 2025, with Mexico making contributions to the regional growth through offshore drilling projects.
Market Dynamics
Growth Drivers: Exploration Investment and Unconventional Resource Development Driving Market Growth
The Drill Pipe Market is being driven primarily by rising oil and gas exploration, rapid technological advancements, increasing demand for unconventional energy resources, and the need for deepwater drilling capability. The expansion of untapped oil reserves around the world represents a primary factor driving market growth, while rising numbers of recoverable reserves and stringent regulations to maintain energy security continue to provide sustained momentum for drill pipe demand.
Digital integration in supply chains continues to improve the efficiency of delivering tubulars by bringing pipes that are ready to use to the rig location. The need for light but strong drill pipes is being pushed further by developments in material sciences, such as carbon fiber materials and improved steel alloys. There has been increased investment in dope-free connections to ensure the safety of high-risk drilling operations.
Restraints: Raw Material Price Volatility and Environmental Regulation Limiting Market Expansion
Even with positive underlying demand factors, there are significant barriers posed by price volatility of raw materials, such as steel and special alloys, that could squeeze profit margins for the manufacturer and make pricing difficult in the long run. Environmental policies affecting the process of drilling are increasing compliance difficulties and costs, especially with rising emissions and safety requirements for major production areas.
Disruptions within the supply chain have delayed considerable portions of annual shipments, thus disrupting the drilling plans of companies relying on their timely delivery of tubular goods. Increased competition among manufacturers is another issue due to the introduction of tariffs for the use of steel, which is increasingly becoming a problem due to the growing number of competitors.
Opportunities: Deepwater Technology Innovation and Digital Traceability Creating New Growth Avenues
Substantial opportunity exists in continued development of premium-grade drill pipe capable of operating in deep-water and ultra-deep-water explorations and challenging geological terrains. Manufacturers that successfully commercialize advanced connection technology and corrosion-resistant materials stand to capture significant share of category growth as offshore exploration activity continues expanding across major global basins.
Growing digital traceability tool adoption, including full tube-level tracking systems, presents a further significant growth avenue, as operators increasingly demand streamlined installation and inventory operations. Expanding unconventional resource development, including shale and tight gas exploration, across emerging markets in Asia Pacific and Latin America also represents meaningful untapped opportunity for drill pipe manufacturers.
Recent Developments:
-
2025: Vallourec was awarded a major contract by Petrobras worth up to USD 1 billion to supply offshore OCTG products and services from 2026 to 2029.
-
2025: Tenaris won a contract for Mexico's first deepwater oil development, supplying pipe products for the project.
-
2025: Vallourec and Petrobras jointly developed the Submagnético Free Flow system, applying a magnetic field on produced fluids to reduce inorganic scaling on production strings.
-
2026: Equinor awarded Vallourec a five-year contract to supply premium tubes, connections, and services to its offshore Brazil presalt Campos Basin projects.
Drill Pipe Market key players are:
-
Vallourec S.A.
-
TMK Group
-
Sumitomo Corporation
-
Nippon Steel Corporation
-
ArcelorMittal S.A.
-
National Oilwell Varco, Inc. (NOV Inc.)
-
Tenaris S.A.
-
Hilong Group of Companies
-
Jindal Saw Ltd.
-
Weatherford International plc
-
Oil Country Tubular Ltd.
-
PetroMaterials Corporation
-
Texas Steel Conversion, Inc.
-
Tejas Tubular Products, Inc.
-
Grant Prideco (NOV)
-
Baoji Petroleum Steel Pipe Co., Ltd.
-
U.S. Steel Tubular Products
-
TMK IPSCO
-
American Iron & Steel
-
Prime Drilling GmbH
Drill Pipe Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.47 Billion |
| Market Size by 2035 | USD 5.04 Billion |
| CAGR | CAGR of 3.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Grade (API Grade, Premium Grade) • By Material (Steel, Premium Alloy & High-Strength Steel) • By Application (Onshore, Offshore) • By End User (Oil & Gas Exploration, Mining, Geothermal) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Vallourec S.A., TMK Group, Sumitomo Corporation, Nippon Steel Corporation, ArcelorMittal S.A., National Oilwell Varco, Inc. (NOV Inc.), Tenaris S.A., Hilong Group of Companies, Jindal Saw Ltd., Weatherford International plc, Oil Country Tubular Ltd., PetroMaterials Corporation, Texas Steel Conversion, Inc., Tejas Tubular Products, Inc., Grant Prideco (NOV), Baoji Petroleum Steel Pipe Co., Ltd., U.S. Steel Tubular Products, TMK IPSCO, American Iron & Steel, Prime Drilling GmbH |
Frequently Asked Questions
The Drill Pipe Market is expected to grow at a CAGR of 3.80% from 2026 to 2035.
The Drill Pipe Market was valued at USD 3.47 Billion in 2025.
The market is driven by rising oil and gas exploration, rapid technological advancements, increasing demand for unconventional energy resources, and the need for deepwater drilling.
The API Grade segment dominated the Drill Pipe Market in 2025, accounting for approximately 51.70% market share.
The North America region dominated the Drill Pipe Market in 2025, accounting for approximately 32.20% market share.
