
Drone Services Market Report Scope & Overview:
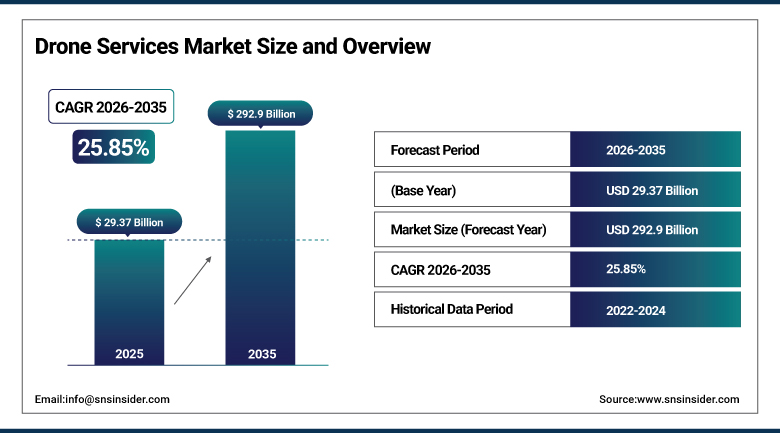
The Drone Services Market was valued at USD 29.37 Billion in 2025 and is expected to reach USD 292.9 Billion by 2035, growing at a CAGR of 25.85% from 2026-2035.
The market for drone services is constantly developing to provide a variety of services that cover remotely controlled and autonomous flying unmanned aerial vehicles. The integration of flight plan algorithms that use software into drones' built-in software makes it a vital element in the following industries: agriculture, insurance, construction, marine, aviation, oil and gas, mining, and infrastructure development. The commercial use of drones involves performing various tasks, such as search and rescue, delivery of packages, inspection of industrial facilities, assembling images, pesticide spraying, and delivering health care products to distant areas. The development of regulatory frameworks of drone services at the level of beyond-visual-line-of-sight and advanced autonomous flight technology is increasing the list of commercially viable uses of drones.
Uber Technologies and Zipline announced a strategic partnership in August 2026 targeting one million drone deliveries daily by the end of 2029, with drone delivery on Uber Eats set to launch across existing Zipline markets and expand into dozens of additional U.S. cities. Uber will also make a strategic investment in Zipline as part of the partnership, reinforcing a long-term collaboration aimed at accelerating the scale of autonomous drone delivery.
To Get more information Drone Services Market - Request Free Sample Report
Drone Services Market Trends
-
Rising adoption of beyond-visual-line-of-sight regulatory exemptions enabling expanded commercial drone delivery operations.
-
Growing integration of artificial intelligence-driven analytics enhancing infrastructure inspection and site audit capability.
-
Expanding deployment of Drone-as-First-Responder programs supporting municipal public safety and incident assessment applications.
-
Increasing adoption of hybrid VTOL drone platforms combining vertical takeoff capability with extended fixed-wing range.
-
Rising strategic partnerships between drone service providers and established logistics and technology platforms.
-
Growing utilization of drone-based surveillance and inspection services across defense and border security applications.
U.S. Drone Services Market Outlook
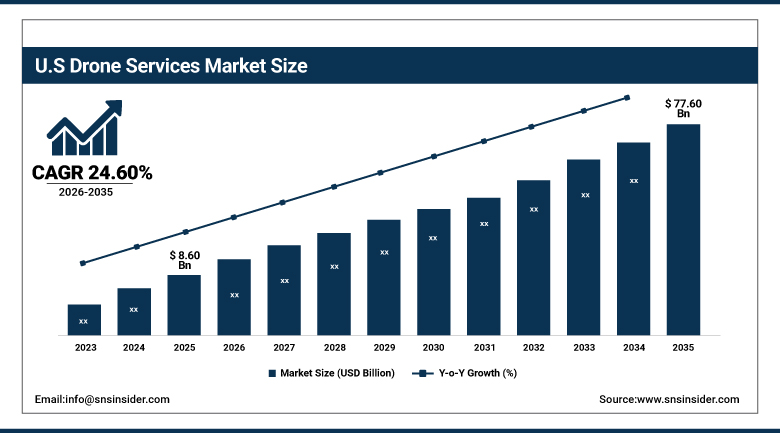
The U.S. Drone Services Market was valued at USD 8.60 Billion in 2025 and is expected to reach USD 77.60 Billion by 2035, growing at a CAGR of 24.60% from 2026-2035.
The U.S. Drone Services Market remains positively influenced by the existence of key original equipment manufacturers, positive regulatory developments from the Federal Aviation Administration, as well as investment in delivery and inspection applications from established technology, defense, and logistics companies. The rule-making of the Federal Aviation Administration known as Part 108 and anticipated to be released early in 2026, is expected to provide standardization of beyond visual line-of-sight operation guidelines, with current waiver numbers indicating the fast growth in scale of operations for expanded drone operations in North America. Utility companies continue to receive ROI through the use of drones for infrastructure inspection services, while municipal Drone as First Responder program applications to the Federal Aviation Administration numbered 300 by mid-2025.
Zipline, headquartered in South San Francisco, California, raised USD 600 million in new funding in January 2026, having surpassed two million total commercial drone deliveries with U.S. delivery volumes growing approximately 15% week-over-week over the preceding seven months. The company subsequently secured an additional USD 200 million in March 2026 to fund continued drone delivery expansion, with deliveries beginning in Houston and Phoenix in early 2026 ahead of further expansion across additional U.S. states throughout the year.
Drone Services Market Segment Analysis
-
By Service Type, the Drone Platform Services segment dominated the Drone Services Market with approximately 43.60% share in 2025, while the Data Acquisition & Analytics segment is the fastest growing with a CAGR of approximately 27.60%.
-
By Application, the Surveillance & Inspection segment dominated the Drone Services Market with approximately 32.60% share in 2025, and is also the fastest growing with a CAGR of approximately 28.60%.
-
By End-User, the Agriculture segment dominated the Drone Services Market with approximately 26.60% share in 2025, while the Infrastructure & Construction segment is the fastest growing with a CAGR of approximately 30.14%.
-
By Drone Type, the Rotary-Wing segment dominated the Drone Services Market with approximately 54.60% share in 2025, while the Hybrid VTOL segment is the fastest growing with a CAGR of approximately 29.60%.
By Service Type, Drone Platform Services Dominates the Drone Services Market and Data Acquisition & Analytics Grows Fastest
The drone platform service accounts for the largest market share of the drone services market, which includes the critical operational framework including flight software, operational infrastructure, and the hardware platform that serves as the base for the drone services value chain. This category has consistently accounted for the largest contribution to the market revenue as the fundamental platform that delivers other service categories in downstream operations in agriculture, infrastructure, and logistics.
The data acquisition and analytics services is the fastest growing drone service type, given the increasing trend of incorporation of AI-driven analytics into drone services, thereby delivering more value through data analytics beyond simple flight capabilities. The need for automation of mission execution and analysis, rather than imagery only, has been on the rise in the enterprise segment, thus making this category grow at a fast pace in the drone services market.
By Application, Surveillance & Inspection Dominates the Drone Services Market and Also Grows Fastest
The surveillance and inspection application represents the largest application share, owing to the popularity of the technology in infrastructure inspection, utility asset management, and industrial facilities assessment applications, which still provide tangible benefits in terms of cost savings and safety improvement in comparison to manual inspection procedures. The significant size of the application comes from the variety of industries that still depend on the use of drones for inspection purposes, including energy, construction, and telecommunications sectors.
Surveillance and inspection represents the fastest-growing application as well, since ongoing developments in automated site auditing capabilities driven by AI continue to expand the number of potential applications within the infrastructure and construction sector.
By End-User, Agriculture Dominates the Drone Services Market and Infrastructure & Construction Grows Fastest
Agriculture is the largest end-user segment, owing to the increasing use of drones in crop monitoring, irrigation control, and yield analysis, which helps in optimizing resource utilization and increasing productivity in agriculture. The large-scale activity in agriculture, along with the proven cost-saving capability of drone technology and improved yield results due to it, continues to make agriculture the largest end-user segment for drone service providers.
Infrastructure and construction is the fastest growing end-user segment, owing to the increasing use of AI-powered site audits in construction projects. The increasing spending on infrastructure development and the increasing regulatory support for commercial drone operations continue to drive strong above-market growth in the segment of infrastructure and construction.
By Drone Type, Rotary-Wing Dominates the Drone Services Market and Hybrid VTOL Grows Fastest
Rotary-wing drones command the largest share by drone type, offering the operational versatility and precise hovering capability required across the majority of inspection, surveillance, and agricultural monitoring applications that constitute the bulk of current commercial drone service demand. This versatility across a broad range of use cases continues to sustain rotary-wing platforms' position as the largest and most widely deployed drone type across the broader services market.
Hybrid vertical takeoff and landing platforms represent the fastest-growing drone type, combining rotary-wing vertical takeoff capability with fixed-wing flight efficiency to deliver extended range suited to longer-distance delivery and mapping applications. As commercial drone delivery operations continue scaling toward genuine mass-market deployment, hybrid VTOL platforms' combination of operational flexibility and extended range positions this drone type for sustained above-market growth through the forecast period.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Middle East & Africa |
United Arab Emirates |
27.60% |
|
Latin America |
Brazil |
24.60% |
North America Drone Services Market Insights
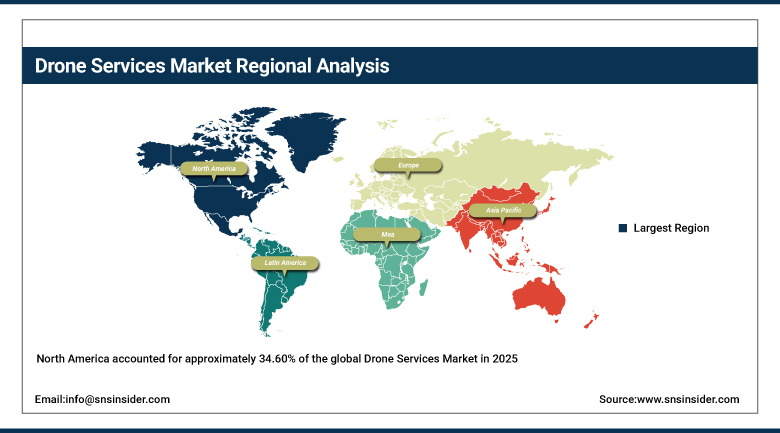
North America accounted for approximately 34.60% of the global Drone Services Market in 2025, making it the largest regional market, supported by the presence of major original equipment manufacturers, favorable regulatory frameworks from the Federal Aviation Administration, and substantial investment in research and development of next-generation drone technology. The United States anchors regional demand, home to leading drone delivery, inspection, and platform service providers continuing to scale commercial operations across an expanding range of end-use applications.
Canada is contributing incremental regional demand as its own regulatory framework and commercial drone service sector continue to develop. Continued domestic investment in beyond-visual-line-of-sight infrastructure and expanded regulatory approval is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Drone Services Market Insights
Asia Pacific is currently the fastest growing region due to increasing adoption of commercial drones in agriculture, infrastructure and logistics operations in China, India and other key economies in the region. The strong local presence of drones and the rapid growth of the commercial services market in China is one of the key drivers of regional demand growth in diverse end-use markets.
India is adding value through its regulatory structure for commercial drone operations as well as increased adoption in agriculture and infrastructure end-uses. Japan and South Korea add scale through their technology industries incorporating drones into their commercial operations, cementing Asia Pacific's place as the fastest growing region in the forecast period.
Europe Drone Services Market Insights
Europe represents a significant share of the global Drone Services Market, with regional demand reinforced by expanding border surveillance and inspection applications amid an evolving regional security environment. Continued utilization of drone-based surveillance and inspection capability for tracking and monitoring purposes continues to support sustained regional demand for commercial drone services across multiple applications.
Germany, France, and the United Kingdom contribute significant regional demand as national regulatory frameworks continue to extend commercial drone operation approval across an expanding range of applications. Regional service providers continue investing in expanded operational capability to meet growing demand across infrastructure inspection and agricultural monitoring applications.
MEA & Latin America Drone Services Market Insights
The Middle East & Africa market is supported by sustained infrastructure and energy sector investment across the United Arab Emirates and Saudi Arabia, as regional governments continue prioritizing advanced technology adoption across oil and gas, construction, and security applications. Regional drone service providers continue expanding operational capability to serve growing demand across the broader Gulf region.
Latin America's market remains at an earlier stage of development, with Brazil contributing incremental growth as regional agricultural and infrastructure sector adoption continues to expand. Regional governments continue evaluating expanded regulatory frameworks to support broader commercial drone service adoption, though the market across the region remains considerably earlier-stage relative to more established markets.
Market Dynamics
Growth Drivers: Expanding Commercial Applications and Regulatory Framework Development
Growing applications of drones across diverse industries represent the primary driver of Drone Services Market growth, as expanding use cases spanning agriculture, insurance, construction, marine operations, aviation, oil and gas, mining, and infrastructure continue to broaden the addressable market for commercial drone service providers. Rising utilization of drones for crop health assessment, soil monitoring, and precision agriculture continues to reinforce sustained demand growth across the agricultural sector specifically.
Continued maturation of beyond-visual-line-of-sight regulatory frameworks represents a second major growth driver, as expanded operating approvals from aviation authorities worldwide continue to unlock previously constrained commercial applications including long-distance delivery and expanded-range inspection services. The escalating utilization of drones for border surveillance and inspection applications amid evolving regional security environments continues to reinforce sustained demand across the broader drone services market.
Restraints: Regulatory Complexity and Cybersecurity Concerns
Complexity of regulation is one of the restraints affecting the growth of the industry due to the ongoing process of incorporating drones into business processes and the necessity of overcoming new aviation safety regulations, as well as the issues related to air traffic control and specific requirements for the operation of drones, which may affect the expansion of their commercial service.
Issues related to cybersecurity are another restraint affecting the development of the industry because of the need to ensure the safe operation of drone systems and the protection of information that is transmitted. The need to ensure secure data transmission leads to additional expenses for service providers.
Opportunities: Autonomous Delivery Scaling and AI-Driven Analytics Integration
Continued scaling of autonomous drone delivery infrastructure represents a substantial opportunity, as service providers that can successfully expand beyond-visual-line-of-sight delivery capability across additional metropolitan markets are positioned to capture significant new demand as regulatory frameworks continue to mature and consumer adoption accelerates. Strategic partnerships between drone delivery providers and established logistics and technology platforms continue to reinforce the pace at which autonomous delivery infrastructure can scale toward genuine mass-market deployment.
The incorporation of artificial intelligence-powered analytics into drone services can open yet another way of growing the business, as service providers that will be able to provide automated missions along with real-time analytics capabilities will be able to attract those enterprise customers who want data-driven solutions rather than just the capture of raw images. Service providers that will be able to combine successful drone flights with high-end analytics capabilities will be ready to attract customers in various industries.
Recent Developments:
-
In August 2026, Uber and Zipline announced a strategic partnership to scale autonomous drone delivery through Uber Eats across the U.S. The companies are targeting expansion into dozens of U.S. cities, with first deployments planned for later in 2026. Uber also announced a strategic investment in Zipline.
-
In July 2026, Manna began its U.S. expansion with a full-scale drone delivery operation in Tulsa, Oklahoma. The company plans to establish up to 40 local operating bases by mid-2027 and is targeting delivery coverage for approximately 90% of Tulsa residents. Manna already has more than 300,000 completed drone deliveries, primarily in Ireland.
-
In June 2026, Airbound partnered with the Andhra Pradesh Drone Corporation (APDC) to develop a large-scale drone delivery network in the Amaravati Capital Region. The partnership targets up to 10,000 drone flights per day within the following year, supporting the development of drone-enabled logistics services in India.
-
In May 2026, Matternet completed its merger transaction and became a wholly owned subsidiary of the newly named Matternet, Inc. The company is expanding its commercial drone delivery model across healthcare, logistics, and home-delivery applications, while also pursuing partnerships with logistics operators and enterprise customers.
-
In May 2025, AgEagle Aerial Systems entered a strategic alliance with India-based Vyom Drones to support the manufacture and sale of AgEagle's eBee X drones in India. The agreement also includes service and maintenance training, targeting agricultural, surveying, civil, and commercial drone applications.
Drone Services Market Key Players
-
DJI Innovations
-
Aerodyne Group
-
AgEagle Aerial Systems Inc.
-
Cyberhawk Innovations Limited
-
DroneDeploy, Inc.
-
Field Group AS
-
Guangzhou XAG Co., Ltd.
-
Identified Technologies
-
iFlight Innovation Technology Co., Ltd.
-
Matternet, Inc.
-
Phoenix Drone Services
-
Safe Pro Group Inc.
-
Sharper Shape, Inc.
-
Skydio, Inc.
-
Skyports Limited
-
Terra Drone Corporation
-
Zipline International Inc.
-
PrecisionHawk, Inc.
-
DroneUp, LLC
-
Wing Aviation LLC
Drone Services Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 29.37 Billion |
| Market Size by 2035 | USD 292.9 Billion |
| CAGR | CAGR of 25.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Service Type (Drone Platform Services, Drone MRO Services, Drone Training & Simulation Services, and Data Acquisition & Analytics) • by Application (Surveillance & Inspection, Aerial Photography, Product Delivery, and Mapping & Surveying) • by End-User (Agriculture, Infrastructure & Construction, Oil & Gas, and Logistics) •by Drone Type (Rotary-Wing, Fixed-Wing, and Hybrid VTOL) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | DJI Innovations, Aerodyne Group, AgEagle Aerial Systems Inc., Cyberhawk Innovations Limited, DroneDeploy, Inc., Field Group AS, Guangzhou XAG Co., Ltd., Identified Technologies, iFlight Innovation Technology Co., Ltd., Matternet, Inc., Phoenix Drone Services, Safe Pro Group Inc., Sharper Shape, Inc., Skydio, Inc., Skyports Limited, Terra Drone Corporation, Zipline International Inc., PrecisionHawk, Inc., DroneUp, LLC, Wing Aviation LLC |

Frequently Asked Questions
Key players include DJI Innovations, Aerodyne Group, AgEagle Aerial Systems Inc., DroneDeploy, Inc., Skydio, Inc., Zipline International Inc., and Terra Drone Corporation, among other commercial drone service providers.
Continued scaling of autonomous drone delivery infrastructure and continued integration of artificial intelligence-driven analytics into drone service offerings represent the primary opportunities.
Growth is primarily driven by growing applications of drones across diverse industries combined with continued maturation of beyond-visual-line-of-sight regulatory frameworks.
By Service Type, Drone Platform Services dominated the market with approximately 43.60% share in 2025, reflecting its role as the foundational infrastructure layer supporting downstream drone service applications.
North America dominated the market with approximately 34.60% share in 2025, supported by the presence of major original equipment manufacturers and favorable Federal Aviation Administration regulatory developments.
