
Aircraft Micro Turbine Engines Market Report Scope & Overview:
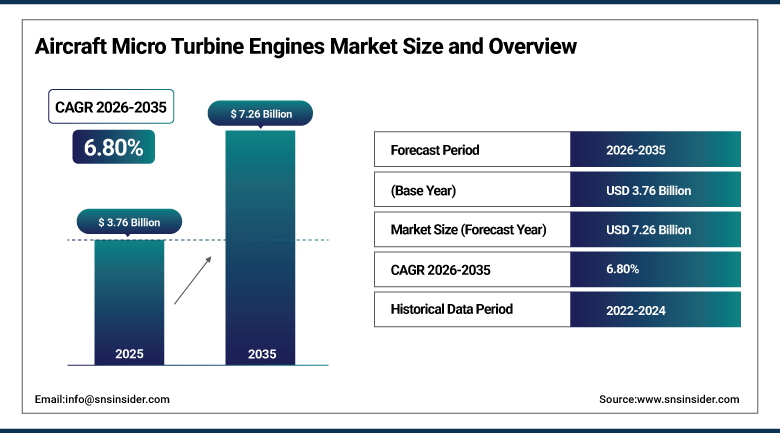
The Aircraft Micro Turbine Engines Market was valued at USD 3.76 Billion in 2025 and is expected to reach USD 7.26 Billion by 2035, growing at a CAGR of 6.80% from 2026-2035.
U.S. Market for Aircraft Micro Turbine Engine Growth is bolstered by ongoing defense modernization expenditures, fast-tracked development of collaborative combat and autonomous platforms, and the presence of top turbine engine and defense companies in the nation. Domestic demand is also driven by ongoing funding for unmanned aerial system propulsion systems by way of several parallel programs that provide an ecosystem of both legacy and new vendors. Increasing focus on hybrid-electric propulsion solutions for advanced air mobility platforms helps drive the demand for turbine generator technology.
In July 2024, GE Aerospace and Kratos Turbine Technologies, a division of Kratos Defense & Security Solutions, signed a memorandum of understanding to partner on the development and production of small, affordable engines capable of powering unmanned aerial systems, collaborative combat aircraft, and similar autonomous platforms. The partnership builds on an existing joint development agreement encompassing full-scale engine production, reflecting continued industry collaboration to meet accelerating defense demand for compact, cost-effective turbine propulsion.
To Get more information Aircraft Micro Turbine Engines Market - Request Free Sample Report
Aircraft Micro Turbine Engines Market Trends
- Rising defense investment in unmanned aerial systems and collaborative combat aircraft driving turbine demand.
- Growing development of hybrid-electric turbogenerator systems for advanced air mobility applications.
- Continued advancement of lightweight materials and additive manufacturing for turbine components.
- Increasing emphasis on fuel flexibility and ultra-low emissions engine technology.
- Expanding use of micro turbines as auxiliary power systems to reduce onboard fuel consumption.
U.S. Aircraft Micro Turbine Engines Market Outlook
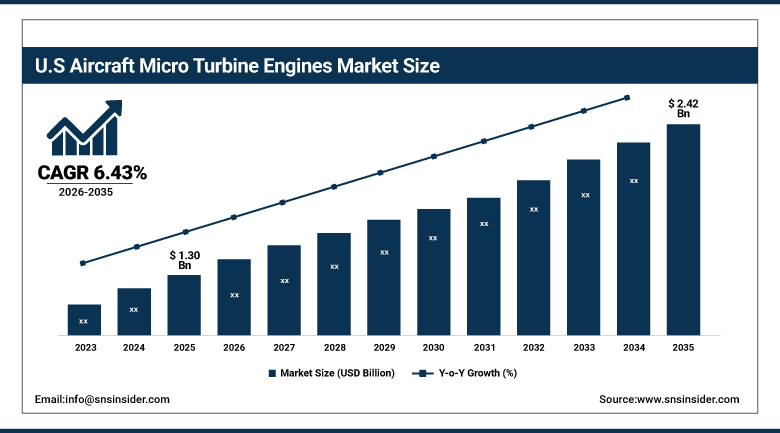
The U.S. Aircraft Micro Turbine Engines Market was valued at USD 1.30 Billion in 2025 and is expected to reach USD 2.42 Billion by 2035, growing at a CAGR of 6.43% from 2026-2035.
The U.S. Aircraft Micro Turbine Engines Market growth continues to be reinforced by sustained defense modernization spending, accelerating development of collaborative combat aircraft and autonomous platform programs, and the country's concentration of leading turbine engine manufacturers and defense contractors. Domestic demand also benefits from continued government investment in unmanned aerial system propulsion under multiple parallel development programs, supporting a diverse vendor base of both established primes and newer entrants. Growing interest in hybrid-electric propulsion for advanced air mobility platforms further supports demand for compact, efficient turbogenerator technology across both defense and emerging commercial applications.
In February 2026, the U.S. Air Force awarded Honeywell a prototype contract to develop a propulsion system based on its SkyShot 1600 engine for the service's Collaborative Combat Aircraft program and other autonomous platforms. The award, issued under the Air Force's Propulsion Consortium Initiative 2.0, supports a modular, scalable engine design capable of configuring as either a turbojet or turbofan, reflecting continued domestic investment in next-generation propulsion for autonomous combat platforms.
Aircraft Micro Turbine Engines Market Segment Analysis
- By Engine Type, the Turboshaft segment dominated the Aircraft Micro Turbine Engines Market with approximately 58.50% share in 2025, while the Turbojet segment is the fastest growing with a CAGR of approximately 8.60%.
- By Platform, the Commercial Aviation segment dominated the Aircraft Micro Turbine Engines Market with approximately 42.50% share in 2025, while the UAV/UAS segment is the fastest growing with a CAGR of approximately 9.80%.
- By Application, the Main Propulsion segment dominated the Aircraft Micro Turbine Engines Market with approximately 64.50% share in 2025, while the Auxiliary Power Unit segment is the fastest growing with a CAGR of approximately 8.20%.
- By Sales Channel, the OEM segment dominated the Aircraft Micro Turbine Engines Market with approximately 71.50% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 8.40%.
By Engine Type, Turboshaft dominates and Turbojet grows fastest
The turboshaft engines have continued to dominate the market segments of Aircraft Micro Turbine Engines Market as they have found wide application in rotorcrafts, APUs, and various other small aircraft that require shaft power continuously. The turboshaft engines' segment continues to benefit from the reliability offered by the engines for years in helicopter and small fixed-wing applications leading to continued specification in commercial and military applications.
Turbojet engines have emerged as the fastest-growing engine type segment due to the increasing requirement for a simple and compact design with better thrust-to-weight ratio in unmanned aerial systems and collaborative combat aircraft as compared to the fuel-efficient engines such as turbofans. The turbojet engine's segment involves the development of modular and scalable engines that can be configured to work either as a turbojet or turbofan.
By Platform, Commercial Aviation dominates and UAV/UAS grows fastest
Commercial Aviation Platform Segment continues to dominate in the Aircraft Micro Turbines Engines Market due to consistent demand for small-sized auxiliary power units as well as small propulsion engines in business jets and regional aircraft. This is attributed to the presence of a stable customer base in the field of commercial aviation that requires micro turbines to generate power and provide some propelling capabilities.
The UAV/UAS Platform Segment is fast becoming one of the leading platform segments in the market owing to the increasing spending in the development of unmanned aerial systems and collaborative combat aircraft that need compact and inexpensive turbine propulsion systems. The main characteristic of this segment involves developing lightweight and affordable engine designs for expendable and semi-expendable autonomous platforms.
By Application, Main Propulsion dominates and Auxiliary Power Unit grows fastest
Main propulsion installations will continue to account for the leading share of the installation segment in the Aircraft Micro Turbine Engines Market, as micro turbines act as the primary propulsion systems in smaller aircraft, helicopters, and unmanned aerial systems. The growing demand for unmanned aerial vehicles, where micro turbine engines serve as the sole propulsion system and not an additional power system, is aiding this market segment.
The installation segment for Auxiliary Power Units has been identified as the fastest growing one in the Aircraft Micro Turbine Engines Market, due to the rising utilization of micro turbines as auxiliary power sources as a measure to cut back operational costs by avoiding the use of main engines for generating ground power. This installation segment caters to power-efficient and lightweight power systems for delivering auxiliary power independent of the propulsion system.
By Sales Channel, OEM dominates and Aftermarket grows fastest
OEM sales remain the dominant distribution channel within the Aircraft Micro Turbine Engines Market, reflecting original equipment manufacturers' position as the primary supplier of micro turbine engines integrated during initial aircraft and unmanned platform manufacturing. This segment benefits from long-term supply agreements between engine manufacturers and airframe producers, sustaining stable demand tied directly to new aircraft and unmanned platform production volumes.
The Aftermarket segment is emerging as the fastest-growing distribution channel, driven by rising demand for auxiliary power unit replacement as the global fleet of aircraft equipped with micro turbine technology continues to age and require component replacement after reaching end-of-service-life. This segment focuses on expanding maintenance, repair, and overhaul capabilities to support the growing installed base of micro turbine-equipped aircraft and unmanned platforms.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.50% |
|
Europe |
Germany |
34.60% |
|
Asia Pacific |
China |
42.80% |
|
Latin America |
Brazil |
44.90% |
|
Middle East & Africa |
Israel |
38.60% |
North America Aircraft Micro Turbine Engines Market Insights
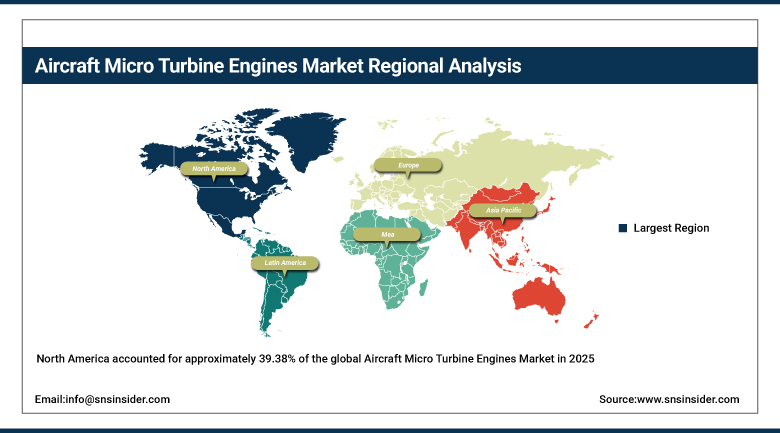
North America accounted for approximately 39.38% of the global Aircraft Micro Turbine Engines Market in 2025, reflecting the region's concentration of leading turbine engine manufacturers and substantial defense modernization spending. The United States accounts for the substantial majority of regional demand, supported by its large defense budget, extensive unmanned aerial system development programs, and presence of major aerospace propulsion companies.
Canada contributes additional regional demand through its participation in North American defense and aerospace supply chains. Continued U.S. government investment in collaborative combat aircraft and autonomous platform propulsion development further reinforces North America's position as the largest regional market for aircraft micro turbine engines.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Aircraft Micro Turbine Engines Market Insights
Europe is expected to witness the highest CAGR of about 7.90% in the Aircraft Micro Turbine Engines Market over the forecast period 2026-2035, driven by robust aerospace engineering competencies and rising focus on hybrid and advanced air mobility propulsion solutions. Germany stands out as the leading regional market player, owing to its strong presence in aerospace manufacturing industry along with engineering competencies and ongoing research & development of propulsion solutions.
United Kingdom and France add up in terms of demand contribution in the region, owing to their strong presence in defense aerospace sector along with their investments in unmanned aerial systems. The increasing development of next generation aircraft propulsion and advanced air mobility solutions is providing ample opportunities. Europe's rising investments and policies on lower emission aircraft are augmenting the demand in the region.
Asia Pacific Aircraft Micro Turbine Engines Market Insights
Asia Pacific represents a significant and expanding regional market for aircraft micro turbine engines, supported by China’s growing unmanned aerial vehicle manufacturing base and increasing defense modernization programs. China represents the largest contributor within the region, driven by substantial investments in military and commercial drone development. Expanding domestic aerospace capabilities and increasing deployment of unmanned platforms are further supporting demand for compact propulsion systems.
India and Japan contribute additional regional demand through expanding indigenous defense aerospace programs and increasing investment in unmanned aerial systems. Government initiatives aimed at strengthening domestic aerospace manufacturing and reducing dependence on imported technologies are supporting the development of regional propulsion capabilities. Continued investments in defense modernization, drone technologies, and advanced aerospace platforms are expected to reinforce Asia Pacific’s long-term market development.
MEA & Latin America Aircraft Micro Turbine Engines Market Insights
The Middle East & Africa region continues to gain strategic importance in the Aircraft Micro Turbine Engines Market, with demand concentrated in countries such as Israel, which has a well-established defense aerospace and unmanned aerial systems ecosystem supporting domestic applications and export-oriented programs. Gulf Cooperation Council markets contribute additional regional demand through increasing defense procurement, investments in aerospace capabilities, and growing interest in unmanned aerial platforms. Continued modernization of defense infrastructure and expansion of indigenous aerospace technologies are expected to support regional demand for micro turbine engines.
Latin America’s Aircraft Micro Turbine Engines Market is led by Brazil, which represents the region’s largest contributor, supported by its established aerospace manufacturing base and ongoing defense modernization initiatives. The country’s aerospace engineering capabilities and expanding development of unmanned aerial systems are creating additional demand for compact propulsion technologies. Other Latin American markets contribute smaller volumes, while gradual investment in domestic defense capabilities and unmanned aviation programs is expected to support steady regional market development.
Market Dynamics
Growth Drivers: Defense Modernization and Unmanned System Proliferation
Increased investments in development of unmanned aerial systems and collaborative combat aircraft are seen to be the key factors driving the Aircraft Micro Turbine Engines Market owing to the need for small-sized and cost-effective turbine engines that can be used in autonomous vehicles. The growth of the market is also attributed to the advantages that micro turbine engines have when it comes to cost-effectiveness and better power-to-weight ratio compared to other engines.
Another important demand generator is the growing adoption of hybrid-electric aircraft designs which are needed in advanced air mobility and regional mobility operations. The use of turbogenerators powered by micro turbine engines is becoming more widespread for such aircraft designs. Advancements in the area of materials and additive manufacturing of turbines is also contributing to the growth of the market.
Restraints: High Development Costs and Certification Complexity
The high cost of development and certification of new micro-turbine engines is one of the major constraints affecting the Aircraft Micro Turbine Engines Market. The manufacturers have to go through the process of certification of aviation safety, airworthiness, and performance, which takes much time and increases the cost of development. The major concern faced by the manufacturers is related to the development of such capability by smaller manufacturers and new market players.
The availability of inadequate infrastructure along with changing regulations for the development of hybrid-electric propulsion systems also hinders the commercial application of these engines especially in advanced air mobility segment. With the emergence of new types of technologies and continuous development of the certification standards and regulations, there arises uncertainty for the manufacturers in terms of their commercialization and investments. The exposure of manufacturers to the tariffs on aerospace parts and materials may increase the cost of manufacturing the product.
Opportunities: Advanced Air Mobility and Hybrid-Electric Propulsion Expansion
Continued development of hybrid-electric aircraft architectures for advanced air mobility presents a substantial growth opportunity for the Aircraft Micro Turbine Engines Market, as these emerging platforms require compact, efficient turbogenerator systems capable of extending range and endurance beyond what battery-electric propulsion alone can achieve. Manufacturers that can demonstrate validated, certifiable hybrid-electric turbine technology are well positioned to capture share as advanced air mobility platforms move toward commercial certification.
Rising defense investment in collaborative combat aircraft and autonomous platform programs presents a longer-term opportunity for engine manufacturers to extend micro turbine technology into new defense applications beyond traditional unmanned aerial vehicles. As multiple parallel development programs continue to advance, manufacturers with established propulsion development capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2024: Honeywell unveiled Honeywell Ensemble, the first end-to-end digital maintenance solution for Honeywell business jet turbofan engines, available through the company's propulsion Maintenance Service Plan.
- 2023: Rolls-Royce launched a new engine utilizing novel combustion technology designed to achieve ultra-low emissions, confirming its suitability for a lightweight turbogenerator system aimed at the advanced air mobility market.
- 2023: Honeywell, through The International Turbine Engine Company, signed a memorandum of understanding with AERALIS at the Paris Air Show to integrate the Honeywell/ITEC F124 engine into AERALIS' new modular aircraft platform.
Aircraft Micro Turbine Engines Market Key Players are:
- Rolls-Royce Holdings plc
- Honeywell International Inc.
- Safran S.A.
- General Electric Company
- Pratt & Whitney
- Williams International
- PBS Velka Bites
- Turbotech SAS
- Aerojet Rocketdyne Holdings, Inc.
- Kratos Defense & Security Solutions, Inc.
- AMT Netherlands B.V.
- Collins Aerospace
- Garrett Motion Inc.
- Textron Inc.
- MTU Aero Engines AG
- IHI Corporation
- Kawasaki Heavy Industries, Ltd.
- JetCat USA
- Price Induction
- Microturbo (Safran)
Aircraft Micro Turbine Engines Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.76 Billion |
| Market Size by 2035 | USD 7.26 Billion |
| CAGR | CAGR of 6.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Engine Type (Turboshaft, Turboprop, and Turbojet) • By Platform (Commercial Aviation, Military & Defense, UAV/UAS, Others) • By Application (Main Propulsion and Auxiliary Power Unit) • By Sales Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Rolls-Royce Holdings plc; Honeywell International Inc.; Safran S.A.; General Electric Company; Pratt & Whitney; Williams International; PBS Velka Bites; Turbotech SAS; Aerojet Rocketdyne Holdings, Inc.; Kratos Defense & Security Solutions, Inc.; AMT Netherlands B.V.; Collins Aerospace; Garrett Motion Inc.; Textron Inc.; MTU Aero Engines AG; IHI Corporation; Kawasaki Heavy Industries, Ltd.; JetCat USA; Price Induction; Microturbo (Safran) |
Frequently Asked Questions
Leading companies in the Aircraft Micro Turbine Engines Market include Rolls-Royce, Honeywell International, Safran, General Electric, and Pratt & Whitney, among others.
Key opportunities include continued development of hybrid-electric turbogenerator systems for advanced air mobility platforms, and rising defense investment in collaborative combat aircraft and autonomous platform programs.
Accelerating defense investment in unmanned aerial systems and collaborative combat aircraft programs, combined with growing development of hybrid-electric aircraft architectures, is the major factor driving market growth.
The Commercial Aviation segment dominated the Aircraft Micro Turbine Engines Market with approximately 42.50% share in 2025.
North America dominated the Aircraft Micro Turbine Engines Market in 2025 with approximately 39.38% share, reflecting the region's concentration of leading turbine engine manufacturers, led by the United States.
