
Dual Flap Dispensing Closure Market Report Scope & Overview:
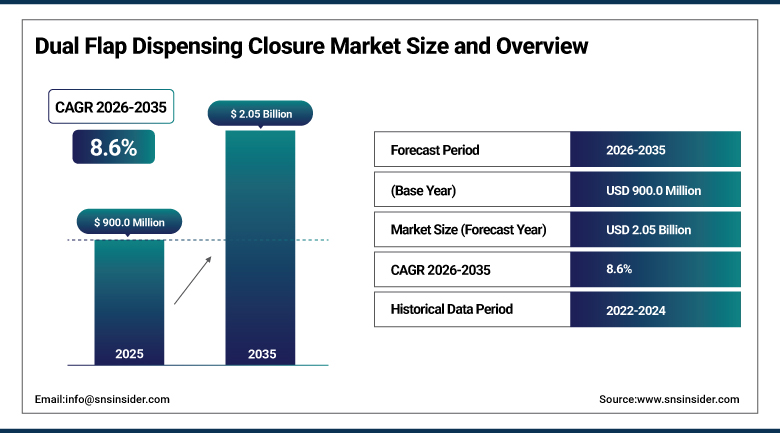
The Dual Flap Dispensing Closure Market was valued at USD 900.0 Million in 2025 and is expected to reach USD 2.05 Billion by 2035, growing at a CAGR of 8.6% from 2026–2035.
Dual flap closures use two hinged flaps, usually a large pour flap and a smaller shake flap, molded into a single cap, letting a shopper control whether they're pouring, shaking, or sprinkling a product without unscrewing anything. They show up constantly on spice jars, sugar and salt canisters, protein powder tubs, and household cleaning products, doing quiet, unglamorous work that most consumers never think twice about. Brand owners increasingly treat the closure as a real design and functionality decision rather than an afterthought bolted onto whatever container they picked first.
In 2025, AptarGroup introduced a controlled-dose dual flap closure for premium spice packaging that combines tamper-evidence with anti-spill functionality, a level of engineering sophistication that would have seemed like overkill for a spice jar cap a decade ago. The launch reflects how far dual flap closures have moved from a purely functional afterthought toward a genuine point of product differentiation that brand owners are willing to pay a premium for.
To Get more information Dual Flap Dispensing Closure Market - Request Free Sample Report
Dual Flap Dispensing Closure Market Trends
-
Mono-material closure design is gaining ground as brand owners align packaging with recyclability standards, moving away from multi-material caps that complicate recycling stream sorting.
-
E-commerce growth is pushing demand for closures with stronger seal integrity and tamper-evidence, since products shipped directly to consumers face more handling and transit risk than items sold through traditional retail.
-
Premiumization in spice, seasoning, and condiment packaging is driving demand for closures with integrated dosing control, tamper-evidence, and refined tactile design that support a higher retail price point.
-
Personal care and beauty brands are adopting dual flap closures for powder and granular products, applications that historically relied on simpler screw caps or sifter tops.
-
Manufacturers are consolidating through acquisition as they chase the scale needed to serve major consumer packaged goods customers cost-effectively while funding sustainability-driven material R&D.
U.S. Dual Flap Dispensing Closure Market Outlook
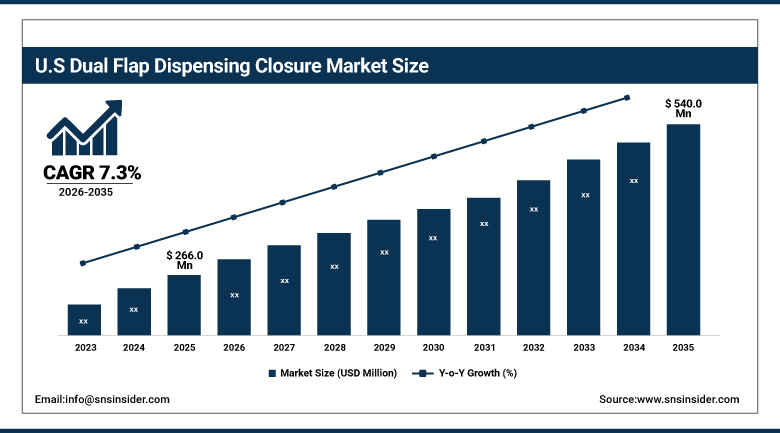
The U.S. Dual Flap Dispensing Closure Market was valued at approximately USD 266.0 Million in 2025 and is expected to reach approximately USD 540.0 Million by 2035, growing at a CAGR of approximately 7.3%.
Demand in the United States is anchored by a large fast-moving consumer goods sector spanning spices, seasonings, household products, and personal care items that rely heavily on dual flap closures for everyday portion control. Domestic manufacturers serve major CPG brand owners through established relationships built on closure quality, capping equipment compatibility, and food-safety compliance. Growing e-commerce penetration is adding a further layer of demand for closures engineered to survive the additional handling that direct-to-consumer shipping involves.
Berry Global, one of the largest manufacturers of dual flap dispensing closures serving the U.S. market, was acquired by Amcor in a deal that closed in April 2025, combining two of the industry's largest plastic packaging suppliers into a single organization with an even broader closures and dispensing systems portfolio serving American food, personal care, and household product brands.
Dual Flap Dispensing Closure Market Segment Analysis
-
By Material, the Polypropylene (PP) segment dominated the Dual Flap Dispensing Closure Market with approximately 42.0% share in 2025, while the High-Density Polyethylene (HDPE) segment is the fastest growing with a CAGR of approximately 7.8%.
-
By Application/End-Use Industry, the Household segment dominated the Dual Flap Dispensing Closure Market with approximately 43.6% share in 2025, while the Personal Care & Beauty segment is the fastest growing with a CAGR of approximately 9.4%.
-
By Closure Design, the Screw-On/Threaded segment dominated the Dual Flap Dispensing Closure Market with approximately 54.0% share in 2025, while the Snap-On segment is the fastest growing with a CAGR of approximately 8.9%.
-
By Neck Size, the Medium (28–38mm) segment dominated the Dual Flap Dispensing Closure Market with approximately 48.0% share in 2025, while the Small (Below 28mm) segment is the fastest growing with a CAGR of approximately 9.2%.
-
By Distribution Channel, the Direct/B2B Supply segment dominated the Dual Flap Dispensing Closure Market with approximately 58.0% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 11.4%.
By Material, polypropylene dominates, HDPE grows fastest
In 2025, the market for material had polypropylene with the biggest market share because of its cost-efficiency and ability to be used effectively by existing machinery. This material's rigidity and flexibility make it very well suited for use in dual flap closures due to their hinged flap design.
High-density polyethylene is increasing at the fastest rate as companies prefer it because of its chemical resistance and durability when used in domestic and industrial settings where dual flap closures have more exposure than just normal food products. This material is very recyclable with an established recycling stream for domestic chemical packaging.
By Application, household dominates, personal care & beauty grows fastest
Household products accounted for the largest application share in 2025, spanning everyday items like salt, sugar, detergents, and bath essentials where dual flap closures let consumers control whether they're pouring or shaking a product. That broad, high-frequency usage across nearly every household keeps this the largest single application category by a wide margin.
Personal care and beauty products are the fastest-growing application as premium cosmetics and personal care brands adopt dual flap closures for powder and granular formulations that previously relied on simpler sifter tops or screw caps. Rising premiumization trends in this category give brands a clear incentive to invest in more sophisticated closure design as a point of shelf differentiation.
By Closure Design, screw-on dominates, snap-on grows fastest
The screw cap/ threaded closure design accounted for the largest proportion of the closure design market share in 2025 due to its tamper resistance seal which is a requirement in most food safety and household chemical applications. The strength of the seals provided through repeatable open/close cycle makes them the go-to closures in any situation that requires containment assurance.
Snap on closures have experienced the highest growth because of the demand from manufacturers and brands for ease of use and speed in opening and closing the package in everyday consumer applications that require opening and closing multiple times per day.
By Neck Size, medium dominates, small grows fastest
Medium neck sizes, roughly 28 to 38 millimeters, held the largest share of the neck-size segment in 2025, matching the standard container dimensions most common across spice jars, condiment bottles, and household product canisters. That broad compatibility with existing container designs keeps medium sizing the default specification most manufacturers produce at scale.
Small neck sizes are growing fastest as single-serve and travel-size packaging trends continue expanding across food, personal care, and household categories. Compact packaging formats designed for portability and portion control are pulling demand toward smaller closure specifications that weren't a significant volume category a decade ago.
By Distribution Channel, direct/B2B supply dominates, online retail grows fastest
In the year 2025, Direct & B2B Supply had the highest market share as far as the distribution channel was concerned due to the fact that the huge number of dual flap closures enter the market by way of supply contracts between the manufacturers and brand owners rather than through direct retail.
However, the online retail segment is growing at the fastest rate due to the reason that many smaller brand owners and manufacturers use the internet to procure their closures from the industrial marketplace. This is particularly true when it comes to smaller CPG firms that don't have the purchasing volume to command favorable direct-supply terms.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.0% |
|
Europe |
Germany |
24.0% |
|
Asia Pacific |
China |
38.0% |
|
Latin America |
Brazil |
39.0% |
|
Middle East & Africa |
UAE |
29.0% |
North America Dual Flap Dispensing Closure Market Insights
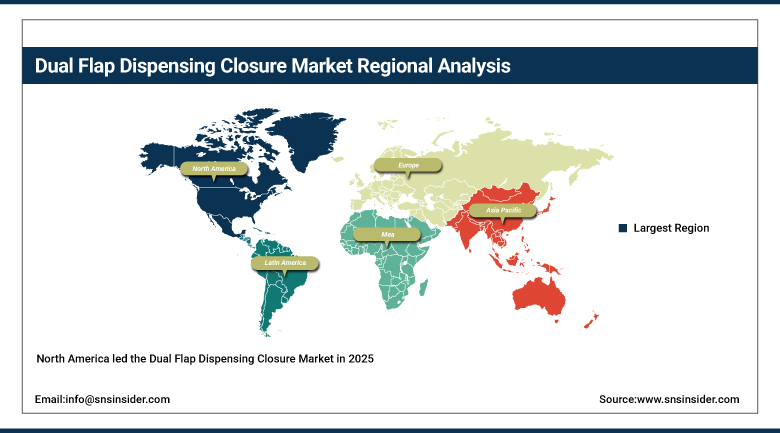
North America led the Dual Flap Dispensing Closure Market in 2025, anchored by the United States' large fast-moving consumer goods sector and its deep base of established closure manufacturers serving major CPG brand owners. Well-developed supply relationships between closure manufacturers and packaged food and household product companies give the region a level of market maturity that most other regions haven't matched.
Canada contributes a meaningful share through its own packaged food and household product manufacturing base, while Mexico's market continues expanding alongside growing regional packaged goods production. Cross-border supply chains tie much of North American demand together, with major manufacturers typically serving all three markets through shared production capacity.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Dual Flap Dispensing Closure Market Insights
The region of Asia Pacific is anticipated to show the highest rate of growth till 2035, on account of increased urbanization and changing consumer lifestyles which are motivating manufactures to quicken the pace of adopting convenient packaging options. The fast-growing packaged food and personal care industries in China and India are generating a large amount of demand for affordable closures.
Manufacturing capacity in China makes it not only a huge consumer base but also an important producer of plastic closures; while South Korea and Japan can be viewed as mature and quality-conscious markets. Southeast Asia is also moving along the same adoption trend.
Europe Dual Flap Dispensing Closure Market Insights
Europe represents a mature, sustainability-focused dual flap dispensing closure market, shaped heavily by EU packaging waste regulation that pushes manufacturers toward mono-material and more easily recyclable closure designs. Germany anchors regional demand, home to several major closure manufacturers with established European distribution networks.
The United Kingdom and South Korea, cited among the fastest-growing individual national markets globally, reflect how regulatory and consumer sustainability pressure is reshaping closure specification across developed markets. France and Italy contribute meaningful volume as well, each with substantial packaged food and personal care manufacturing sectors.
MEA & Latin America Dual Flap Dispensing Closure Market Insights
The Middle East and Africa represent a smaller but developing dual flap dispensing closure market, with the UAE driving demand through growing packaged food and personal care retail expansion tied to rising urbanization. Growth elsewhere in the region remains tied closely to the pace of modern retail and packaged goods manufacturing development.
Latin America is a growing market led by Brazil, where expanding packaged food and household product manufacturing continues driving closure demand higher. Mexico contributes a meaningful secondary share of regional demand, tied to its growing consumer packaged goods manufacturing base serving both domestic and export markets.
Market Dynamics
Growth Drivers: Convenience packaging demand and premiumization fueling adoption
Rising consumer demand for convenient, easy-to-use packaging is one of the clearest forces behind dual flap closure adoption, since the format lets shoppers control product flow, pouring versus shaking, without the fumbling a simple screw cap sometimes requires. That practical convenience advantage keeps demand growing steadily across food, household, and personal care categories alike.
Premiumization in packaging design adds a second major driver, as brand owners increasingly treat closure design as a genuine differentiation point rather than a purely functional afterthought. Integrated dosing control, tamper-evidence, and refined tactile design all give brands ways to justify premium pricing that a basic closure simply can't support.
Restraints: Material cost volatility and recycling complexity limiting margin stability
Plastic resin price volatility adds real cost unpredictability for closure manufacturers, since polypropylene and HDPE prices can swing significantly based on broader petrochemical market conditions. Manufacturers without long-term resin supply contracts are particularly exposed to these swings, which can compress margins even when finished-closure demand remains steady.
Recycling complexity remains a genuine restraint as well, since dual flap closures often combine multiple plastic components or colors that complicate standard recycling stream sorting. That complexity is pushing manufacturers toward mono-material redesigns, but the transition requires real engineering investment and retooling that smaller manufacturers may struggle to fund quickly.
Opportunities: Mono-material innovation and personal care expansion opening new growth avenues
Mono-material closure innovation offers manufacturers a genuine path to capturing premium business from brand owners chasing credible sustainability improvements ahead of tightening packaging waste regulation. Companies that scale mono-material design successfully are positioned to capture a growing share of business from CPG brands prioritizing recyclability.
Expanding personal care and beauty applications represent a second significant opportunity, as premium cosmetics brands increasingly adopt dual flap closures for powder and granular formulations that previously relied on simpler closure formats. Manufacturers that build genuine expertise serving this higher-margin application are positioned to capture disproportionate growth relative to the broader household and food categories.
Recent Developments:
-
October 2024: Silgan Holdings acquired Weener Packaging, a leading producer of differentiated dispensing solutions, expanding its dispensing product portfolio across personal care, health care, and food markets.
-
2025: Berry Global launched a mono-material polypropylene dual flap dispensing closure engineered for compatibility with standard plastic recycling streams.
-
2024: Silgan Holdings and Berry Global both advanced recyclable all-PP dispensing closure programs for European and North American customers, part of a broader industry shift toward mono-material construction.
-
2025: Silgan Holdings reported that its dispensing and specialty closures business accounted for nearly half of the company's consolidated EBIT, underscoring how central dispensing closures have become to major packaging suppliers' overall business mix.
Dual Flap Dispensing Closure Market Key Players
-
Berry Global Group, Inc. (Amcor plc)
-
AptarGroup, Inc.
-
Silgan Holdings Inc.
-
Closure Systems International, Inc.
-
RPC Group plc
-
ALPLA Werke Alwin Lehner GmbH & Co KG
-
Alpha Packaging, Inc.
-
MJS Packaging
-
Comar, LLC
-
Mold-Rite Plastics, LLC
-
O.Berk Company, LLC
-
Aaron Packaging, Inc.
-
Weener Plastics Holding B.V.
-
Guala Closures Group S.p.A.
-
TricorBraun Inc.
-
BERICAP Group
-
United Caps
-
Pano Cap Canada Ltd.
-
Georg MENSHEN GmbH & Co. KG
-
Silgan Dispensing
Dual Flap Dispensing Closure Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 900.0 Million |
| Market Size by 2035 | USD 2.05 Billion |
| CAGR | CAGR of 8.6% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material (Polypropylene (PP), High-Density Polyethylene (HDPE), Others) • by Application/End-Use Industry (Food & Beverage, Personal Care & Beauty, Household, Pharmaceutical & Healthcare, Others) • by Closure Design (Snap-On, Screw-On/Threaded, Hinged) • by Neck Size (Small: Below 28mm, Medium: 28–38mm, Large: Above 38mm) • by Distribution Channel (Direct/B2B Supply, Retail, Online Retail) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Berry Global Group, Inc. (Amcor plc), AptarGroup, Inc., Silgan Holdings Inc., Closure Systems International, Inc., RPC Group plc, ALPLA Werke Alwin Lehner GmbH & Co KG, Alpha Packaging, Inc., MJS Packaging, Comar, LLC, Mold-Rite Plastics, LLC, O.Berk Company, LLC, Aaron Packaging, Inc., Weener Plastics Holding B.V., Guala Closures Group S.p.A., TricorBraun Inc., BERICAP Group, United Caps, Pano Cap Canada Ltd., Georg MENSHEN GmbH & Co. KG., Silgan Dispensing |
Frequently Asked Questions
The Dual Flap Dispensing Closure Market is expected to grow at a CAGR of 8.6% from 2026 to 2035.
Rising consumer demand for convenient, easy-to-use packaging combined with growing premiumization in spice, condiment, and personal care packaging design.
North America dominated the Dual Flap Dispensing Closure Market in 2025, while Asia Pacific is the fastest-growing region.
