
Edible Water Bottles Market Report Scope & Overview:
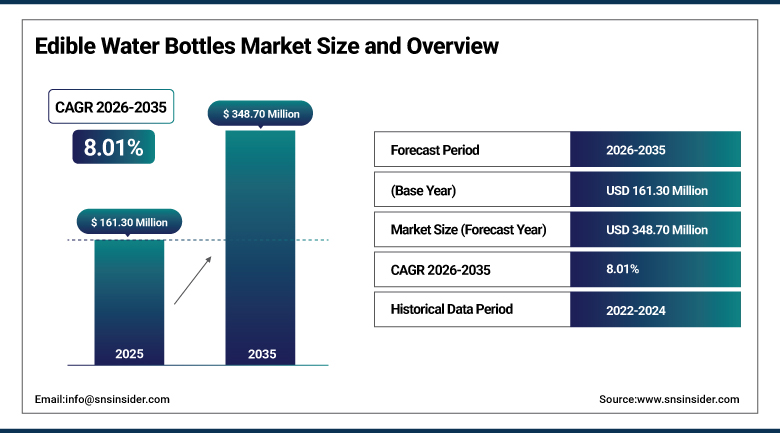
The Edible Water Bottles Market was valued at USD 161.30 Million in 2025 and is expected to reach USD 348.70 Million by 2035, growing at a CAGR of 8.01% from 2026 to 2035.
The Edible Water Bottles Market has emerged as a truly direct solution to the problem of plastic pollution throughout the world because it uses capsules and bottles that are biodegradable and can be consumed by humans instead of just trying to make plastics a little more recyclable. Over 450 million single-use plastic bottles are consumed daily worldwide, contributing to 13 million tons of marine plastic waste annually, a scale of problem that has pushed edible packaging from a novelty demonstration into genuine commercial trials across events, festivals, and food service. These innovative capsules are primarily composed of edible seaweed derivatives such as sodium alginate and other plant-based polymers, materials that dissolve or can simply be eaten once the water inside has been consumed, eliminating the packaging waste question entirely rather than just deferring it to a recycling system that may or may not actually process it.
In 2024, more than 27 million edible water capsules were produced globally, with Europe accounting for 47% of total production volume, primarily composed of edible seaweed derivatives such as sodium alginate.
To Get more information Edible Water Bottles Market - Request Free Sample Report
Edible Water Bottles Market Trends
- Commercial trials at marathons, festivals, and sporting events continue expanding real-world adoption of edible water capsules.
- Nutrient-enriched edible bottles are gaining rapid traction as brands add functional health benefits beyond basic hydration.
- State and municipal plastic bans are prompting businesses to test edible water capsules as compliant single-use alternatives.
- Seaweed-derived materials remain the dominant packaging base as sodium alginate technology continues to mature commercially.
- Hospitality and food service adoption is expanding as venues seek visible, story-driven sustainability commitments for guests.
The U.S. Edible Water Bottles Market Outlook
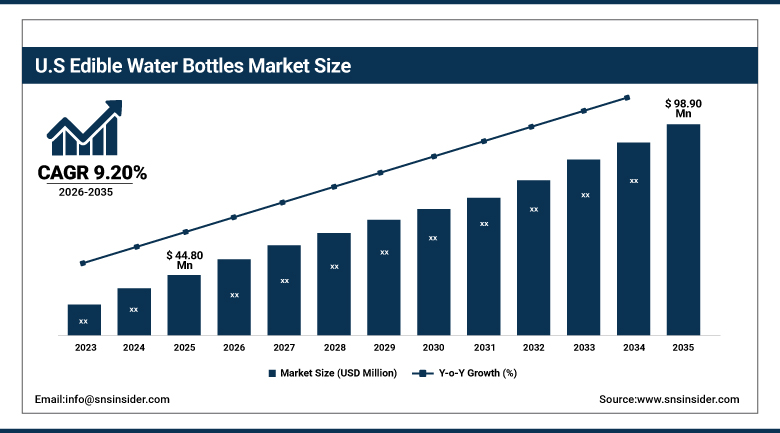
The U.S. Edible Water Bottles Market was valued at USD 44.80 Million in 2025 and is projected to reach USD 98.90 Million by 2035, growing at a CAGR of 9.20% during 2026-2035.
There were some advancements seen in the domestic market, as more than 5.6 million units of edible water bottles were distributed throughout the year 2024 in domestic markets in response to the growing curiosity of consumers. The states of California, New York, and Oregon emerged as the pioneers in adopting this innovation domestically, with these three states responsible for 51% of total domestic sales. With plastic bans in over 16 states targeting single-use bottles, businesses and municipal organizations are increasingly testing edible water capsules as a genuine compliance-friendly alternative rather than simply an experimental novelty. Growing commercial trials at sporting events, festivals, and conferences continue building consumer familiarity with a format that remains genuinely unfamiliar to most American shoppers outside these settings.
In June 2025, Cove launched fully compostable and edible water bottles across select U.S. retail and hospitality locations, marking one of the most prominent commercial rollouts of edible packaging technology to date.
Edible Water Bottles Market Segment Analysis
- By Material Type, seaweed-based dominates the edible water bottles market with seaweed-based holding 62% share in 2025 while plant-based grows fastest registering a CAGR of 10.20% from 2026 to 2035.
- By Product Type, plain edible bottles dominates the edible water bottles market with plain edible bottles holding 58% share in 2025 while nutrient-enriched edible bottles grows fastest registering a CAGR of 11.60% from 2026 to 2035.
- By Application, beverage industry dominates the edible water bottles market with beverage industry holding 38% share in 2025 while sports & events grows fastest registering a CAGR of 12.40% from 2026 to 2035.
- By End User, commercial dominates the edible water bottles market with commercial holding 72% share in 2025 while home use grows fastest registering a CAGR of 13.20% from 2026 to 2035.
- By Distribution Channel, direct sales dominates the edible water bottles market with direct sales holding 45.30% share in 2025, while e-commerce sales grows fastest, registering a CAGR of 26.40% from 2026 to 2035.
By Material Type, seaweed-based dominates the edible water bottles market while plant-based grows fastest
Seaweed-based occupies 62% of the edible water bottle market share, which is the largest segment in the industry because this product is mainly made from seaweed derivatives like sodium alginate, which is considered the most tested formulation of the technology. The lower ecological impact of seaweed farming versus land crop production continues to validate this material’s association with the core positioning of the industry.
Plant-based is growing at a 10.20% CAGR, the fastest pace among material types, as manufacturers increasingly explore alternative plant-derived polymers that can diversify supply chains beyond seaweed cultivation and potentially offer different taste, texture, or dissolution characteristics for specific applications. Growing material science investment across the broader sustainable packaging industry continues reinforcing plant-based innovation's above-average growth trajectory.
By Product Type, plain edible bottles dominates the edible water bottles market while nutrient-enriched edible bottles grows fastest
Regular Edible Bottles constitute the biggest share of 58% based on the product type segment, since regular hydration continues to be the main application case of these bottles in events, catering, and hospitality industries when cost is the priority rather than additional features. The established manufacturing techniques for regular formulas make these products the most affordable ones in mass commercialization.
Nutrition-Enhanced Edible Bottles are experiencing a fast rise due to additional health effects of these products with 11.60% CAGR as brands are increasingly marketing edible water bottles as a wellness product rather than a novel form of hydration. Growing consumer interest in functional beverages more broadly is reinforcing this product type's above-average growth trajectory.
By Application, beverage industry dominates the edible water bottles market while sports & events grows fastest
Beverage industry applications continue to represent the largest market share, accounting for 38% of application demand, as edible water capsules increasingly find placement alongside conventional bottled beverages in venues seeking visible sustainability differentiation. Growing brand interest in edible packaging as a genuine marketing and sustainability story continues reinforcing this application's lead.
Sports & Events Application is the one with the highest CAGR of 12.40%, with the hospitality and sports sectors witnessing strong growth due to increased adoption by 38% in 2025 for commercial uses and niche events such as marathons and festivals, with more than 2.2 million units in circulation in public sporting and cultural events. The increasing interest of event organizers in minimizing single-use plastic waste during public events further strengthens its strong growth trend.
By End USer, commercial dominates the edible water bottles market while home use grows fastest
Commercial leads in the market by distribution channel at 72%, which is the biggest category, because events, hospitality locations, and specialty retailers are still the main way consumers get to experience edible water capsules for the first time. The partnerships already established between edible packaging manufacturers and events have ensured the continued dominance of this channel.
Home use is growing fastest, at a 13.20% CAGR, as consumer familiarity built through commercial trial experiences increasingly translates into direct retail purchasing for personal and household hydration use. Growing retail availability through specialty and sustainability-focused retailers continues reinforcing this channel's above-average growth trajectory.
Regional Analysis
|
Region |
Country |
Share within Region, 2025 (%) |
|
North America |
United States |
85.00% |
|
Europe |
Germany |
26.20% |
|
Asia Pacific |
China |
68.20% |
|
Middle East & Africa |
Saudi Arabia |
17.30% |
|
Latin America |
Brazil |
26.60% |
North America Edible Water Bottles Market Insights
Edible Water Bottles Market in North America has been exhibiting steady growth fueled by good environmental consciousness and well-developed packaging technology infrastructure in the region. Banning of plastics for single use water bottles in many states in the U.S. continues to drive demand for edible water capsules that are in compliance with regulations.
United States holds the largest market share in the North America Edible Water Bottles Market accounting for nearly 85.00%, owing to its higher share in commercial trials of the product and innovative edible packaging players.
Europe Edible Water Bottles Market Insights
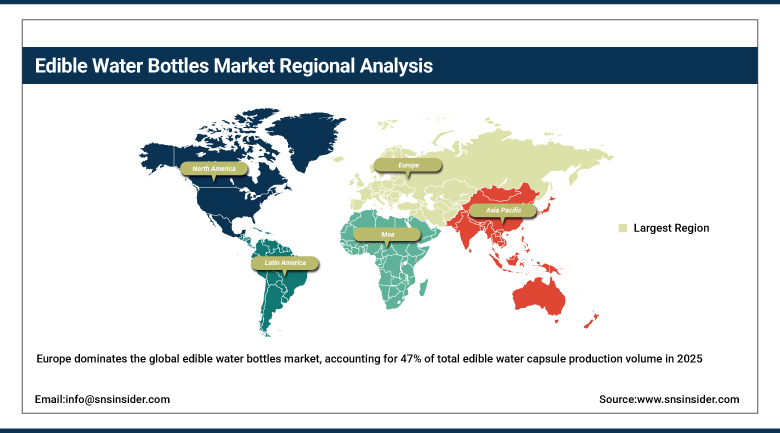
Europe dominates the global edible water bottles market, accounting for 47% of total edible water capsule production volume in 2025, driven by the region's strong environmental consciousness and receptiveness to novel sustainable packaging concepts. European commercial trials at festivals, marathons, and public events have provided some of the category's most visible real-world adoption, reinforcing the region's leadership position.
Germany leads the European market with a 26.20% share, supported by its strong sustainability-conscious consumer culture and growing interest in alternative packaging materials. The United Kingdom and France follow, with demand in both countries tied to established event and festival culture that has provided early commercial trial opportunities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Edible Water Bottles Market Insights
Asia Pacific is growing faster than any other region in this market, driven by increasing urbanization and government initiatives promoting sustainable packaging across the region's major economies. Rising environmental awareness and growing plastic waste regulation across China and India continue creating exactly the kind of first-time adoption growth that mature markets can no longer generate at comparable scale.
China holds roughly 68.20% of the regional market, supported by its large population base and growing government attention to plastic waste reduction. India and Southeast Asian markets are growing quickly as environmental awareness spreads, while Japan and South Korea contribute through their established, technology-forward sustainable packaging industries.
Middle East & Africa and Latin America Edible Water Bottles Market Insights
The Middle East and Africa region is experiencing steady growth due to increased awareness about the environment coupled with the improved modern retail infrastructure in the Gulf countries, backed by increasing popularity of sustainable packaging innovations. The same pattern applies to the Latin American region, which is experiencing growth due to the increase in the number of sustainability-oriented consumers in Brazil.
The UAE accounts for 17.30% of the total Middle East and Africa market owing to its status as a hub of sustainable innovation and events. Brazil holds a share of 26.60% of the total Latin American market owing to its sizeable consumer base along with Mexico, which contributes due to increased awareness and event industry.
Market Dynamics
Growth Drivers: Plastic Waste Crisis and Regulatory Bans Fueling Market Growth
The global plastic waste crisis is the clearest driver behind this market's growth, as over 450 million single-use plastic bottles are consumed daily worldwide, contributing to 13 million tons of marine plastic waste annually, a scale of problem that edible packaging directly addresses rather than merely mitigates. Plastic bans in over 16 U.S. states and comparable regulation across Europe and Asia Pacific are reinforcing this demand, as businesses and municipal organizations increasingly need compliant single-use alternatives.
Growing commercial trial activity at marathons, festivals, and public events is adding a meaningful additional demand line, as each successful high-visibility trial builds consumer familiarity and normalizes the format for broader retail adoption.
Restraints: Limited Shelf Life and Consumer Familiarity Gaps Limiting Market Expansion
The use of edible water capsules is bound by certain challenges in terms of shelf life and storage conditions, since biodegradable membranes can be expected to be less durable over long periods of time than plastic bottles. The lack of consumer familiarity is also an issue, especially since most customers have never experienced the product, as its consumption would involve eating the packaging.
Production scale remains limited relative to conventional bottled water manufacturing, creating a genuine cost premium that constrains broader retail adoption beyond premium and novelty positioning.
Opportunities: Nutrient Enrichment and Retail Expansion Creating New Growth Avenues
Development of nutrient-added products presents an exciting growth potential for brands that see their future edible water bottles as not only a new hydration technology but also a functional product offering additional health benefits. Those who succeed at adding value and creating stable capsules have great potential to capitalize on such positioning.
Expansion from commercial trial settings into mainstream retail availability offers a second clear opportunity, particularly as consumer familiarity built through events and festivals increasingly translates into direct purchasing interest for home use.
Recent Developments:
- 2024: Adoption of edible water capsules rose by 38% across commercial trials and niche events like marathons and festivals, with over 2.2 million units distributed in public sporting and cultural events worldwide.
- 2024: In the United States, over 5.6 million edible water bottle units were distributed across events, hospitality venues, and specialty retailers, with California, New York, and Oregon leading domestic adoption with 51% of total consumption.
- 2025: Notpla Ltd. continued expanding commercial applications of its Ooho edible packaging technology, building on its origins as a seaweed-derived alternative to single-use plastic water sachets.
Edible Water Bottles Market key players are:
- Notpla Ltd.
- Cove
- Loliware Inc.
- WikiFoods, Inc.
- Do-Eat
- Sway
- Tomorrow Machine
- Zerocircle
- Evoware
- MarinaTex
- TIPA Corp Ltd.
- Amcor plc
- Mondi Group
- Tetra Pak International S.A.
- Huhtamaki Oyj
- Stora Enso Oyj
- BASF SE
- Danimer Scientific, Inc.
- NatureWorks LLC
- Elastopoli Oy
Edible Water Bottles Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 161.30 Billion |
| Market Size by 2035 | USD 348.70 Billion |
| CAGR | CAGR of 8.01% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Seaweed-Based, Plant-Based, Others) • By Product Type (Plain Edible Bottles, Nutrient-Enriched Edible Bottles, Mineral Water, Sparkled Water, Flavored Water, Others) • By Application (Beverage Industry, Hospitality & Food Service, Sports & Events, Retail & Consumer Use, Travel & Tourism, Institutional & Corporate, Others) • By Distribution Channel (Direct Sales, Online / E-Commerce, Retail Stores, Supermarkets & Hypermarkets, Specialty Stores, Others) • By End User (Commercial, Home Use, Institutional) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Notpla Ltd., Cove, Loliware Inc., WikiFoods, Inc., Do-Eat, Sway, Tomorrow Machine, Zerocircle, Evoware, MarinaTex, TIPA Corp Ltd., Amcor plc, Mondi Group, Tetra Pak International S.A., Huhtamaki Oyj, Stora Enso Oyj, BASF SE, Danimer Scientific, Inc., NatureWorks LLC, Elastopoli Oy |
Frequently Asked Questions
Key players include Notpla Ltd., Cove, Loliware Inc., WikiFoods, Inc., and biodegradable packaging innovators, among others.
Key opportunities include nutrient-enriched product development positioning capsules as functional wellness products, expansion from commercial trials into mainstream retail, and growing plastic-ban-driven institutional adoption.
The market is driven by the global plastic waste crisis, plastic bans across numerous states and regions, and growing commercial trial activity at events and festivals building consumer familiarity.
The Seaweed-Based segment dominated the Edible Water Bottles Market in 2025.
The Europe region dominated the Edible Water Bottles Market in 2025, accounting for approximately 47% of global production volume.
