
Enterprise Video Market Report Scope & Overview:
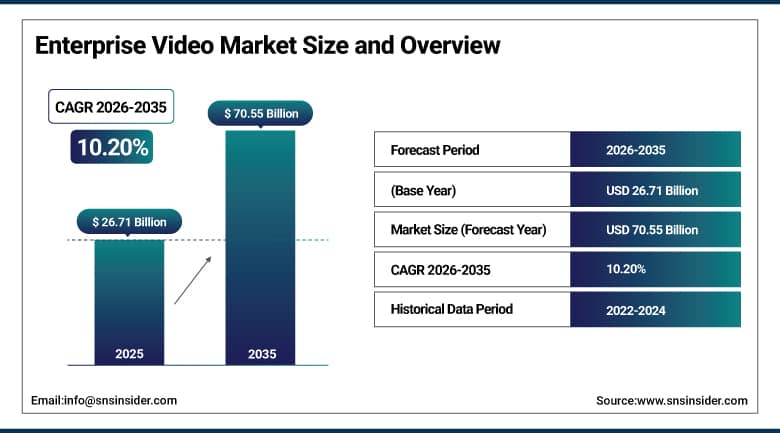
The Enterprise Video Market was valued at USD 26.71 Billion in 2025 and is expected to reach USD 70.55 Billion by 2035, growing at a CAGR of 10.20% from 2026-2035.
Enterprise video has shifted from a meeting tool into mission-critical infrastructure supporting workflow automation, data-driven decision making, and global collaboration, a genuine change in how organizations think about video rather than simply an expansion of video conferencing volume. Video conferencing remains the entrenched default collaboration medium and the largest single category by revenue, but AI-powered video analytics, capable of detecting anomalies, extracting metadata, and triggering workflow automations across security, manufacturing, and retail settings, is expanding far faster than any other segment as enterprises discover use cases well beyond the original meeting-room application. Adoption patterns increasingly reveal convergence between once-distinct categories, as conferencing vendors bundle analytics for speaker sentiment while content-management platforms embed live-stream modules to support hybrid events.
AI video generators including Google's Veo 3 are increasingly blurring the boundary between video production and distribution, enabling non-specialist employees to create branded video assets in seconds rather than requiring a dedicated production team or external agency. This matters because it fundamentally changes the economics of enterprise video content creation, moving training, marketing, and internal communication video from an occasional, resource-intensive project into something individual teams can generate on demand, a shift that vendors across the enterprise video landscape are racing to build native AI generation capability around rather than treating it as a separate, standalone tool.
To Get More Information On Enterprise Video Market - Request Free Sample Report
Enterprise Video Market Trends
-
AI-powered video analytics is expanding rapidly beyond security applications into manufacturing, retail, and workflow automation use cases.
-
Enterprise video platforms are converging with unified communications, bundling conferencing, messaging, and content management into single platforms.
-
AI video generation tools are enabling non-specialist employees to create branded video content without dedicated production resources.
-
Automated transcription, meeting summaries, and analytics continue improving enterprise video content usability and management.
-
Cloud-native architecture adoption continues accelerating, improving scalability for enterprises managing growing video content libraries.
U.S. Enterprise Video Market Outlook
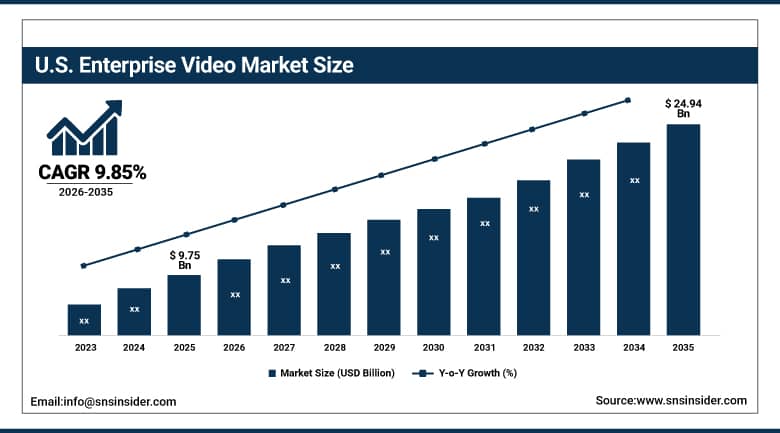
The U.S. Enterprise Video Market was valued at approximately USD 9.75 Billion in 2025 and is expected to reach approximately USD 24.94 Billion by 2035, growing at a CAGR of approximately 9.85%.
The U.S. market is driven by widespread digital workplace adoption, an entrenched remote and hybrid work culture, and strong enterprise investment in video communication tools as companies prioritize employee engagement, virtual collaboration, and high-quality content delivery across corporate environments. Large enterprises across finance, healthcare, and technology sectors continue to anchor domestic demand, given their scale and existing investment in broader digital workplace transformation initiatives that enterprise video increasingly forms a core component of.
Microsoft continued extending its integrated collaboration environment through 2024 and 2025, deepening Microsoft Teams' integration with Microsoft 365 while expanding artificial intelligence capability and security framework depth that particularly appeals to its large customer base in regulated industries. The company's continued leadership reflects how enterprise video purchasing decisions increasingly hinge on platform breadth and existing software ecosystem integration rather than video quality alone, since most large enterprises now evaluate video tools as one component of a broader digital workplace suite rather than a standalone communication tool.
Enterprise Video Market Segment Analysis
-
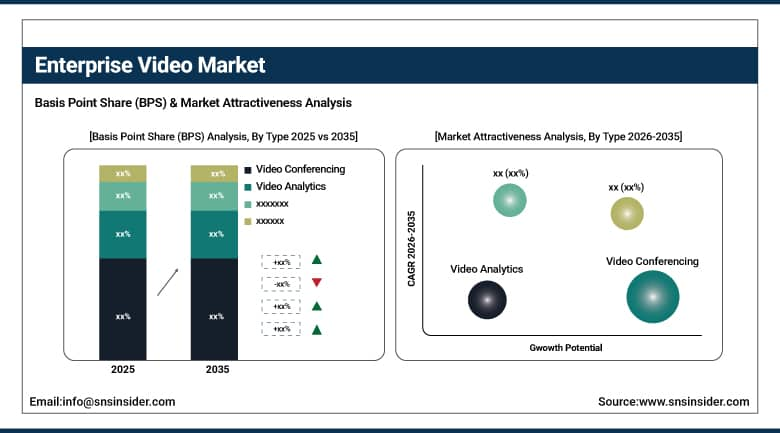
By Type, the Video Conferencing segment dominated the Enterprise Video Market with approximately 42.85% share in 2025, while the Video Analytics segment is the fastest growing with a CAGR of approximately 17.60%.
-
By Component, the Software segment dominated the Enterprise Video Market with approximately 49.30% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 13.45%.
-
By Organization Size, the Large Enterprises segment dominated the Enterprise Video Market with approximately 62.75% share in 2025, while the Small & Medium Enterprises (SMEs) segment is the fastest growing with a CAGR of approximately 11.95%.
-
By Deployment Mode, the Cloud segment dominated the Enterprise Video Market with approximately 71.20% share in 2025, and is also the fastest growing with a CAGR of approximately 12.40%.
-
By End-Use Industry, the IT & Telecom segment dominated the Enterprise Video Market with approximately 24.60% share in 2025, while the Healthcare & Life Sciences segment is the fastest growing with a CAGR of approximately 14.80%.
By Type, video conferencing dominates, video analytics grows fastest
Video conferencing dominated the type segment in 2025, reflecting its entrenchment as the default collaboration medium across nearly every enterprise following the broad, lasting shift toward remote and hybrid work that reshaped corporate communication patterns over the past several years. Continued bundling of AI features including automated transcription and meeting summaries keeps conferencing platforms central to daily enterprise workflow beyond pure video calling.
Video analytics is the fastest-growing type segment with its momentum stemming from AI engines that detect anomalies, extract metadata, and trigger workflow automations across security, manufacturing, and retail settings, use cases that extend well beyond video analytics' original narrow security-monitoring application. Adoption patterns increasingly reveal convergence with other video categories, as conferencing vendors bundle sentiment analytics while content-management platforms embed similar automated detection capability.
By Component, software dominates, services grows fastest
Software dominated the component segment in 2025, underpinning the meeting, streaming, and archival functions that form the core functional backbone of any enterprise video deployment across conferencing, content management, and analytics applications alike. Vendors continue expanding software feature depth around AI-driven summarization and search, reinforcing software's central role even as services revenue grows at a faster relative pace.
Services are the fastest-growing component segment expanding over the forecast period, as enterprises increasingly require implementation, integration, and ongoing management support to fully realize value from increasingly sophisticated, AI-enabled video platforms rather than treating software as a self-service purchase. Growing platform complexity across multiple integrated AI capabilities continues to expand the scope of professional services engagements beyond basic setup and training.
By Organization Size, large enterprises dominates, SMEs grows fastest
Large enterprises dominated the organization size segment due to the nature of their business, past investments in digital workplace transformation initiatives, and financial ability to deploy an integrated video platform across the enterprise for conferencing, content management, and analytics in large workforces that may be geographically dispersed. The multinational enterprises especially have standardized on an integrated video platform for all their regional offices, giving the large enterprise segment a leading edge in terms of size and purchasing power.
The small and medium enterprises (SMEs) have been the fastest growing organization size segment over the forecast period, owing to falling prices of cloud-based platform and simplification of deployment. This has made it easier for smaller companies that previously could not afford an enterprise grade video platform to adopt such technologies due to financial constraints.
By Deployment Mode, cloud dominates and also grows fastest
Cloud deployment dominated the deployment mode segment in 2025, as enterprises increasingly favor subscription-based platforms that eliminate on-premise hardware maintenance while enabling rapid scaling across distributed, hybrid workforces. Continuous vendor investment in cloud-native AI features, including automated transcription and analytics, further reinforces cloud's advantage over legacy on-premise systems for most enterprise buyers.
Cloud deployment is also the fastest-growing segment over the forecast period, as regulated industries that previously required on-premise or air-gapped systems increasingly adopt compliant, sovereign cloud offerings that satisfy data residency requirements. Vendors continue to expand region-specific cloud hosting options specifically to address this remaining barrier among security-conscious enterprise buyers.
By End-Use Industry, IT & Telecom dominates, healthcare grows fastest
IT & Telecom was the dominating end-use industry in 2025 because of the early adoption of video platform by the industry owing to the need to cater to distributed engineering teams, customer support activities, and other internal collaboration needs of globally scattered workforces. The IT industry also serves as the reference customer base and early adopter for AI-based video capabilities, emphasizing the dominance of the industry in terms of platform adoption in spite of revenue share.
The Healthcare & Life Sciences industry is the fastest growing end-use industry due to telemedicine, remote patient monitoring, and documentation-driven adoption of purpose-built video platforms by hospital systems and life sciences companies. The increased regulatory scrutiny on patient data management has been driving the need for healthcare compliance certifications among the video platform providers targeting this industry.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
78.35% |
|
Europe |
United Kingdom |
26.15% |
|
Asia Pacific |
China |
36.60% |
|
Latin America |
Brazil |
28.70% |
|
Middle East & Africa |
UAE |
24.05% |
North America Enterprise Video Market Insights
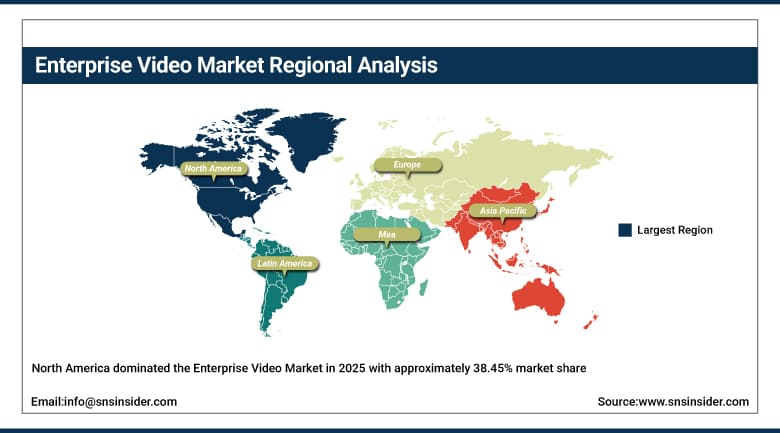
North America dominated the Enterprise Video Market in 2025 with approximately 38.45% market share, supported by widespread digital workplace adoption, an entrenched remote and hybrid work culture, and strong enterprise investment in video communication tools across finance, healthcare, and technology sectors. Strong existing cloud infrastructure investment across the region continues to support rapid deployment of increasingly sophisticated, AI-enabled video platform capability.
The United States accounts for the substantial majority of regional demand, anchored by major platform vendors headquartered domestically and large enterprise customers with sophisticated digital workplace requirements. Canadian enterprises continue to expand video platform adoption alongside similar hybrid work trends. Growing enterprise interest in unified communications consolidation continues to reinforce demand for platforms combining video, messaging, and collaboration tools within North American markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Enterprise Video Market Insights
Asia Pacific is the fastest-growing region in the Enterprise Video Market, expanding at a CAGR of approximately 13.25% over the forecast period, driven by rapid digital workplace transformation across China, India, and Southeast Asian markets alongside growing enterprise cloud adoption. Growing regional cloud infrastructure investment continues to support enterprise video platform scalability across rapidly digitalizing markets throughout the broader Asia Pacific region.
China leads regional manufacturing-sector video analytics adoption specifically, leveraging the technology for quality control and workflow automation across its large industrial manufacturing base. India's expanding IT and business process outsourcing sector continues to drive strong incremental regional demand for enterprise video infrastructure. South Korean and Japanese enterprises continue to adopt advanced video analytics for manufacturing quality control, reinforcing the region's position at the technology adoption frontier.
Europe Enterprise Video Market Insights
Europe represents a mature enterprise video market, with the UK leading regional demand through its large financial services and professional services sector requiring sophisticated video collaboration and compliance-focused content management capability. Growing enterprise cloud migration across the region continues to support broader adoption of AI-enabled video platform capability within compliance-conscious European industries.
Germany and France contribute additional demand, both markets favoring enterprise video platforms that support strict data residency and privacy compliance requirements under EU regulation. Nordic countries continue to serve as early adopters of AI-enabled video analytics pilot programs. Growing hybrid event demand across the region continues to reinforce webcasting and live-streaming platform adoption among European enterprises and event organizers.
MEA & Latin America Enterprise Video Market Insights
The Middle East and Africa are emerging regions for the market, driven by the UAE, which has been pursuing government-led digital transformation efforts. The growing use of the enterprise cloud in these regions is increasing the addressable market size for video platform providers.
Latin America is an emerging market, which is being driven by Brazil with its growing enterprise services market. Mexico provides secondary demand due to its growing outsourcing and technology sectors. Video collaboration is increasingly being adopted in Argentina and Colombia as digital transformation investments grow in the region.
Market Dynamics
Growth Drivers: Hybrid work culture and AI-powered analytics fueling adoption
Continued enterprise investment in digital workplace transformation remains the primary driver of enterprise video demand, as companies increasingly treat video platforms as essential infrastructure for communication, collaboration, training, and marketing rather than an optional productivity tool. Growing employee expectation for flexible, video-enabled remote work options continues to reinforce this investment even at organizations that have otherwise scaled back broader hybrid work policies.
Growing integration of AI-powered analytics into enterprise video platforms is expanding the technology's addressable use cases well beyond traditional meetings into security monitoring, manufacturing quality control, and retail customer behavior analysis, creating substantial new demand pools beyond conferencing alone.
Restraints: Platform fragmentation and data security concerns limiting broader adoption
Fragmentation across multiple video platforms and vendors, each often serving a different specific use case, continues to create integration complexity for IT departments seeking a unified enterprise video strategy rather than a patchwork of disconnected point solutions. Enterprises increasingly prioritize vendors offering broad platform integration capability specifically to reduce this fragmentation burden across their existing technology stack.
Data security and privacy concerns around video content, particularly for regulated industries handling sensitive customer or patient information, continue to slow adoption of certain cloud-based platforms among enterprises with strict compliance requirements.
Opportunities: AI video generation and SME market expansion widening addressable demand
The fast growth of AI video generation technology creates an excellent opportunity for platform providers to move from video hosting to video content creation, gaining a larger portion of enterprise spending on marketing and training content that used to go to external agencies for production. Platform providers that can combine generation, hosting, and analytics capabilities within one platform will be able to capture a disproportionate share of the growing and consolidating market opportunity.
Declining cloud platform costs and simplified deployment models present a substantial opportunity to expand enterprise video adoption among small and medium enterprises that previously lacked the budget or IT resources for enterprise-grade video infrastructure.
Recent Developments:
-
2024- Zoom Video Communications expanded its AI Companion feature set across its enterprise video platform, adding automated transcription, meeting summaries, and workflow analytics capability.
-
2023- Kaltura expanded its enterprise video content management platform with enhanced live-streaming and hybrid event support capability for large enterprise customers.
Enterprise Video Market Key Players
-
Microsoft Corporation
-
Cisco Systems, Inc.
-
Zoom Video Communications, Inc.
-
IBM Corporation
-
Vimeo, Inc.
-
Kaltura, Inc.
-
Brightcove Inc.
-
Panopto, Inc.
-
Dacast
-
Google LLC
-
Adobe Inc.
-
Vbrick Systems, Inc.
-
Qumu Corporation
-
IBM Video Streaming (Ustream)
-
Wowza Media Systems, LLC
-
Haivision Systems Inc.
-
Polycom (HP Inc.)
-
RingCentral, Inc.
-
Webex (Cisco)
-
GoTo Technologies (LogMeIn)
Enterprise Video Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 26.71 Billion |
| Market Size by 2035 | USD 70.55 Billion |
| CAGR | CAGR of 10.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Video Conferencing, Video Content Management, Webcasting and Live Streaming, Video Analytics, Others) • By Component (Software, Services, Hardware) • By Deployment Mode (Cloud, On-Premise) • By Organization Size (Large Enterprises, Small & Medium Enterprises (SMEs)) • By End-Use Industry (BFSI, IT & Telecom, Healthcare & Life Sciences, Media & Entertainment, Education, Government & Public Sector, Retail & E-commerce, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Microsoft Corporation, Cisco Systems, Inc., Zoom Video Communications, Inc., IBM Corporation, Vimeo, Inc., Kaltura, Inc., Brightcove Inc., Panopto, Inc., Dacast, Google LLC, Adobe Inc., Vbrick Systems, Inc., Qumu Corporation, IBM Video Streaming (Ustream), Wowza Media Systems, LLC, Haivision Systems Inc., Polycom (HP Inc.), RingCentral, Inc., Webex (Cisco), GoTo Technologies (LogMeIn) |
Frequently Asked Questions
Key players in the Enterprise Video Market include Microsoft Corporation, Cisco Systems, Inc., Zoom Video Communications, Inc., IBM Corporation, and Vimeo, Inc., among others.
Key opportunities include rapid advancement of AI video generation tools expanding into content creation, and declining cloud platform costs expanding adoption among small and medium enterprises.
The market is driven by continued enterprise investment in digital workplace transformation and growing integration of AI-powered analytics expanding video's use cases beyond traditional meetings.
The Video Conferencing segment dominated the Enterprise Video Market, accounting for approximately 42.85% market share.
North America dominated the Enterprise Video Market in 2025 with approximately 38.45% share, supported by widespread digital workplace adoption and entrenched hybrid work culture.
