
Ethanol Market Report Scope & Overview:
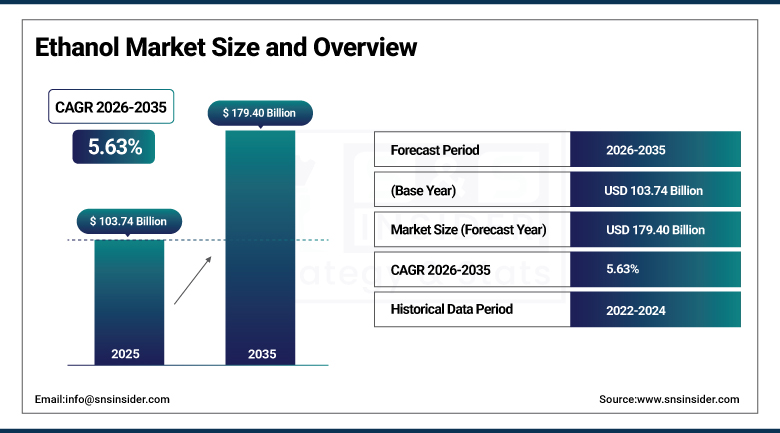
The Ethanol Market was valued at USD 103.74 Billion in 2025 and is expected to reach USD 179.40 Billion by 2035, growing at a CAGR of 5.63% from 2026-2035.
The Ethanol Market covers fuel, industrial, and beverage-grade ethyl alcohol made by fermenting grain, sugarcane, molasses, and cellulosic residues, and it is expanding as governments raise gasoline blending ratios while food, pharmaceutical, and solvent buyers keep demand firm. Revenue here counts producer sales of fuel ethanol, neutral spirits, and industrial grades, and it excludes packaged alcoholic drinks and coproducts such as distillers grains and corn oil. Capacity is consolidating around large operators, as POET's 2025 Tennessee purchase showed, and plants are adding carbon capture to lower carbon intensity scores and earn tax credits. North America holds the largest share of revenue, while Asia Pacific is adding blending mandates and distillery capacity fastest.
⮞In September 2025, POET completed its acquisition of the Green Plains bioethanol plant in Obion, Tennessee, renamed POET Bioprocessing – Obion, which adds 120 million gallons of annual capacity. The purchase lifts POET to 35 bioprocessing facilities across nine states with 3.10 billion gallons of yearly bioethanol capacity, and the company said it strengthens service to southeastern markets.
To Get more information On Ethanol Market - Request Free Sample Report
Ethanol Market Trends
-
Raising gasoline ethanol blends toward E20 in India and E30 in Brazil, which lifts fuel demand in the two fastest-expanding blending markets.
-
Adding carbon capture and low carbon intensity scoring at Midwest plants to qualify for the 45Z clean fuel production tax credit.
-
Shifting new capacity toward grain-based distilleries in India and Brazil that can switch between maize, rice, and cane feedstocks by season.
-
Upgrading ethanol into higher-value outputs such as sustainable aviation fuel feedstock, green ethyl acetate, and high-purity alcohol.
-
Commercializing second-generation ethanol from bagasse and agricultural residues, led by Raízen's new plants in São Paulo.
U.S. Ethanol Market Outlook
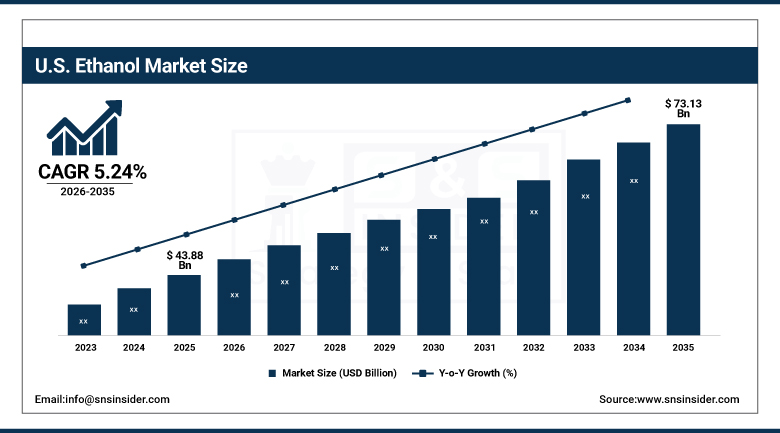
The U.S. Ethanol Market was valued at USD 43.88 Billion in 2025 and is expected to reach USD 73.13 Billion by 2035, growing at a CAGR of 5.24% from 2026-2035.
The U.S. Ethanol Market is the largest national market in the world because blending into gasoline absorbs most output, and the Corn Belt supplies low-cost corn to plants across Iowa, Nebraska, Illinois, Minnesota, and the Dakotas. E10 remains the standard blend, E15 is sold at a growing number of stations, and flex-fuel vehicles use E85, which together keep plant utilization high. Operators earn extra revenue from distillers grains, corn oil, carbon dioxide, and exports, and the 45Z credit now rewards lower carbon intensity. Growth is moderate because gasoline consumption is flat, so the outlook rests on higher blend levels, wider export access, rising carbon capture adoption, and premiums paid for lower-carbon fuel.
⮞In September 2026, ADM announced plans to enter the voluntary carbon removal market from its Columbus, Nebraska, complex, where biogenic carbon dioxide from ethanol fermentation is captured, with annual removal capacity above 800,000 tons. The carbon dioxide is moved to Tallgrass's Eastern Wyoming Sequestration Hub for storage, and Puro.earth is expected to certify the first credits by year end.
Ethanol Market Segment Analysis
-
By Source, the Grain-Based segment dominated the Ethanol Market with approximately 63.47% share in 2025, while the Sugar & Molasses-Based segment is the fastest growing with a CAGR of approximately 6.38%.
-
By Purity, the Denatured segment dominated the Ethanol Market with approximately 67.28% share in 2025, while the Undenatured segment is the fastest growing with a CAGR of approximately 6.74%.
-
By Application, the Fuel & Fuel Additives segment dominated the Ethanol Market with approximately 58.36% share in 2025, while the Beverages segment is the fastest growing with a CAGR of approximately 6.91%.
-
By End-Use, the Transportation segment dominated the Ethanol Market with approximately 61.74% share in 2025, while the Pharmaceuticals & Healthcare segment is the fastest growing with a CAGR of approximately 7.03%.
By Source, Grain-Based Dominates the Ethanol Market and Sugar & Molasses-Based Grows Fastest
Grain-based ethanol leads because corn dry-mill plants in the United States, wheat and maize plants in Europe, and new maize distilleries in India and Brazil deliver the largest volumes at predictable cost. Gevo's Richardton plant in North Dakota produces 67 million gallons a year from corn, Cardinal Ethanol lists annual capacity above 200 million gallons across its Indiana and Kansas sites, and The Andersons is planning a debottlenecking project at its Clymers, Indiana, plant. Coproducts such as distillers grains, corn oil, and carbon dioxide give grain plants a second revenue line, which cushions margins when fuel prices fall.
Sugar and molasses-based ethanol is growing faster as Brazil and India expand distilleries tied to cane and as sugar mills in Africa add alcohol units. Raízen runs the largest second-generation lines, which turn bagasse into cellulosic ethanol in São Paulo, while TPC in Tanzania plans 16.30 million liters a year of extra neutral alcohol from molasses. Indian mills can switch between cane juice, molasses, and grain to match the season, a flexibility that Godavari Biorefineries highlights at its Sameerwadi complex. Cellulosic residues, wheat, and sorghum form the remaining supply.
⮞In March 2026, Gevo said it plans a second low-carbon ethanol facility of up to 75 million gallons a year at its Richardton, North Dakota, site, which would roughly double output there. The company also plans to lift the existing plant from 67 to 75 million gallons, using nearly 52 million bushels of corn annually, and the project awaits state environmental approval.
By Purity, Denatured Dominates the Ethanol Market and Undenatured Grows Fastest
Denatured ethanol leads because fuel blending takes the bulk of production, and fuel ethanol is denatured with gasoline or another additive so that it is unfit for beverage use and avoids beverage alcohol excise tax. Corn Belt plants ship denatured product by rail and truck to terminals and blenders, and large operators such as POET, ADM, Valero, and Green Plains sell most of their output through that channel. Industrial solvent buyers also take denatured grades for cleaning, coatings, and inks. Long contracts with refiners and terminals keep this segment ahead, although margins swing with gasoline prices and corn costs.
The undenatured ethanol segment is witnessing faster growth, driven by increasing demand from the beverage, pharmaceutical, cosmetic, and food industries for neutral spirits and high-purity alcohol that comply with stringent standards such as USP, FCC, and European Pharmacopoeia. Key producers, including Greenfield Global, offer USP-, FCC-, and ACS-certified high-purity alcohol, while MGP Ingredients supplies grain neutral spirits and food-grade alcohol to brand owners, and Tereos includes alcohol and ethanol in its product portfolio. Growing emphasis on product traceability, consistent quality, and regulatory compliance enables suppliers to command premium prices. Consequently, manufacturers are investing in advanced rectification and dehydration capabilities to expand high-purity production capacity and capture greater value from specialized applications.
⮞In July 2026, Greenfield Global announced an exclusive long-term agreement with Show Me Ethanol, a Missouri producer, to supply U.S.-made USP, FCC, and ACS certified high-purity alcohol under the Greenfield Global brand. The company said the Missouri location shortens delivery distances to customers in the Midwest, Southwest, and West Coast, and it did not disclose volumes or terms.
By Application, Fuel & Fuel Additives Dominates the Ethanol Market and Beverages Grows Fastest
Fuel and fuel additives lead because ethanol works as both an octane booster and an oxygenate in gasoline, and blending mandates in the United States, Brazil, India, and the European Union fix minimum volumes. Brazilian mills sell anhydrous ethanol for gasoline blending, Indian oil marketing companies buy from distilleries such as BCL Industries and Godavari Biorefineries, and U.S. plants supply E10, E15, and E85 through terminals. Because regulation sets the demand floor, this segment grows steadily, and producers with large, low-cost plants capture most of the volume.
Beverages are growing fastest as spirits makers, wine fortifiers, and brewers draw on food-grade neutral alcohol and as premium and ready-to-drink categories raise spend per liter. Producers with rectification capacity, including MGP Ingredients at Lawrenceburg, Indiana, and Tereos in Europe, which lists alcohol among its product lines, sell neutral spirits under multi-year agreements with brand owners. Industrial solvents, personal care, and pharmaceutical uses make up the remaining applications, and disinfectant demand keeps these uses steady, while buyers increasingly ask for documented origin and lower carbon footprints.
⮞In August 2026, Alto Ingredients reported second-quarter specialty alcohol volume of 23.50 million gallons, up from 19.90 million gallons a year earlier, within net sales of USD 245.70 million. The company said it has several initiatives underway to expand capacity, optimize carbon dioxide production, and increase earnings from 45Z tax credits.
By End-Use, Transportation Dominates the Ethanol Market and Pharmaceuticals & Healthcare Grows Fastest
Transportation accounts for the largest share because ethanol blended into gasoline is the main outlet for plants in North America and Brazil, and flex-fuel vehicles use higher blends. Refiners such as Valero own ethanol plants to secure blendstock, while independent operators sell to terminals under rack and long-term contracts. Brazilian mills choose between sugar and fuel ethanol each season, and Indian distilleries sell to oil marketing companies under allocated tenders. Export demand from Canada, the European Union, and Asia adds volume when local margins weaken.
Pharmaceuticals and healthcare are growing fastest because ethanol serves as an extraction solvent, an excipient carrier, and a base for sanitizers and antiseptics, and drug makers require grades with documented purity. Greenfield Global supplies life sciences customers with high-purity alcohol and ethanol blends, and Alto Ingredients sells specialty alcohols to pharmaceutical and personal care buyers. Alcoholic beverages, chemicals and industrial uses, and personal care make up the remaining demand, and CropEnergies is building a plant that converts ethanol into green ethyl acetate for coatings and inks.
⮞In July 2026, Valero Energy reported second-quarter ethanol production of 4,666 thousand gallons per day and segment operating income of USD 318 million, compared with USD 54 million a year earlier. Valero operates 12 ethanol plants in the U.S. Mid-Continent with combined capacity of about 1.70 billion gallons per year.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
91.54% |
|
Asia Pacific |
India |
39.68% |
|
Europe |
Germany |
27.16% |
|
Middle East & Africa |
South Africa |
34.98% |
|
Latin America |
Brazil |
88.23% |
North America Ethanol Market Insights
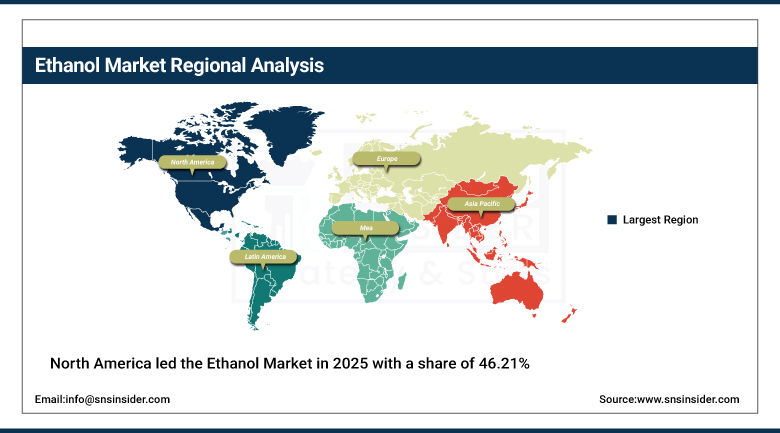
North America led the Ethanol Market in 2025 with a share of 46.21%, equal to USD 47.94 Billion, and is projected to register a CAGR of 5.19% from 2026 to 2035. The United States contributes 91.54% of the regional total, equal to USD 43.88 Billion when applied to the rounded North America figure. The region benefits from the world's largest corn-based production base, steady gasoline blending, and growing export sales. Growth is moderate because fuel demand is flat, so producers focus on carbon capture, tax credits, and coproduct income.
Canada adds blending-mandated demand and high-purity alcohol supply, with Greenfield Global, based in Toronto, serving fuel, industrial, and life sciences buyers. In the United States, Nebraska hosts large carbon capture operations at ADM and Green Plains plants, Illinois is home to the Pekin campus of Alto Ingredients, and California's Keyes plant of Aemetis supplies a market with strict carbon rules. Verbio and Gevo are converting plants in Iowa, Indiana, and North Dakota into low-carbon biorefineries. Mexico contributes smaller volumes through imports for blending and industrial use.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Ethanol Market Insights
Asia Pacific accounted for 17.34% of the Ethanol Market in 2025, equal to USD 17.99 Billion, and is the fastest growing region, projected to register a CAGR of 7.12% from 2026 to 2035. India drives this expansion with its E20 blending program, which has pushed distilleries to add grain-based capacity, and it contributes 39.68% of the regional total. Oil marketing companies buy under allocated tenders, and mills now diversify across cane juice, molasses, maize, and rice. China, Thailand, and Australia supply additional grain and cane-based volumes.
Balrampur Chini Mills plans to scale its distillery capacity to 1,050 kiloliters per day by fiscal 2027, and Godavari Biorefineries and BCL Industries have each added grain-based units. These sites also run biomass boilers and power units, which cuts fuel costs and carbon intensity. Japan and South Korea import ethanol for fuel and industrial use, while Southeast Asian countries are testing higher blends. Policy support for farmers who sell surplus grain to distilleries keeps feedstock supply steady, although grain price swings remain a risk.
⮞In July 2026, Godavari Biorefineries commissioned a 200 kiloliter-per-day grain and maize-based distillery at its Sameerwadi complex in Karnataka, raising site capacity to 800 kiloliters per day. The Rs 130 crore unit adds 60 million liters of annual ethanol capacity and works alongside sugarcane operations, allowing the complex to switch feedstocks by season.
Europe Ethanol Market Insights
Europe accounted for 14.31% of the Ethanol Market in 2025, equal to USD 14.85 Billion, and is projected to register a CAGR of 4.37% from 2026 to 2035. Output rests on wheat, maize, and sugar beet plants that serve fuel blending under renewable energy rules and sell neutral alcohol to food and beverage users. Growth is slower than the global rate because the vehicle fleet is mature and blend levels are already established. Germany contributes 27.16% of the regional total, supported by large integrated biorefineries.
CropEnergies, part of Südzucker, operates the large Zeitz site and is expanding into chemicals through green ethyl acetate. Lantmännen Agroetanol runs the Norrköping biorefinery in Sweden, described as the Nordic region's largest ethanol producer with 230,000 cubic meters of annual output, while Tereos produces bioethanol and alcohol from beet and cereals in France. Verbio, a German producer, operates biorefineries in Europe and North America. European producers therefore compete on carbon footprint, protein coproducts, and chemical-grade outlets rather than on volume.
⮞In April 2024, CropEnergies held the ground-breaking ceremony for Europe's first production plant for green ethyl acetate at the Zeitz Chemical and Industrial Park in Saxony-Anhalt. The company is investing between 120 million and 130 million euros in the plant, which uses sustainable ethanol as its raw material, with commissioning planned for the end of 2025.
MEA & Latin America Ethanol Market Insights
The Middle East & Africa accounted for 2.31% of the Ethanol Market in 2025, equal to USD 2.40 Billion, and is projected to register a CAGR of 6.47% from 2026 to 2035. South Africa contributes 34.98% of the regional total through sugar-linked distilleries and industrial alcohol suppliers. Sugar producers in East Africa are adding alcohol units to process molasses locally, as TPC is doing in Tanzania, and governments are studying fuel blending and clean cooking programs. Growth is fast from a small base, but projects are modest in scale and depend on molasses supply and financing.
In November 2025, TPC Limited announced a USD 52 million investment to modernize its sugar operations in Tanzania and add ethanol production of 16.30 million liters a year of extra neutral alcohol, plus 400,000 liters of technical alcohol intended for clean cooking stoves. The expansion is scheduled to start operating by the end of December 2026.
Latin America held 19.83% of the Ethanol Market in 2025, equal to USD 20.57 Billion, and is projected to register a CAGR of 6.04% from 2026 to 2035. Brazil contributes 88.23% of the regional total, where sugarcane mills and a fast-growing corn ethanol industry supply anhydrous and hydrous fuel. Raízen and Inpasa lead capacity additions, and higher gasoline blends and flex-fuel cars keep demand strong. Argentina and Colombia add smaller volumes, and growth depends on harvest conditions, sugar prices, and the pace of new corn plants.
⮞In March 2026, Inpasa started operations at its new corn ethanol plant in western Bahia, Brazil, rated at about 470 million liters a year. The company secured BNDES financing of R$950 million for the biorefinery in January 2026, and the plant is expected to reach maximum capacity in 2027.
Market Dynamics
Growth Drivers: Rising Gasoline Blending Mandates and Low-Carbon Fuel Incentives
Rising gasoline blending mandates are the first driver, because governments use ethanol to cut oil imports, lift octane, and support farm incomes. India is steering oil marketing companies toward E20 and has prompted distilleries such as BCL Industries and Godavari Biorefineries to add hundreds of kiloliters per day of grain-based capacity. Brazil has raised its gasoline blend, and U.S. refiners keep blending at the E10 level while E15 expands. Mandates create reliable offtake, which lets lenders finance new plants and keeps utilization high across cycles.
Low-carbon fuel incentives form the second driver. The 45Z clean fuel production credit rewards plants that lower carbon intensity, and The Andersons reported USD 24.00 million of 45Z credits in its second quarter of 2026. Carbon capture projects such as those at Nebraska plants of ADM and Green Plains, and Gevo's capture-equipped Richardton site, let producers sell lower-carbon ethanol at premiums. These incentives also support investment in efficiency upgrades, renewable power, and sustainable aviation fuel pathways, which broadens demand beyond gasoline.
⮞In July 2026, BCL Industries announced completion and commissioning of a 150 kiloliter-per-day expansion at its Bathinda, Punjab, grain-based distillery, lifting capacity from 400 to 550 kiloliters per day. The distillery uses maize and rice and targets rising demand from oil marketing companies and India's E20 blending target.
Restraints: Feedstock Price Volatility and Oversupply and Flat Gasoline Demand
Feedstock price volatility restrains margins, because corn, sugarcane, and wheat account for most of a plant's cost and weather can move prices sharply. A plant such as Cardinal Ethanol's processes about 65 million bushels of corn a year, so small price swings alter profit materially. Indian producers face grain price changes and shifting official procurement prices, as BCL Industries notes among its risks. Producers hedge corn and ethanol, yet the hedges cost money and cannot offset multi-season shocks, which discourages expansions among smaller operators.
Opportunities: Second-Generation and Upgraded Ethanol Products and High-Purity Alcohol Demand
Second-generation ethanol and upgraded products open a larger addressable pool. Raízen is commissioning plants that turn bagasse into cellulosic ethanol, Gevo is planning low-carbon ethanol as a feedstock for sustainable aviation fuel, and CropEnergies is converting ethanol into green ethyl acetate for coatings and inks. These routes use residues rather than food crops, earn lower carbon intensity scores, and sell at premiums to commodity fuel ethanol. Technology owners also gain licensing and catalyst revenue, while producers diversify beyond gasoline blending and reduce exposure to fuel price cycles.
High-purity alcohol demand offers a second path. Greenfield Global's agreement with Show Me Ethanol broadens its USP, FCC, and ACS supply, and Alto Ingredients lifted second-quarter 2026 specialty alcohol volume above year-earlier levels. Pharmaceutical, cosmetic, sanitizer, and beverage buyers pay for purity, traceability, and reliable delivery, which supports healthier margins than fuel grades and steadier revenue through fuel price cycles. Producers that add rectification, dehydration, and quality systems can lock in multi-year accounts, qualify for regulated customers, and shift output toward these higher-value grades.
⮞In November 2024, Raízen began testing and commissioning two new second-generation ethanol plants at its Univalem park in Valparaíso and Barra park in Barra Bonita, São Paulo, each with nominal capacity of 82 million liters a year. The company expects to become the largest cellulosic ethanol producer, with four large-scale second-generation plants totaling 278 million liters of nominal capacity.
Recent Developments:
-
August 2026: Aemetis reported second-quarter ethanol sales of 15.50 million gallons from its Keyes, California, plant, which ran above its nameplate capacity. The company expects a mechanical vapor recompression upgrade at Keyes to become operational in 2026, replacing most of the plant's natural gas use with solar and grid electricity.
-
August 2026: Green Plains reported second-quarter ethanol production of 160.70 million gallons from eight operating plants running at high utilization. The company runs carbon capture at its three Nebraska plants and booked USD 58.70 million of net 45Z production tax credit value in the quarter.
Ethanol Market Key Players are:
-
POET, LLC
-
Archer Daniels Midland Company
-
Valero Energy Corporation
-
Green Plains Inc.
-
Raízen S.A.
-
Alto Ingredients, Inc.
-
Aemetis, Inc.
-
Verbio SE
-
CropEnergies AG (Südzucker Group)
-
Tereos
-
Lantmännen Agroetanol
-
Inpasa
-
Godavari Biorefineries Limited
-
BCL Industries Limited
-
The Andersons, Inc.
-
Balrampur Chini Mills Limited
-
Cargill, Incorporated
-
Flint Hills Resources
-
Abengoa Bioenergy
-
The Praj Industries Limited
Ethanol Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 103.74 Billion |
| Market Size by 2035 | USD 179.40 Billion |
| CAGR | 5.63% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source: Dominant – Grain-Based (63.47% share in 2025); Fastest-Growing – Sugar & Molasses-Based (CAGR 6.38%) • By Purity: Dominant – Denatured (67.28% share in 2025); Fastest-Growing – Undenatured (CAGR 6.74%) • By Application: Dominant – Fuel & Fuel Additives (58.36% share in 2025); Fastest-Growing – Beverages (CAGR 6.91%) • By End-Use: Dominant – Transportation (61.74% share in 2025); Fastest-Growing – Pharmaceuticals & Healthcare (CAGR 7.03%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | POET, LLC, Archer Daniels Midland Company, Valero Energy Corporation, Green Plains Inc., Raízen S.A., Alto Ingredients, Inc., Aemetis, Inc., Verbio SE, CropEnergies AG (Südzucker Group), Tereos, Lantmännen Agroetanol, Inpasa, Godavari Biorefineries Limited, BCL Industries Limited, The Andersons, Inc., Balrampur Chini Mills Limited, Cargill, Incorporated, Flint Hills Resources, Abengoa Bioenergy, The Praj Industries Limited |

Frequently Asked Questions
Key players include POET, LLC, Archer Daniels Midland Company, Valero Energy Corporation, Green Plains Inc., and Raízen S.A., among others.
Second-generation and low-carbon ethanol, upgraded products such as sustainable aviation fuel feedstock and green ethyl acetate, and high-purity alcohol for pharmaceutical, beverage, and personal care buyers represent the primary opportunities.
Growth is primarily driven by rising gasoline blending mandates in the United States, Brazil, and India, reinforced by low-carbon fuel incentives that reward carbon capture and lower carbon intensity.
By Source, Grain-Based ethanol dominated the market with approximately 63.47% share in 2025, reflecting the scale of corn and wheat plants in North America and Europe and new maize distilleries in India and Brazil.
North America dominated the market with approximately 46.21% share in 2025, driven by the large U.S. corn ethanol base, steady gasoline blending, and growing exports.
