
Bioplastics Market Report Scope & Overview:
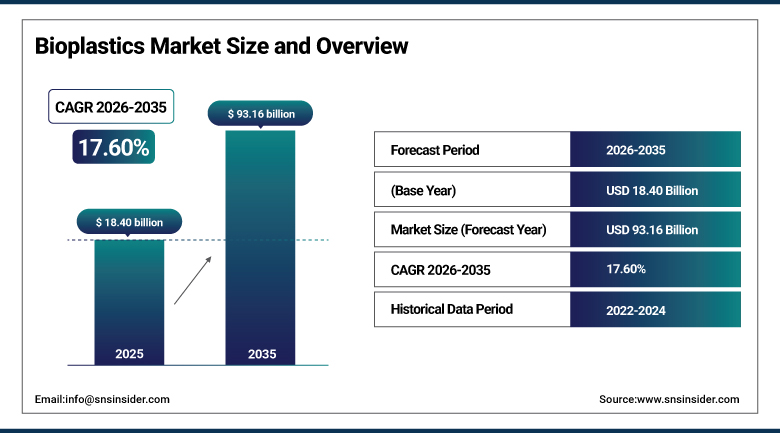
The Bioplastics Market was valued at USD 18.40 Billion in 2025 and is expected to reach USD 93.16 Billion by 2035, growing at a CAGR of 17.60% from 2026 to 2035.
The use of bioplastics has become quite significant within the overall plastic industry, which produces renewable and, in most cases, biodegradable substitutes for petroleum-based polymers used in packaging, agricultural, automotive, electronic, and textile industries. The demand for bioplastics is relatively limited to packaging, foodservice, flexible packaging, and consumer goods, but increasing numbers of agricultural, textile, automotive, and medical sectors are switching to bioplastics because of the growing need for environmental sustainability and the implementation of waste management policies.
In 2026, TotalEnergies Corbion and Benvic joined efforts to develop low-carbon compounds for use in automotive and electronics industries, among others, and thus demonstrate how much the industry itself tends to move out of the sphere of packaging into more valuable areas.
Market Size and Forecast
-
Market Size in 2026E: USD 21.70 Billion
-
Market Size by 2035: USD 93.16 Billion
-
CAGR: 17.60% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: Europe
To Get more information Bioplastics Market - Request Free Sample Report
Bioplastics Market Trends
-
Growing surge in personal protective equipment and post-pandemic preference for packaged food is reinforcing demand for biodegradable plastic materials.
-
Rising strategic collaborations between bioplastic producers and packaging converters are deepening life-cycle transparency and carbon footprint labeling adoption.
-
Expanding automotive and electronics sector adoption is broadening bioplastics applications beyond traditional packaging and consumer goods.
-
Increasing PHA material investment is capitalizing on its fully biodegradable nature and expanding applications across medical and specialty categories.
-
Growing industry advocacy for domestic production incentives, including tariff support, is reshaping regional supply chain strategy for PLA producers.
U.S. Bioplastics Market Outlook
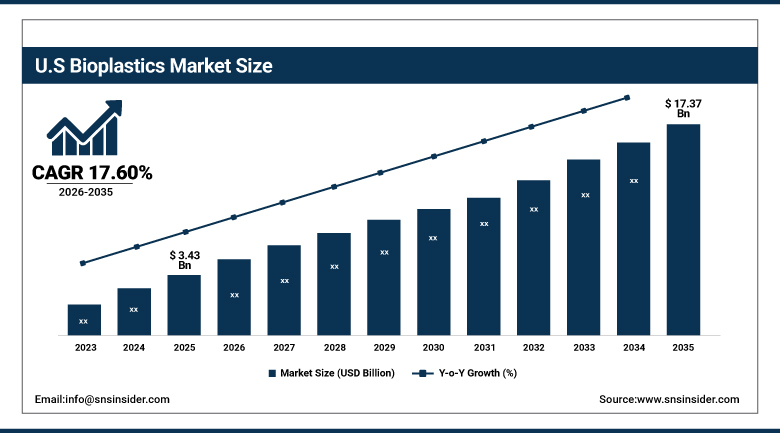
The U.S. Bioplastics Market was valued at USD 3.43 Billion in 2025 and is projected to reach USD 17.37 Billion by 2035, growing at a CAGR of 17.60% during 2026-2035.
The increasing regulatory backing and consumers' rising inclination towards using environment-friendly goods keep driving strong market growth throughout the United States. The leading companies keep increasing production capacity, research efforts, and innovation in materials to enhance heat-resistance, durability, and recycling capability in their bioplastic products. The increasing interest in the supply chain resilience of the industry in light of growing competition from overseas competitors continues to strengthen the efforts to make advanced bioplastic manufacturing possible in the country.
NatureWorks advocated for tariffs in 2026 in an effort to revive the U.S. PLA industry in light of growing interest in supply chain resilience of the industry as the leading bioplastic producers in the United States keep experiencing intense competition from overseas companies while investing in manufacturing expansion and innovation throughout the country.
Bioplastics Market Segment Analysis
-
By Product Type, Biodegradable led the Bioplastics Market with a 50.10% share in 2025, while Non-biodegradable is the fastest-growing product type segment with a CAGR of 19.80% from 2026-2035.
-
By Material Type, PLA led the Bioplastics Market with a 32.60% share in 2025, while PHA is the fastest-growing material type segment with a CAGR of 21.40% from 2026-2035.
-
By Application, Packaging led the Bioplastics Market with a 61.29% share in 2025, while Automotive & Transportation is the fastest-growing application segment with a CAGR of 20.60% from 2026-2035.
By Product Type, Biodegradable Dominated the Market While Non-biodegradable Is the Fastest-Growing Segment
The Biodegradable segment occupied the leading position in the Bioplastics Market with a revenue share of 50.10% in 2025, due to increasing demands for personal protective equipment and continued preferences for packed food post pandemic, that has continued to boost the utilization of biodegradable plastics. Increasing demands for bio-plastics in various end-use industries, owing to their re-usability and speedy degradation, continues to drive the leading revenue generation of biodegradable material in the bioplastics market.
The Non-biodegradable segment is anticipated to witness a higher CAGR of 19.80% over the forecast period 2026-2035, owing to the increasing usage of bio-based, drop-in material such as bio-polyethylene and bio-polyamide in the interior components of automotive, bottles, food packaging, shopping bags, and electronics applications. Increasing preferences for materials that can be recycled using the existing infrastructure continues to favor the non-biodegradable segment with its high growth rate.
By Material Type, PLA Dominated the Market While PHA Is the Fastest-Growing Segment
The PLA segment led the Bioplastics Market with a revenue share of 32.60% in 2025, reflecting polylactic acid's established commercial-scale production infrastructure and broad application versatility across packaging, food service, and 3D printing filament markets. PLA continues to benefit from an extensive global producer base and proven manufacturing scale advantages, sustaining this material type's dominant position across the broader bioplastics market worldwide.
The PHA segment is expected to register the fastest CAGR of 21.40% during the forecast period 2026-2035, driven by growing capitalization on polyhydroxyalkanoates' fully biodegradable nature and expanding applications across medical, specialty packaging, and marine-safe product categories. Rising investment in scaling PHA production technology continues to reinforce this segment's above-average growth trajectory relative to more established bioplastic materials.
By Application, Packaging Dominated the Market While Automotive & Transportation Is the Fastest-Growing Segment
The Packaging segment held the largest revenue market share of 61.29% in the Bioplastics Market in 2025 due to the extensive utilization of bioplastics in films, sheets, household care products, food and beverages packaging, and personal care products. The top bioplastics used for packaging, including starch composites, PET, PLA, PBAT, PE, and PBS, will keep the leading position of packaging in the overall bioplastics application segment due to increasing demands for sustainable, environment-friendly packaging materials globally.
The Automotive & Transportation segment is projected to exhibit the highest CAGR of 20.60% during the forecast period from 2026 to 2035 owing to increasing automotive sector usage of bio-based composites and components that help in reducing the weight of vehicles. Increasing collaborations in developing low-carbon composites for automotive and electronics application segments are boosting the performance of this segment compared to traditional packaging application segments.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
26.40% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
38.60% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
28.60% |
North America Bioplastics Market Insights
North America was a considerable proportion of the Global Bioplastics Market in 2025 due to increasing regulation support and increased consumer preferences for environmentally friendly products. Increased focus on building resilient domestic supply chains is driving continuous investments into developing superior bioplastic production capabilities in an expanding regional production network.
The US comprised about 84.60% of the North American market in 2025 owing to the dominance of bioplastic producers in the country and increased regulation support for sustainable materials. The contributions of Canada to regional growth have been in terms of sustainable packaging adoption and increased consumer preferences for environmentally friendly products.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Bioplastics Market Insights
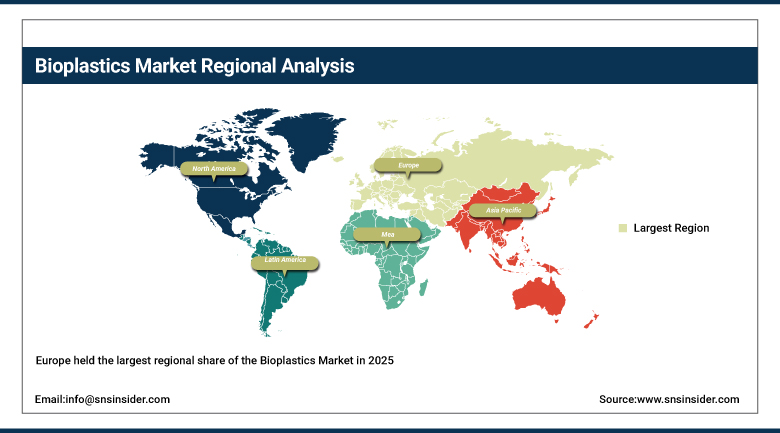
Europe held the largest regional share of the Bioplastics Market in 2025, driven by strict environmental policies and sustainability initiatives across major member states. Stringent restrictions on single-use plastic, extended producer responsibility frameworks, and bio-preferred procurement mandates continue to strongly support bioplastics adoption and reinforce the region's leadership position across the broader bioplastics landscape.
Germany led the European market with a 26.40% regional share in 2025, supported by its strong domestic bioplastic manufacturing base and rigorous environmental regulatory framework. France, the Netherlands, and Italy are also contributing meaningfully to regional growth, supported by leading bioplastic producers headquartered across the region and expanding sustainable packaging retail penetration.
Asia Pacific Bioplastics Market Insights
Asia Pacific is expected to witness strong growth during the forecast period 2026-2035, driven by expanding production capacity and increasing demand across China, Japan, South Korea, and Thailand. Leading bioplastic producers continue deepening their footprint through strategic collaborations with packaging converters and foodservice brands, aligning with the region's tightening sustainability mandates.
China accounted for approximately 38.60% of the Asia Pacific market in 2025, supported by its rapidly expanding domestic bioplastic manufacturing capacity and growing government sustainability policy support. Japan, South Korea, and Thailand are also contributing meaningfully to regional growth, with Thailand serving as a strategic production hub for leading global PLA manufacturers serving Southeast Asian and Indian markets.
Middle East & Africa and Latin America Bioplastics Market Insights
The Middle East & Africa region is showing a constant trend for growth because of the growing sustainability projects and investments in modern retail infrastructures in the Gulf states. Latin America region is also experiencing the same trends due to increased use of sustainable packaging because of the availability of sugarcane feedstocks which can be used in the production of bio-based polymers.
In 2025, the UAE had a 20.60% regional market share in the Middle East & Africa region due to the increase in the sustainability projects in retail infrastructure. In 2025, Brazil accounted for 28.60% of the Latin American market share due to the presence of the sugarcane feedstock that helps produce bio-based polyethylene.
Growth Drivers: Environmental Sustainability Awareness and Regulatory Support Driving Market Growth
The growth of the Bioplastics Market can be attributed largely to rising demand for sustainable packaging solutions, rising consciousness among consumers about environmental sustainability, and introduction of stringent waste management and emissions regulations. As less than 10% of plastic waste generated in the world is being recycled today, consumers have started opting for sustainable options, which is evident from rising demand for eco-friendly packaging in food & beverages, personal care, and consumer goods segments worldwide.
Rising demand for personal protective equipment and packaged foods due to the pandemic is driving the adoption of biodegradable plastic materials. Rising number of strategic partnerships between bioplastic manufacturers and packaging converters is helping in enhancing life cycle visibility and carbon footprint labeling. Growth in the use of bioplastics in the automotive and electronics industries has increased the applications of bioplastics beyond consumer goods packaging.
Restraints: Higher Production Costs and Limited Composting Infrastructure Limiting Market Expansion
Despite the positive underlying demand trends, the market continues to face significant challenges associated with higher cost of production relative to petrochemical-based plastics, and this continues to act as a deterrent especially for price-sensitive producers and consumers in developing countries. The lack of composting facilities in many countries continues to be a factor that hampers the potential end-of-life advantages of biodegradable bioplastics when disposed improperly.
The production scalability issues continue to affect the speed at which manufacturers can ramp up their production capacity to meet the rising demands, particularly for the new types of bioplastics such as PHA. The performance restrictions of certain bioplastic materials in some challenging applications coupled with stiff competition among producers and price competition also continue to reduce margins.
Opportunities: Automotive Sector Expansion and Domestic Manufacturing Investment Creating New Growth Avenues
The potential in further growth within automotive and electronic applications is high as bio-composites and bio-components provide an avenue through which automobile manufacturers can reduce their vehicle weight and environmental impact while also conforming to sustainability regulations. Businesses capable of effectively developing bioplastics that match the required performance levels will be able to gain significant market share in their category.
Another avenue of growth open to producers of bioplastics is the industry push towards incentives for domestic manufacturing, especially through the influence of tariffs in altering regional supply chain strategy. The growth potential in increasing investments in PHA manufacturing technology, as well as initiatives in sustainability, is substantial and currently untapped.
Recent Developments:
-
2026: NatureWorks advocated for tariffs to help rebuild the U.S. PLA sector, reflecting growing industry attention to domestic supply chain resilience.
-
2026: TotalEnergies Corbion and Benvic teamed up to expand low-carbon compound offerings for automotive and electronics applications, among other end markets.
-
2026: Ecovia Bio expanded its biopolymer production with new funding, reflecting continued investor confidence in scaling next-generation bioplastic manufacturing capacity.
-
2026: NatureWorks deepened its Asia Pacific footprint through strategic collaborations with packaging converters and foodservice brands in Japan, South Korea, and Thailand.
Bioplastics Companies are:
-
NatureWorks LLC
-
BASF SE
-
Novamont S.p.A.
-
TotalEnergies Corbion
-
Mitsubishi Chemical Group Corporation
-
Biome Bioplastics Limited
-
FKuR Kunststoff GmbH
-
Danimer Scientific, Inc.
-
Green Dot Bioplastics, Inc.
-
Cardia Bioplastics Limited
-
Plantic Technologies Limited
-
Kaneka Corporation
-
Toray Industries, Inc.
-
Corbion N.V.
-
DuPont de Nemours, Inc.
-
Avantium N.V.
-
Arkema S.A.
-
PTT MCC Biochem Co., Ltd.
Bioplastics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.40 Billion |
| Market Size by 2035 | USD 93.16 Billion |
| CAGR | CAGR of 17.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Biodegradable, Non-biodegradable) • By Material Type (PLA, Starch Blends, PBAT, Bio-PE, Bio-PET, PHA) • By Application (Packaging, Agriculture, Automotive & Transportation, Electronics, Textile) • By Region |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | NatureWorks LLC, BASF SE, Novamont S.p.A., Braskem S.A., TotalEnergies Corbion, Mitsubishi Chemical Group Corporation, Biome Bioplastics Limited, FKuR Kunststoff GmbH, Danimer Scientific, Inc., Green Dot Bioplastics, Inc., Cardia Bioplastics Limited, Plantic Technologies Limited, Kaneka Corporation, Toray Industries, Inc., Corbion N.V., Eastman Chemical Company, DuPont de Nemours, Inc., Avantium N.V., Arkema S.A., PTT MCC Biochem Co., Ltd. |
Frequently Asked Questions
The Bioplastics Market is expected to grow at a CAGR of 17.60% from 2026 to 2035.
The Bioplastics Market was valued at USD 18.40 Billion in 2025.
The market is driven by increasing demand for eco-friendly and sustainable packaging solutions, growing environmental sustainability awareness, and stricter waste management regulations.
The Packaging segment dominated the Bioplastics Market in 2025, accounting for approximately 61.29% market share.
The Europe region dominated the Bioplastics Market in 2025.
