
Superconducting Wire Market Report Scope & Overview:
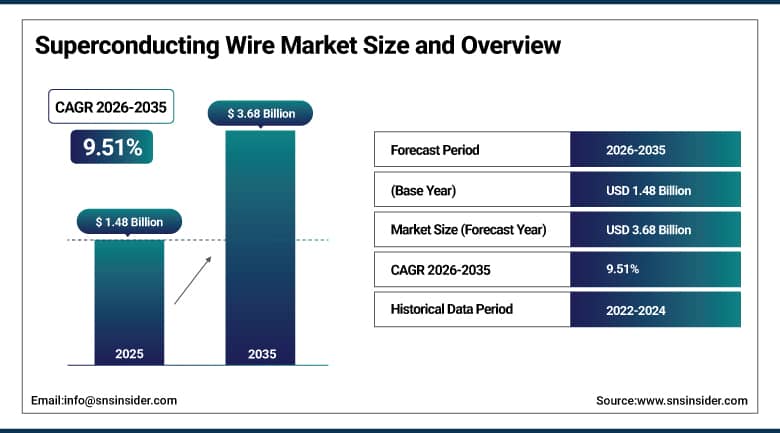
The Superconducting Wire Market was valued at USD 1.48 Billion in 2025 and is expected to reach USD 3.68 Billion by 2035, growing at a CAGR of 9.51% from 2026-2035.
Superconducting wire enables electrical current transmission with virtually zero electrical resistance when operated below its critical temperature, significantly reducing energy losses associated with conventional conductors such as copper and aluminum. This capability supports highly efficient power transmission, high-field magnetic systems, and advanced electrical infrastructure. Growing adoption across magnetic resonance imaging (MRI), smart grid modernization, research facilities, and nuclear fusion projects is expanding the commercial application of superconducting wire beyond laboratory environments. Its ability to generate powerful magnetic fields while minimizing electrical losses makes it particularly valuable in performance-intensive applications. However, superconducting systems generally require cryogenic cooling infrastructure, which increases installation costs and operational complexity. Despite these challenges, continued technological development and investment in advanced energy and medical systems are supporting steady demand for superconducting wire technologies.
Sumitomo Electric established an innovative joint venture with a major renewable energy company in January 2024 aimed at advancing next-generation superconductor technology specifically for grid applications. Partnerships like this matter because superconducting wire's promise for power grid modernization has always come with a catch, integrating it into existing utility infrastructure requires deep collaboration between superconductor specialists and companies who actually understand grid operations at scale, and this kind of joint venture is exactly the sort of practical, execution-focused partnership that tends to move a promising technology from pilot projects toward genuine commercial deployment.
To Get More Information On Superconducting Wire Market - Request Free Sample Report
Superconducting Wire Market Trends
-
Rising adoption of high-temperature superconductor wire offering easier cooling requirements than traditional low-temperature alternatives.
-
Growing investment in nuclear fusion research programs requiring specialized high-current-density superconducting wire.
-
Expanding smart grid modernization initiatives incorporating superconducting fault current limiters and transmission cable technology.
-
Increasing use of superconducting wire in quantum computing applications requiring precise, low-loss signal transmission.
-
Rising collaboration between superconductor manufacturers and renewable energy companies advancing grid-scale applications.
-
Growing research into cost-effective manufacturing processes aimed at reducing superconducting wire production expenses.
U.S. Superconducting Wire Market Outlook
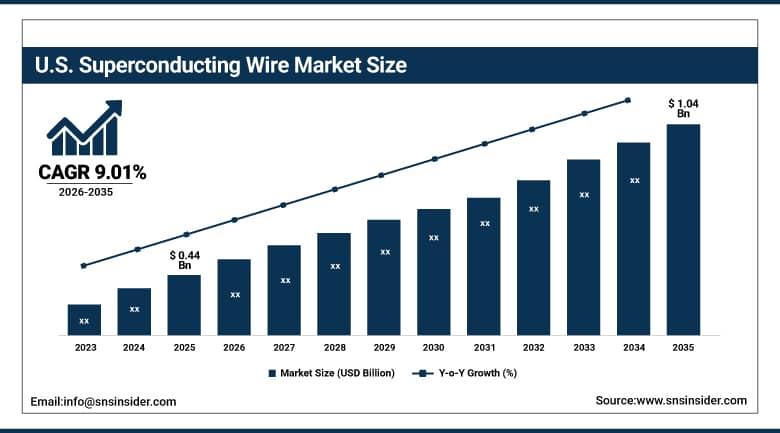
The U.S. Superconducting Wire Market was valued at USD 0.44 Billion in 2025 and is expected to reach USD 1.04 Billion by 2035, growing at a CAGR of 9.01% from 2026-2035.
The United States continues benefiting from decades of accumulated research and development investment in superconductor technology, alongside strong healthcare infrastructure that keeps MRI systems, one of the largest established applications for superconducting wire, in steady demand nationwide. Domestic strength in nuclear fusion research programs continues reinforcing demand too, as increasing investment in fusion energy development requires the specialized high-current-density superconducting wire that only a handful of manufacturers worldwide can reliably produce. Early adoption of superconducting technology across industries, paired with extensive research infrastructure at national laboratories and universities, continues keeping the domestic market at the technical forefront of the broader global industry.
American Superconductor Corporation keeps providing superconducting wire technology for the construction of renewable energy infrastructure for the energy grid, as American Superconductor Corporation had already participated in developing the Tres Amigas Project – the first renewable energy market hub project in the United States created to interconnect different power grids in the country. Participation of American Superconductor Corporation in the development of such a large scale renewable energy infrastructure demonstrates the connection between the internal demand for superconducting wire technologies and the energy transition process itself.
Superconducting Wire Market Segment Analysis
-
By Type, the Low-Temperature Superconductor segment dominated the Superconducting Wire Market with approximately 44.60% share in 2025, while the High-Temperature Superconductor segment is the fastest growing with a CAGR of approximately 10.83%.
-
By Application, the Magnetic Resonance Imaging segment dominated the Superconducting Wire Market with approximately 32.60% share in 2025, while the Power Grid Infrastructure segment is the fastest growing with a CAGR of approximately 11.20%.
-
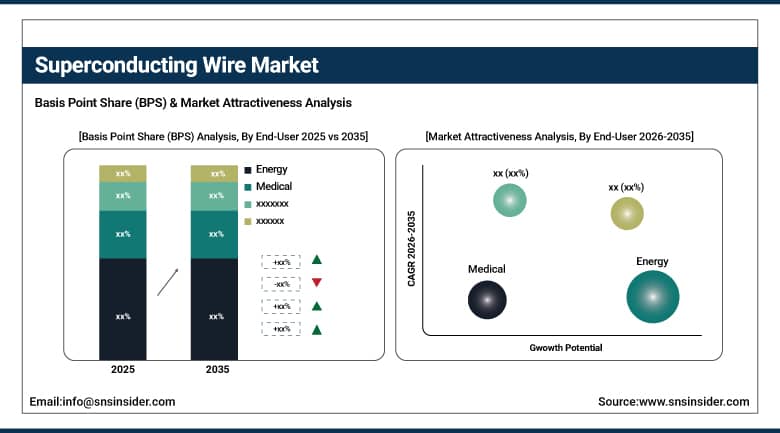
By End-User, the Energy segment dominated the Superconducting Wire Market with approximately 35.60% share in 2025, and is also the fastest growing with a CAGR of approximately 11.34%.
By End-User, Energy Dominates the Superconducting Wire Market and Also Grows Fastest
In terms of end-user, the energy sector emerges as the dominant end-user for superconducting wire, primarily due to increasing demand for high tensile strength cables by wind turbine manufacturers and renewable energy infrastructure developers. With the increasing adoption of renewable energy around the globe, the energy sector's usage of superconducting wire for generating and transmitting electricity helps ensure that the energy sector maintains its leading end-user position.
Moreover, the energy sector remains the fastest-growing end-user as well, owing to the continued deployment of renewables and investments into smart grids. The existing dominance combined with the anticipated high growth rate further cements the role of superconducting technology in the energy transition process, and thus helps ensure the future dominance of the energy sector as an end-user category.'
By Type, Low-Temperature Superconductor Dominates the Superconducting Wire Market and High-Temperature Superconductor Grows Fastest
Low-temperature superconductors hold the largest share of this market, benefiting from decades of established manufacturing experience and a proven track record across MRI systems, research magnets, and other applications where the technology's performance and reliability have been thoroughly validated over many years of commercial use. That mature manufacturing base and well-understood performance profile continues making low-temperature superconductors the default choice for applications where established reliability matters more than cutting-edge efficiency.
High-temperature superconductors are the fastest-growing type, offering a genuinely meaningful practical advantage, they require less extreme, less expensive cooling than low-temperature alternatives, which opens the door to a broader range of commercially viable applications. As fusion energy research, quantum computing, and grid infrastructure projects increasingly favor this easier-to-deploy technology, high-temperature superconductor demand continues climbing faster than the more established low-temperature category, even as it works to close the remaining performance gap in certain demanding applications.
By Application, Magnetic Resonance Imaging Dominates the Superconducting Wire Market and Power Grid Infrastructure Grows Fastest
Magnetic resonance imaging represents the largest application for superconducting wire, reflecting the technology's foundational and long-established role in producing the powerful, stable magnetic fields that MRI machines require to generate diagnostic images. The steady, ongoing global demand for medical imaging equipment, combined with MRI's decades-long reliance on superconducting magnet technology, continues sustaining this application's position as the largest source of superconducting wire demand worldwide.
Power grid infrastructure is the fastest-growing application, as rising investment in smart grid modernization continues creating genuine opportunity for superconducting fault current limiters and transmission technology capable of improving grid reliability and efficiency. As countries around the world increasingly recognize the need to modernize aging electrical grids, substantial funding continues flowing toward advanced technologies including superconducting wire, positioning power grid infrastructure as an increasingly significant demand driver alongside the market's more established medical imaging foundation.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Superconducting Wire Market Insights
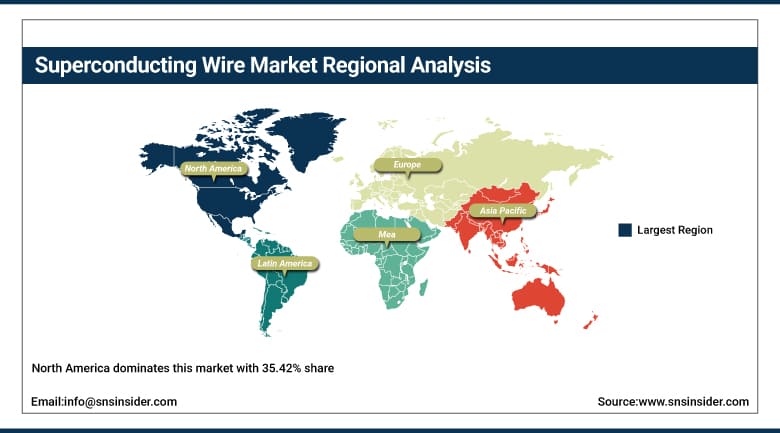
North America dominates this market with 35.42% share, anchored by the United States' strong investments in advanced research, healthcare infrastructure, and energy innovation programs. The region's early adoption of superconducting wire across multiple industries, combined with extensive research and development activity at national laboratories and leading universities, continues reinforcing North America's position as the largest regional market for superconducting wire.
Increasing investment in nuclear fusion-based research continues meaningfully impacting the region's superconducting wire demand, as fusion energy programs require the specialized, high-performance wire that only a limited number of manufacturers worldwide can reliably supply. Canada is contributing incremental regional demand as its own research and energy sectors continue developing, with continued domestic investment expected to sustain North America's leading position through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Superconducting Wire Market Insights
Asia Pacific has the highest rate of growth compared to all other regions due to the growth in the health care, automobiles, and electronics industries in the region and the rising usage of superconducting products within applications in energy and transportation. The large manufacturing industry in China and the rising research facilities are driving regional demand, thanks to the growing government funding for material sciences and energy innovations.
The Japan SCMAGLEV system is an example of how Japan is taking the lead in using the superconducting maglev trains, showing that the region is using superconducting wires not only in energy and medical applications. South Korea is another contributor to the region through its electronics and industrial manufacturing industry which are using superconducting technology.
Europe Superconducting Wire Market Insights
Europe represents a significant share of the global superconducting wire market, supported by large-scale fusion and particle accelerator research programs that continue requiring specialized, high-performance superconducting wire. The region's deep scientific research infrastructure, spanning major international collaborations, continues anchoring sustained demand for advanced superconductor technology.
Germany's substantial industrial and research base contributes significantly to regional demand, while collaborative projects like the HTS4Fusion initiative continue advancing high-temperature superconductor innovation specifically for fusion energy applications. Continued European investment in fusion research and grid modernization is expected to sustain steady regional growth through the forecast period.
MEA & Latin America Superconducting Wire Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing research and energy infrastructure investment across the United Arab Emirates and Saudi Arabia sustains gradual interest in advanced superconducting technology. Regional research infrastructure remains considerably less developed relative to established markets, with most sophisticated applications continuing to rely on imported technology and expertise.
Latin America's market remains at an early stage of development, with Brazil contributing incremental growth as regional research and energy infrastructure continue to expand gradually. Regional governments continue exploring superconducting technology investment as part of broader energy modernization strategies, though commercial-scale adoption across the region remains considerably earlier-stage relative to more established markets.
Market Dynamics
Growth Drivers: Renewable Energy Integration and Medical Imaging Demand
The ability of superconducting wire to facilitate zero resistance in transferring electrical current constitutes the key factor contributing to the expansion of the market, since such technological efficiency is still highly appealing for such applications as renewable energy integration and modernization of the smart grid system. The expansion of renewable energy systems, as well as the electrification of power systems globally, will help increase the demand for superconducting wire that provides more efficient power transfer.
The development of medical imaging systems, fusion energy technologies, and transportation systems is another key factor contributing to the expansion of the market, since all these applications depend on the unique capabilities of superconducting wire. Improvements in material science, as well as continued investments in scientific research by governments, will continue broadening the range of commercial applications of superconducting wire technologies.
Restraints: High Production Costs and Cryogenic Cooling Requirements
High production costs represent a meaningful restraint on market growth, with a substantial share of companies reporting genuine difficulty managing the specialized manufacturing processes and materials required for reliable superconducting wire production. These elevated costs continue limiting broader commercial adoption, particularly for applications where conventional copper or aluminum wiring remains adequate despite its efficiency disadvantages.
Cryogenic cooling system integration represents a further restraint, as a meaningful share of companies continue reporting genuine challenges incorporating the specialized cooling infrastructure superconducting wire requires to reach and maintain its critical operating temperature. This cooling requirement adds real cost and complexity relative to conventional wiring, continuing to constrain the pace at which superconducting technology can expand into more cost-sensitive applications.
Opportunities: High-Temperature Superconductor Innovation and Fusion Energy Investment
Continued advancement in high-temperature superconductor wire represents a substantial opportunity, as manufacturers that can successfully improve the price-performance profile of this easier-to-cool technology are positioned to capture demand across a genuinely broader range of commercial applications than low-temperature alternatives can economically address. Recent research breakthroughs in high-performing HTS wire segments continue improving the technology's competitive positioning relative to established alternatives.
The continued expansion of nuclear fusion research investment offers a further avenue for growth, as fusion energy programs worldwide continue requiring increasingly sophisticated, high-current-density superconducting wire to build the powerful magnetic confinement systems these projects depend on. Manufacturers that can reliably supply this specialized, demanding wire technology are well positioned to capture meaningful new demand as global fusion energy research investment continues its steady expansion.
Recent Developments:
-
In December 2024, THEVA Dünnschichttechnik GmbH collaborated with the Max-Planck-Institute for Plasma Physics and the Technical University of Munich's Forschungs-Neutronenquelle Heinz Maier-Leibnitz, launching the HTS4Fusion project to advance high-temperature superconductor innovations for fusion technology.
-
ASG Superconductors S.p.A. continued expanding its role supplying superconducting technology components for major fusion energy research projects.
-
Bruker's Energy & Supercon Technologies division continued fulfilling multi-year sales contracts supplying high-current-density superconductors for tokamak fusion projects across Europe and Asia.
Superconducting Wire Market Key Players
-
American Superconductor Corporation
-
Bruker Corporation
-
Furukawa Electric Co., Ltd.
-
Fujikura Ltd.
-
Sumitomo Electric Industries, Ltd.
-
ASG Superconductors SpA
-
Eaton Corporation plc
-
Fuji Electric Co., Ltd.
-
Superconductor Technologies Inc.
-
LS Cable & System Ltd.
-
THEVA Dünnschichttechnik GmbH
-
Nexans S.A.
-
Luvata Oy
-
Oxford Instruments plc
-
SuperPower Inc. (Furukawa)
-
Kiswire Advanced Technology Co., Ltd.
-
MetOx Technologies, Inc.
-
Japan Superconductor Technology Inc.
-
Prysmian Group
-
General Electric Company
Superconducting Wire Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.48 Billion |
| Market Size by 2035 | USD 3.68 Billion |
| CAGR | CAGR of 9.51% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Low-Temperature Superconductor, Medium-Temperature Superconductor, High-Temperature Superconductor) • By Application (Magnetic Resonance Imaging, Power Grid Infrastructure, Superconducting Fault Current Limiter, Maglev, Particle Accelerators, Fusion & High-Field Magnets) • By End-User (Energy, Medical, Transportation, Research) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | American Superconductor Corporation, Bruker Corporation, Furukawa Electric Co., Ltd., Fujikura Ltd., Sumitomo Electric Industries, Ltd., ASG Superconductors SpA, Eaton Corporation plc, Fuji Electric Co., Ltd., Superconductor Technologies Inc., LS Cable & System Ltd., THEVA Dünnschichttechnik GmbH, Nexans S.A., Luvata Oy, Oxford Instruments plc, SuperPower Inc. (Furukawa), Kiswire Advanced Technology Co., Ltd., MetOx Technologies, Inc., Japan Superconductor Technology Inc., Prysmian Group, General Electric Company |

Frequently Asked Questions
Key players include American Superconductor Corporation, Bruker Corporation, Furukawa Electric Co., Ltd., Fujikura Ltd., Sumitomo Electric Industries, Ltd., and ASG Superconductors SpA, among other advanced materials manufacturers.
Continued advancement in high-temperature superconductor wire and continued expansion of nuclear fusion research investment represent the biggest opportunities for manufacturers.
Growth is driven mainly by superconducting wire's ability to enable nearly zero resistance electricity transmission, combined with renewable energy integration and continued medical imaging demand.
By Type, Low-Temperature Superconductor held approximately 44.60% share in 2025, reflecting decades of established manufacturing experience and a proven commercial track record.
North America led with approximately 36.60% share in 2025, supported by strong investments in advanced research, healthcare infrastructure, and energy innovation programs.
