
Fashion Influencer Marketing Market Report Scope & Overview:
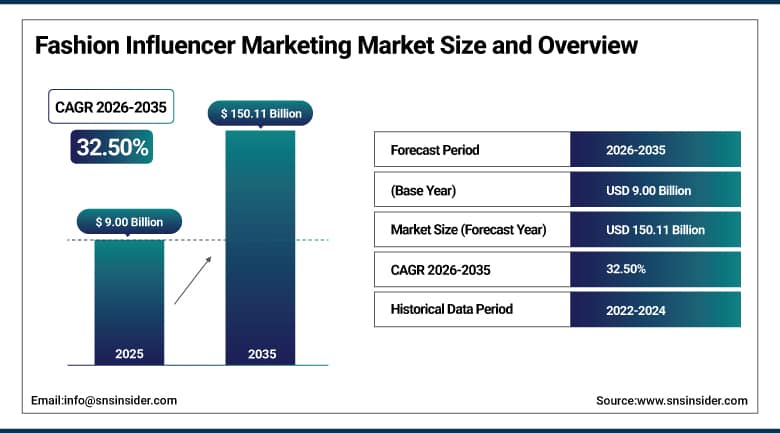
The Fashion Influencer Marketing Market was valued at USD 9.00 Billion in 2025 and is expected to reach USD 150.11 Billion by 2035, growing at a CAGR of 32.50% from 2026-2035.
The Fashion Influencer Marketing Market is growing rapidly as apparel, footwear, accessories and beauty brands shift advertising budgets toward creators who shape style choices on social platforms. Growth is driven by the rise of short-form video, social commerce, affiliate and shoppable content, and the strong trust that younger consumers place in peer recommendations over traditional advertising. Brands are moving from one-off campaigns to always-on creator programs, spreading budgets across many micro and nano creators and measuring results by sales rather than reach. Platforms, agencies and software providers are adding discovery, payment, rights management and analytics tools, and artificial intelligence is helping brands match creators to audiences and verify authenticity at scale. Retailers are turning creators into a permanent loyalty layer.
⮞In early February 2026, American Eagle relaunched its AE Creator Community with the brand ambassador platform SocialLadder, accepting creators with at least 1,000 followers and rewarding them with commission, product access, gifting and points redeemable for cash or merchandise. The program recorded 643 sign-ups within 24 hours and 803 after ten days, and the retailer plans to bring its 16 million U.S. and Canadian loyalty members into the community. The launch reflects a wider move from one-off influencer campaigns to always-on advocacy programs that combine loyalty mechanics with performance-based creator marketing.
To Get More Information On Fashion Influencer Marketing Market - Request Free Sample Report
Fashion Influencer Marketing Market Trends
-
Shift from one-off campaigns to always-on creator advocacy and loyalty programs
-
Growth of short-form video and shoppable content on social platforms
-
Rising use of micro and nano creators with close-knit communities and higher engagement
-
Adoption of artificial intelligence for creator discovery, matching and fraud detection
-
Growth of user-generated content and affiliate commission models
-
Measurement moving from reach and earned media value toward sales-linked metrics
U.S. Fashion Influencer Marketing Market Outlook
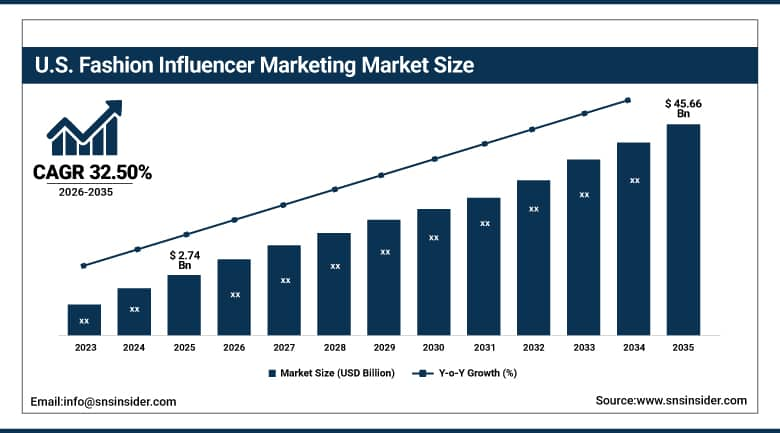
The U.S. Fashion Influencer Marketing Market was valued at USD 2.74 Billion in 2025 and is expected to reach USD 45.66 Billion by 2035, growing at a CAGR of 32.50% from 2026-2035.
The U.S. Fashion Influencer Marketing Market is the largest national market, supported by a deep base of apparel and beauty brands, mature social commerce platforms, a large creator economy and advanced measurement tools. Brands use creators for product launches, seasonal campaigns, affiliate programs and community building, and retailers are linking creator content directly to checkout through shoppable links and storefronts. Agencies, marketplaces and software companies compete to offer discovery, contracting, payments and analytics. Disclosure rules from the Federal Trade Commission require clear labeling of sponsored posts, and brands are strengthening compliance processes and creator contracts as the volume of partnerships grows.
⮞On September 1, 2026, LTK named 50 creators and 50 brands in its 2026 LTK Awards and reported that creators on its platform drive more than USD 6.00 billion in annual retail sales, that brands invested USD 450.00 million in LTK creators over the past twelve months, and that it works with more than 8,000 retailers. The company said nearly 40% of Gen Z and Millennial women in the United States use the platform, which has more than 44 million monthly users.
Fashion Influencer Marketing Market Segment Analysis
-
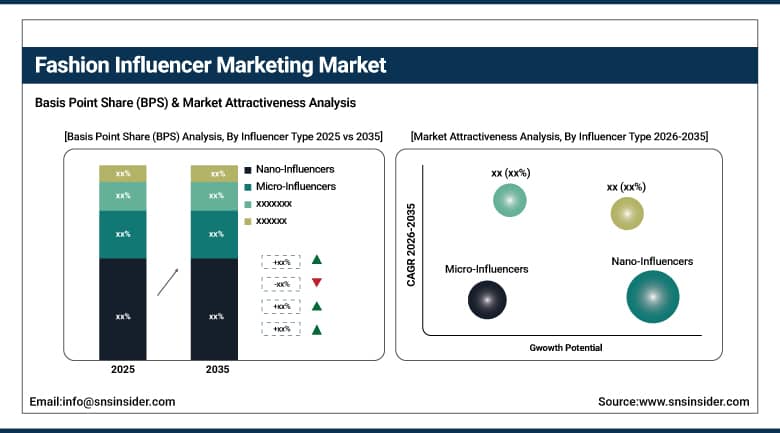
By Influencer Type, the Nano-Influencers segment dominated the Fashion Influencer Marketing Market with approximately 35.60% share in 2025, while the Micro-Influencers segment is the fastest growing with a CAGR of approximately 34.80%.
-
By Platform, the Instagram segment dominated the Fashion Influencer Marketing Market with approximately 49.50% share in 2025, while the TikTok segment is the fastest growing with a CAGR of approximately 38.40%.
-
By Campaign Type, the Sponsored Content segment dominated the Fashion Influencer Marketing Market with approximately 31.20% share in 2025, while the Brand Ambassadorships segment is the fastest growing with a CAGR of approximately 36.10%.
-
By Fashion Category, the Apparel segment dominated the Fashion Influencer Marketing Market with approximately 46.80% share in 2025, while the Jewelry and Accessories segment is the fastest growing with a CAGR of approximately 34.60%.
-
By End User, the Beauty and Cosmetic Companies segment dominated the Fashion Influencer Marketing Market with approximately 35.80% share in 2025, while the Fashion Brands segment is the fastest growing with a CAGR of approximately 35.40%.
By Influencer Type, Nano-Influencers Lead While Micro-Influencers Grow Fastest
Nano-influencers hold the leading position because brands are spreading budgets across many small creators who have close relationships with their followers. Their content feels personal, their rates are low, and many accept product gifting or commission instead of fixed fees, which lets brands run large programs at modest cost. Retailers and apparel labels use nano creators to generate user-generated content, reviews and local reach, and brand advocacy platforms make it easy to recruit and manage thousands of them. Industry data indicates that nearly four in five collaborations cost less than USD 300.00, showing how far the market has moved toward small-scale partnerships.
The micro-influencers are making the most progress in this regard as brands seek individuals who have sufficient influence on their followers to generate sales without losing credibility and engagement. They generally focus on a particular style of dressing, body type, or city/country. This makes it easier for brands to target specific markets like street wear, modest fashion, sustainable fashion, and resale fashion. The macro and mega influencers are still crucial for raising awareness at launch events or fashion weeks. Tools that measure sales contribution rather than follower counts are strengthening the case for smaller creators.
⮞In May 2026, Indian value-fashion retailer Style Baazar reported expanding its creator-led, community-first marketing strategy across Tier 2 and Tier 3 cities, combining regional storytelling, youth culture and hyperlocal campaigns. The company reported 4.1-fold year-on-year growth in creator-led organic reach.
By Platform, Instagram Leads While TikTok Grows Fastest
Instagram leads because it combines visual inspiration, shopping tags, stories, reels and creator marketplaces in a format that suits fashion. Brands have long used the platform for lookbooks, collaborations and product drops, and creators are comfortable producing polished photography and short video there. Integration with shopping features lets followers move from a post to a product page quickly, and detailed analytics support reporting to marketing teams. The platform remains the default channel for apparel, accessories and beauty campaigns across most regions.
The growth of TikTok happens as outfits and styles get viral with the young audience discovering new brands via algorithms, not following. Social commerce capabilities including live commerce and shoppable videos transform entertainment into a business, especially in Asia, and more and more in the West. YouTube has long-form reviews, hauls, and styling videos that have high search value for a longer period of time, while Pinterest and up-and-coming platforms help users to plan and find inspiration. Brands create one content piece and distribute it on various platforms; contracts stay flexible due to the quick changes in the regulatory environment.
⮞In May 2026, TikTok announced that TikTok Shop would expand into Austria, Belgium, the Netherlands and Poland from June 15, extending shoppable videos, livestream commerce and creator affiliate opportunities across additional European markets.
By Campaign Type, Sponsored Content Leads While Brand Ambassadorships Grow Fastest
Sponsored content leads because it is the simplest way to engage a creator for a defined deliverable such as a post, video or story, with clear pricing and disclosure. Brands use it for product launches, seasonal collections and promotions, and agencies can plan and measure these campaigns using established methods. Performance is judged by engagement, clicks and increasingly by attributed sales through tracked links and codes. The format suits both large and small creators and works across every major platform.
Brand ambassadorships are growing fastest as brands seek longer relationships that build familiarity and trust. Ambassadors appear across multiple seasons, take part in product development and events, and often receive commission, equity-like rewards or loyalty benefits. Affiliate marketing is expanding alongside this, paying creators for sales they drive, which aligns cost with results. Retailers are creating creator communities and advocacy hubs that blend gifting, content briefs and rewards. Such programs reduce the cost of constantly recruiting new talent and produce a steady stream of content for owned channels.
⮞In April 2025, COSRX and YesStyle launched their first Euro Supporters influencer program across the United Kingdom, France, Germany, Italy and Spain, recruiting creators to produce content and connect the Korean beauty brand with local consumer communities through ongoing partnerships.
By Fashion Category, Apparel Leads While Jewelry and Accessories Grow Fastest
Apparel leads because clothing is the most visual and frequently purchased fashion category, and creators naturally demonstrate fit, styling and seasonal trends. Fast fashion, streetwear, athleisure and premium labels all use creators to launch collections and drive traffic, and try-on content answers consumer questions about sizing and quality. Resale and rental platforms also work with creators to promote circular fashion. The breadth of price points and styles in apparel gives brands a wide choice of creators and formats.
The category of Jewelry & Accessories is the one that’s experiencing the highest growth because there are close-up videos featuring handbags, watches, eyewear, and jewelry, gifts, and impulse buys on social media platforms. Up-and-coming brands and direct-to-consumer brands are using influencers to promote their products without investing too much money in advertising, while luxury brands are working with selected creators. Footwear, on the other hand, is still an important category because of sneaker culture and drops. Beauty-adjacent fashion categories benefit from crossover audiences that follow style and cosmetics creators alike.
⮞In April 2025, Adidas introduced its Loomhood Collection, drawing inspiration from cultural landmarks in Dubai, Riyadh and Cairo to reinterpret the Samba OG and Handball Spezial footwear styles, illustrating how fashion brands use culturally rooted collaborations to connect products with regional audiences.
By End User, Beauty and Cosmetic Companies Lead While Fashion Brands Grow Fastest
Beauty and cosmetic companies lead spending because tutorials, reviews and swatch content are natural fits for creator formats, and the category has high repeat purchase rates. These companies were early adopters of always-on creator programs, seeding products widely and tracking earned media value, and they have large teams dedicated to creator relations. Their experience with advocacy programs and affiliate models is now being copied by apparel and footwear companies, and fashion marketers often rely on the same agencies and software providers.
Fashion brands are growing fastest as they redirect budgets from print, television and paid search toward creators who can influence both awareness and purchase. Department stores, fast-fashion labels, luxury groups and independent designers are building creator communities and storefront partnerships. Retailers are also adding creator content to product pages and email campaigns to raise conversion. As measurement improves and finance teams accept sales-linked metrics, fashion marketers are expected to treat creator marketing as a core channel rather than an experimental budget line.
⮞In September 2026, Macy’s launched its Fall “Find Us At Macy’s” fashion campaign, featuring six limited-edition capsule collections from established and emerging American designers, strengthening its approach to fashion discovery through designer-led storytelling and exclusive collections.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.50 |
|
Asia Pacific |
China |
38.60 |
|
Europe |
United Kingdom |
27.40 |
|
Latin America |
Brazil |
46.20 |
|
Middle East & Africa |
United Arab Emirates |
31.70 |
North America Fashion Influencer Marketing Market Insights
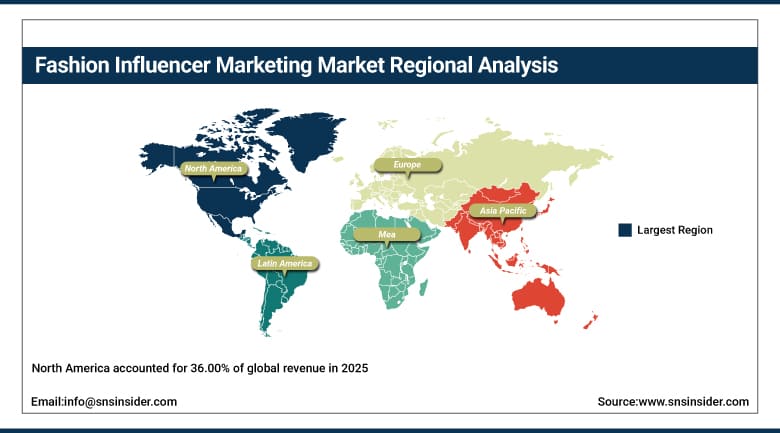
North America accounted for 36.00% of global revenue in 2025, making it the largest regional market for fashion influencer marketing. The United States drives most spending through a deep creator economy, large apparel and beauty brands, mature social commerce platforms and advanced analytics. Canada contributes through growing retail creator programs. Brands run launch campaigns, affiliate programs and loyalty-linked advocacy communities, and platform companies host events and awards that showcase creators and connect them with advertisers.
Regulatory expectations shape practice, as the Federal Trade Commission requires clear disclosure of sponsored content and brands are strengthening contracts and compliance reviews. Budgets are moving away from large celebrity deals toward portfolios of micro and nano creators, and finance teams are demanding sales-linked measurement. Marketplaces, software providers and agencies compete on discovery, payments and reporting, and consolidation among platforms is likely as brands look for integrated tools.
⮞In December 2025, TikTok announced that its U.S. Black Friday and Cyber Monday campaign generated more than USD 500 million in sales over four days, with creator affiliates publishing nearly 10 million shoppable videos, demonstrating the commercial scale of creator-led retail campaigns.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Fashion Influencer Marketing Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 36.40% from 2026-2035. China leads regional demand through live-stream commerce, key opinion leaders and super-app ecosystems, followed by Japan, South Korea, India and Southeast Asian countries. Young, mobile-first consumers discover fashion through short video and social shopping, and creators sell directly through live broadcasts. Regional fast-fashion and cross-border commerce platforms rely heavily on creators to reach buyers.
South Korea's entertainment industry and Japan's street style culture export trends worldwide, giving local creators global reach. India is a rapidly expanding market where regional language creators and affordable fashion brands are building audiences on short-video and messaging platforms. Southeast Asia combines large young populations with fast adoption of social commerce. Brands entering these markets partner with local agencies and creators to adapt content to language, culture and platform preferences, and to comply with differing advertising rules.
⮞In February 2026, TikTok published its “Art and Science of Authenticity” study on creator-driven growth across Asia Pacific, examining how authentic creator storytelling contributes to consumer engagement and commercial outcomes across fashion, beauty and other industries.
Europe Fashion Influencer Marketing Market Insights
Europe combines heritage luxury houses, fast-fashion retailers and a vibrant independent design scene, which together create varied demand for creator partnerships. The United Kingdom, France, Germany and Italy lead spending, and fashion weeks in Paris, Milan, London and Copenhagen draw creators and brands to major events. Luxury groups collaborate selectively with creators to reach younger buyers, while high-street retailers run large affiliate and gifting programs.
Regulation influences the market, with advertising standards authorities and consumer protection rules requiring transparent disclosure and, in some countries, specific rules for influencer conduct. Sustainability is a strong theme, and creators who promote resale, rental and responsible production find receptive audiences. Language diversity requires localized campaigns, which encourages regional agencies and marketplaces. Brands increasingly ask for authenticity checks and audience quality verification before signing contracts.
⮞In March 2025, TikTok Shop announced its expansion into France, Germany and Italy, building on its U.K. operations and extending creator-affiliate commerce, shoppable videos and livestream shopping into three major European consumer markets.
MEA & Latin America Fashion Influencer Marketing Market Insights
In the Middle East and Africa, demand is concentrated in the United Arab Emirates, Saudi Arabia, Qatar and South Africa, where affluent, young and highly social media-active populations support luxury, modest fashion and beauty campaigns. Gulf retailers and malls work with local creators for launches and events, and licensing rules for influencers in some countries shape how campaigns are run. In Africa, a growing creator scene in Nigeria, Kenya and South Africa is building audiences for local designers.
Brazil and Mexico are the top consumers of influencer marketing in Latin America thanks to their sizeable social media users, the existence of a strong beauty culture, and the burgeoning presence of social commerce. Influencers are integral to the promotion of both international and local brands, while affiliate marketing and live selling models are gaining popularity. As digital advertising and e-commerce infrastructure develop, both regions are expected to add steadily to global revenue from a smaller base.
⮞In June 2026, TikTok reported that TikTok Shop's average daily gross merchandise value in Brazil had grown 102-fold during its first year, while the average number of active affiliate creators increased 46-fold, demonstrating the rapid expansion of creator-led social commerce.
Growth Drivers: Social Commerce, Consumer Trust and Short-Form Video
Social commerce is a primary driver, as shopping features, affiliate links, live streams and creator storefronts shorten the path from inspiration to purchase. Fashion is a naturally visual category, and short-form video lets creators demonstrate fit, movement and styling in ways that static advertising cannot. Brands that connect creator content to checkout see direct revenue attribution, which supports larger budgets and encourages finance leaders to treat creators as a performance channel.
Trust from consumers provides additional impetus. The youth, when buying products and services, look to their friends and creators for advice and have little faith in classic advertisements; thus, brands that collaborate with trusted individuals gain quicker recognition. The growing popularity of creator tools, payment solutions, and analytical services makes the programs more affordable, and AI enables brands to select proper creators and predict results. Growth in user-generated content gives brands a steady supply of authentic material for their own channels.
⮞In June 2025, TikTok reported that U.S. TikTok Shop sales had increased 120% year over year during the comparable period, with womenswear among the platform's leading shopping categories, illustrating the growing commercial role of creator-driven product discovery and in-app purchasing.
Restraints: Measurement, Fraud and Regulatory Complexity
Measurements continue to be challenging. Engagement and opinions may not turn into sales; cross-platform measurement is not always reliable; there is a challenge for brands when comparing influencers with varying levels of popularity. Fictitious followers, false engagement, and hidden sponsorships affect the trust and budget waste. It becomes necessary to have verification mechanisms and audits, which increase costs, along with the challenge of proving the return on investment based on different measurement standards.
Regulatory risks and platform dependency pose risks. Regulations are different across nations, there are enforcement risks, and there is also the possibility that an error could hurt a brand’s reputation. Algorithmic shifts, ownership issues, or even social media bans will create difficulties for a marketing campaign and access to its target audience. Creator fatigue and high fees for the best creators are other risks.
Opportunities: Artificial Intelligence, Loyalty Integration and Emerging Markets
Artificial intelligence offers significant opportunity in creator discovery, brief generation, content analysis and performance prediction. Tools that match brands with creators based on audience overlap, style and past results can improve returns, and automation reduces the manual work of managing large networks. Integration of creator programs with loyalty schemes, as retailers connect millions of members to advocacy communities, gives brands first-party data and repeat engagement.
Emerging markets offer further opportunity, as rising smartphone use, social commerce and local fashion brands expand the creator base in Asia, Latin America, the Middle East and Africa. The ideas of resale, renting, and sustainable fashion can be used for theme-based content. The use of virtual try-ons, augmented reality, and live shopping experiences will give you additional options. Finally, your campaigns can go beyond your country because cross-border marketing is now possible.
⮞In October 2025, Adobe detailed how Tapestry, the parent company of Kate Spade New York and Coach, was exploring Adobe Firefly Custom Models to accelerate brand-specific creative development, highlighting an opportunity to integrate AI-enabled content production into fashion marketing workflows.
Recent Developments:
-
2025: Gap Inc. introduced a creator affiliate and advocacy hub across its Old Navy, Gap, Banana Republic and Athleta brands. The program accepts creators with at least 1,000 followers and rewards them through commission, product access and gifting. The hub reflects the company's move toward performance-based creator marketing across its portfolio.
-
2026: SHEIN launched its Fall/Winter 2026 Trend Campaign built around six key trends and five top digital creators. Creators offered their own interpretations of themes such as Dark Romance, Folk Revival and Power Dressing, and shared behind-the-scenes content so communities could follow the process.
-
2026: CreatorIQ introduced Q, an agentic AI system for creator marketing, alongside MeasureIQ analytics and enhanced SafeIQ brand-suitability tools. The products support campaign workflows, creator performance measurement, and risk monitoring.
Fashion Influencer Marketing Market Key Players are:
-
LTK
-
CreatorIQ
-
Upfluence
-
Grin
-
IZEA Worldwide, Inc.
-
Klear
-
Launchmetrics
-
Mavrck
-
Influencity
-
Modash
-
Pearpop
-
ShopMy
-
Billion Dollar Boy
-
Takumi
-
The Influencer Marketing Factory
-
Later
-
Tagger Media
-
Collabstr
Fashion Influencer Marketing Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.00 Billion |
| Market Size by 2035 | USD 150.11 Billion |
| CAGR | CAGR of 32.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Influencer Type (Nano-Influencers, Micro-Influencers, Macro-Influencers, Mega-Influencers) • By Platform (Instagram, TikTok, YouTube, Others) • By Campaign Type (Sponsored Content, Brand Ambassadorships, Affiliate Marketing, Others) • By Fashion Category (Apparel, Footwear, Jewelry and Accessories, Others) • By End User (Fashion Brands, Beauty and Cosmetic Companies, Retailers, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LTK, CreatorIQ, Upfluence, Grin, AspireIQ, IZEA Worldwide, Inc., Klear, Launchmetrics, Mavrck, Influencity, Modash, Pearpop, ShopMy, Billion Dollar Boy, Viral Nation, Takumi, The Influencer Marketing Factory, Later, Tagger Media, Collabstr |

Frequently Asked Questions
Key players include LTK, CreatorIQ, Upfluence, Grin, AspireIQ, IZEA Worldwide, Inc., and Collabstr, among others.
Key opportunities include artificial intelligence for creator discovery and measurement, integration of creator programs with retail loyalty schemes, live and video commerce, and expansion in Asia, Latin America and the Middle East.
The major growth factor is the rise of social commerce and short-form video, combined with the trust younger consumers place in creators over traditional advertising.
By Platform, the Instagram segment dominated the market with approximately 49.50% share in 2025, owing to its visual format, shopping features and established creator ecosystem.
North America dominated the market with a share of 36.00% in 2025, supported by a deep creator economy, mature social commerce platforms and large apparel and beauty brands in the United States.
