
Fast Moving Consumer Goods (FMCG) Market Report Scope & Overview:
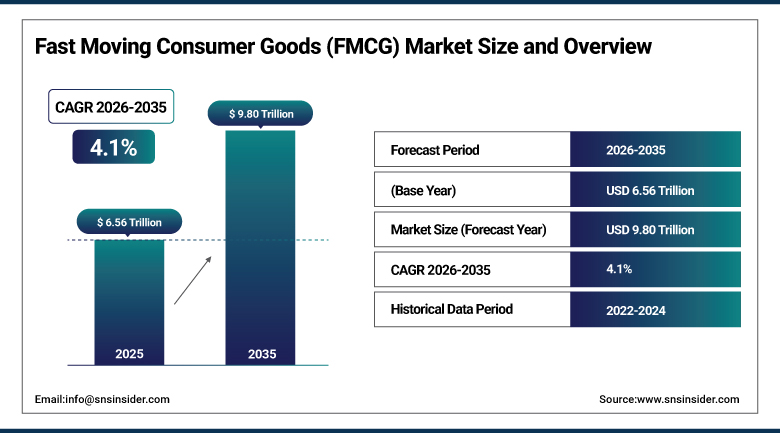
The Fast Moving Consumer Goods (FMCG) Market was valued at USD 6.56 Trillion in 2025 and is expected to reach USD 9.80 Trillion by 2035, growing at a CAGR of 4.1% from 2026–2035.
The Fast Moving Consumer Goods (FMCG) Market includes the category of packaged foods and beverages, personal care, household care, and over-the-counter health products. These products are sold rapidly, at low prices, and in large volumes. The demand remains constant since these are products that need to be purchased again and again as people use them daily. They are driven by income growth in developing nations, urbanization, premium, and health products, as well as e-grocery.
⮞On March 31, 2026, Unilever entered into an agreement to sell its food business line, which includes brands such as Knorr and Hellmann’s, to McCormick for a total consideration of USD 44.80 billion. In this transaction, Unilever is set to receive USD 15.70 billion in cash and USD 29.10 billion in stock of McCormick. The sale is still pending shareholder and regulatory approvals and is set to be completed in mid-2027.
To Get more information Fast Moving Consumer Goods (FMCG) Market - Request Free Sample Report
Fast Moving Consumer Goods (FMCG) Market Trends
-
Premiumization of food, beverage and personal care products as incomes rise
-
Shift toward health, protein-rich and functional products
-
Growth of online grocery, quick commerce and direct-to-consumer brands
-
Portfolio reshaping through large acquisitions, demergers and brand sales
-
Move to recyclable, lightweight and refillable packaging
-
Expansion of retailer private labels and value-focused ranges
U.S. Fast Moving Consumer Goods (FMCG) Market Outlook
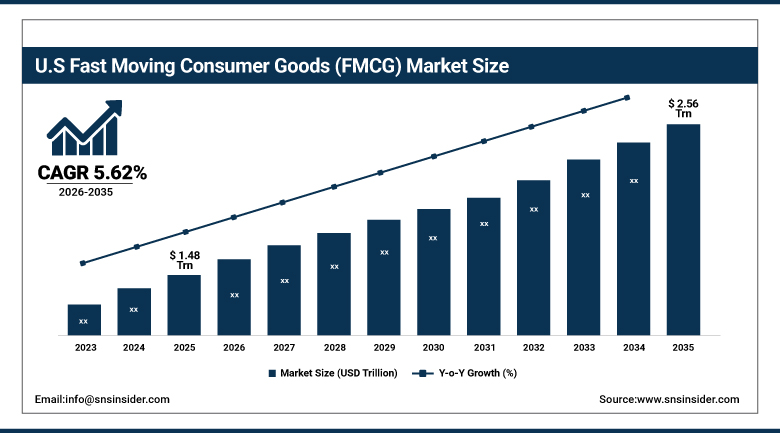
The U.S. Fast Moving Consumer Goods (FMCG) Market was valued at USD 1.48 Trillion in 2025 and is expected to reach USD 2.56 Trillion by 2035, growing at a CAGR of 5.62% from 2026-2035.
The United States FMCG Market is the largest in the country among all other markets, backed up by high household expenditures, efficient distribution channels, strong brands, and high online groceries presence. Large-scale producers face competition from retailer's private labels that benefit when consumers' household budgets are constrained. The growth is restrained by high raw material and labor prices, price sensitivity, and increasing ingredient and labeling regulations, whereas protein, snacks, and wellness products drive demand.
⮞On December 11, 2025, Mars completed its acquisition of Kellanova, the maker of Pringles and other snack brands, after final regulatory approvals. The purchase was financed with USD 26.00 billion of senior notes in a public offering, USD 1.00 billion equivalent in a private placement and USD 4.00 billion of delayed draw term loans, giving Mars a larger position in savory snacks.
Fast Moving Consumer Goods (FMCG) Market Segment Analysis
-
By Product Type, food and beverages segment dominated the Fast Moving Consumer Goods (FMCG) Market in 2025 with an estimated 46.00% share; personal care segment is the fastest-growing segment, with an estimated CAGR of 6.40% during 2026–2035.
-
By Distribution Channel, supermarkets and hypermarkets segment dominated the Fast Moving Consumer Goods (FMCG) Market in 2025 with an estimated 41.00% share; online retail segment is the fastest-growing segment, with an estimated CAGR of 11.50% during 2026–2035.
-
By Price Tier, mass segment dominated the Fast Moving Consumer Goods (FMCG) Market in 2025 with an estimated 62.00% share; premium segment is the fastest-growing segment, with an estimated CAGR of 7.20% during 2026–2035.
-
By Packaging Type, plastic segment dominated the Fast Moving Consumer Goods (FMCG) Market in 2025 with an estimated 44.00% share; paper and paperboard segment is the fastest-growing segment, with an estimated CAGR of 7.00% during 2026–2035.
By Product Type, Food and Beverages Dominates Global FMCG Market; Personal Care to Register Fastest Growth.
Food and beverages dominate the Fast Moving Consumer Goods (FMCG) Market because packaged staples, dairy, snacks, confectionery, soft drinks and ready meals are bought by almost every household on a weekly basis. Large manufacturers sell across many price points, and constant launches in flavors, sizes and formats keep shelves active. Rising demand for convenience and protein-rich foods and the expansion of modern retail in emerging markets add steady volume to this segment. Strong brand loyalty and quick turnover also mean that producers can plan output with confidence and adjust recipes, pack sizes and prices in short cycles.
Personal care products are expected to be the fastest growing category as consumers are spending more on skin care, hair care, oral care and grooming, particularly in the Asia Pacific and Latin American regions. Social media marketing, influencer brands, and online selling ensure that the new product finds its way into the hands of the consumer in a shorter period of time. Premium formulations, use of natural ingredients, and men's grooming lines increase the average price, and big firms are acquiring fast-growing brands for diversification in beauty and wellness.
By Distribution Channel, Supermarkets and Hypermarkets Dominates Global FMCG Market; Online Retail to Register Fastest Growth.
Supermarkets and hypermarkets are the most prevalent formats in the FMCG market of the globe due to the diversity of their offering, promotions and provision of shopping in one place. Manufacturers develop promotions with large chains and buy shelf space, which is suitable for family shopping visits. In developed countries, supermarkets and hypermarkets have private label products which compete against national brands. Chains also benefit from data on loyalty card purchases in order to tailor the offering in accordance with shopping habits in particular stores.
Online retail is projected to register the fastest growth as grocery apps, marketplaces and quick commerce services deliver everyday products within minutes in large cities. Subscription orders, targeted offers and easy reordering raise repeat purchases, and brands use online data to adjust assortments quickly. Lower delivery costs, wider mobile payment use and investment by retailers and platforms in local warehouses are drawing new shoppers in both mature and emerging economies. Retailers are linking stores with online ordering, so shoppers can pick up goods the same day, which supports further growth of this channel.
By Price Tier, Mass Dominates Global FMCG Market; Premium to Register Fastest Growth.
The mass tier dominates the Fast Moving Consumer Goods (FMCG) Market because most buyers choose affordable, trusted products for daily needs, and large populations in Asia Pacific, Latin America and Africa have limited budgets. Small pack sizes, sachets and value multipacks make products accessible, and wide distribution through local stores supports volume. Manufacturers defend this tier with cost control, local production and frequent price-pack changes. Retailers also place mass brands at eye level, and heavy advertising keeps them familiar to shoppers who compare prices carefully.
The premium range is expected to show the fastest growth because of increased purchasing power amongst high-income groups who will look at premium ingredients, health benefits, sustainable aspects, and unique designs. The craft, organic, plant-based, and functional product ranges come at a higher price point, and marketers use limited editions and loyalty programs to keep customers loyal. The growing middle class in developing countries expands the market base for consumers who can afford to pay more for the better quality experience. Premium brands are also being launched under already established brands.
By Packaging Type, Plastic Dominates Global FMCG Market; Paper and Paperboard to Register Fastest Growth.
Plastic dominates the Fast Moving Consumer Goods (FMCG) Market because bottles, pouches, tubs and films are light, low in cost, protect freshness and suit high-speed filling lines. They are used across beverages, personal care, household cleaners and snacks, and flexible formats reduce shipping weight. Manufacturers are increasing recycled content and redesigning packs for recycling, which keeps plastic in use even as rules tighten. Lower breakage in transport and long shelf life also reduce waste, which matters for companies shipping goods across large distances.
Paper and paperboard are projected to register the fastest growth as brands respond to extended producer responsibility laws, retailer targets and consumer concern about waste. Cartons, paper-based pouches and fiber bottles are replacing mixed plastics in food, beverage and household products. Improvements in barrier coatings, printing and recyclability allow wider use, and companies promote lower-carbon packaging as part of their sustainability goals. Packaging suppliers are investing in new coating lines and fiber molding capacity, which should improve supply and lower unit costs over the forecast period.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
38.00 |
|
North America |
United States |
82.00 |
|
Europe |
Germany |
21.00 |
|
Latin America |
Brazil |
46.00 |
|
Middle East & Africa |
Saudi Arabia |
24.00 |
North America Global FMCG Market Insights
North America is the second-largest region, with a share of 27.50% in 2025, and is projected to grow at a CAGR of 4.30% during 2026-2035. The United States accounts for about 82.00% of regional demand, with Canada and Mexico adding volume. PepsiCo, Coca-Cola, Procter & Gamble, Mondelez, Kraft Heinz, Mars, Colgate-Palmolive, Kimberly-Clark and General Mills hold strong positions across grocery, drug and club store channels. Retail is concentrated among a few large chains, warehouse clubs and online platforms, which gives manufacturers wide reach but also strong negotiating pressure.
Categorization, branding, marketing budget, and logistics are mature in this region. There is an increase in demand for proteins, health-related snacks, and products. The online grocery channel remains a fast-growing one. Factors such as inflation, growth in private label business, labor and commodity costs, and regulation of ingredients hinder growth in the sector. Companies have to concentrate on price, innovation, and savings to sustain their profit margins. Automation, regional distribution centers, and data-driven pricing ensure that companies maintain their supply while adapting to consumer changes in demand. Consumers' demand for clean labels and proteins is influencing new product introductions.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Global FMCG Market Insights
Europe is the third-largest region, with a share of 21.50% in 2025, and is growing at a CAGR of 3.60% during 2026-2035. Germany, the United Kingdom, France, Italy and Spain lead regional demand. Nestlé, Unilever, Danone, Henkel, Beiersdorf, Reckitt, L'Oréal and large grocery chains with strong private labels shape the competitive field. Retail is led by discount chains and large supermarkets, and many of them sell strong private label ranges next to national brands, which shapes pricing across categories. Strong demand for dairy, chocolate, bakery and household cleaning products keeps volumes resilient despite cautious spending.
Consumers favor sustainable, organic and health-focused products, and regulation on packaging, labeling and emissions is strict. Portfolio changes among large groups are frequent as companies sell slower brands and invest in faster ones. Slow population growth, high costs, discount retailer competition and cautious spending limit volume, though premium and plant-based ranges support value growth. European producers also invest in lower-carbon plants, recyclable packs and reformulated recipes to meet rules and retailer targets. Aging populations also support demand for nutrition and healthcare-related packaged products across the region.
⮞In December 2025, Unilever completed the demerger of its ice cream business, now The Magnum Ice Cream Company, whose brands include Magnum, Ben & Jerry's, Wall's and Cornetto. The new company lists its shares in London, Amsterdam and New York, and the move leaves Unilever focused on health, wellness and personal care brands.
Asia Pacific Global FMCG Market Insights
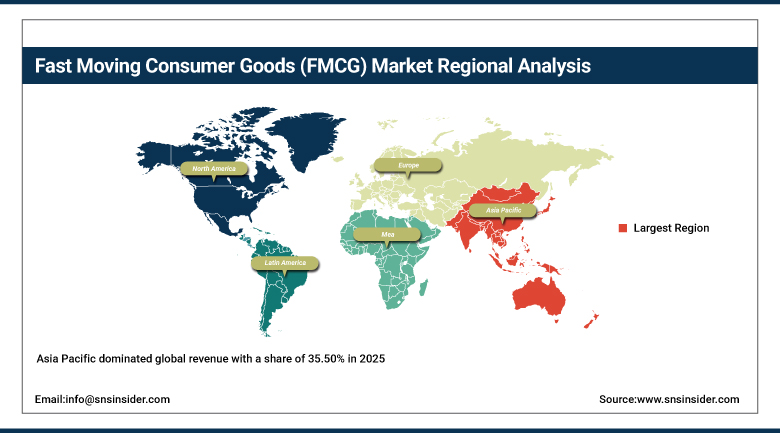
Asia Pacific dominated global revenue with a share of 35.50% in 2025 and is projected to be the fastest-growing region, at a CAGR of 6.30% during 2026-2035. China accounts for about 38.00% of regional demand, followed by India, Japan, Indonesia and South Korea. Nestlé, Unilever, Procter & Gamble, Hindustan Unilever, ITC, Tata Consumer Products, Reliance Consumer Products, Danone and local manufacturers serve a large and young consumer base. Online platforms and neighborhood stores are both growing, and companies rely on local distributors to reach villages and small towns across the region.
Growing disposable incomes, increasing urbanization, development of modern retail formats and the boom in quick commerce are favorable for leadership. Corporations are setting up local manufacturing facilities and acquiring regional brands to access small cities. Price sensitivity, high input costs, poor logistics infrastructure, and competitive threat of local brands constrain growth, but the sheer size of the population drives demand in food, beverages, and personal care segments. The government’s encouragement towards food processing, higher use of smartphones, and exports of packaged products from multiple countries are other drivers of regional sales.
⮞On February 10, 2026, Reliance Consumer Products, the FMCG arm of Reliance Industries, acquired Southern Health Foods, the Tamil Nadu maker of the Manna health foods brand. Separately, on June 22, 2026, Danone agreed to buy Australia's MADE Group, maker of Cocobella coconut water and Rokeby protein smoothies, and to acquire the 49% of its Australian dairy venture held by Saputo.
MEA & Latin America Global FMCG Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Chile, with regional demand growing at about 5.20% annually. Large urban populations, growing modern retail and strong demand for dairy, beverages and personal care support sales, while currency swings and inflation add risk. Nestlé, Unilever, Coca-Cola, PepsiCo, Danone and local groups invest heavily in local plants. Informal and neighborhood stores remain important in many cities, and companies use small packs and local distributors to reach lower-income households. Brazil and Mexico together account for most regional sales, and young populations support steady growth in packaged food, beverages and hygiene products.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, South Africa, Egypt and Nigeria are key drivers of consumption with annual growth of about 5.80%. Growing youth populations, increasing disposable income in cities and expansion in the number of supermarkets and convenience stores drives consumption in packaged foods and household products, but low income and dependency on imports are constraining the growth rate. No confirmed case study of any company could be found for Middle East and Africa.
⮞On September 3, 2026, Nestlé announced an investment of about USD 392.73 million, in its nutrition and health division in Brazil through 2028, including a BRL 600.00 million infant formula plant in Ituiutaba, Minas Gerais, with construction starting in 2027. In October 2026, Nestlé also announced a further USD 1.00 billion for Mexico for 2028 to 2030.
Market Dynamics
Growth Drivers: Rising Incomes, Urbanization and Premiumization
Rising incomes and urban living in Asia Pacific, Latin America and Africa bring more households into branded, packaged products, and modern retail makes them easier to buy. Frequent repeat purchases give the market steady volume even when the wider economy slows. Demographic growth in large markets adds new buyers every year.
Consumers are also trading up to health, protein and personal care products, which lifts average prices. Online grocery and quick commerce widen reach and let brands test products faster. Wider access to credit and digital payments further supports everyday spending.
Restraints: Input Costs, Private Labels and Packaging Rules
Commodity, energy, and freight costs eat into profit margins, while price hikes need to be weighed against volume losses from price-sensitive consumers. Foreign currency fluctuations in developing countries add another layer of difficulty to importing raw materials.
Private label products gain popularity during economically tough times, and extended producer responsibility legislation increases packaging costs for smaller producers.
Opportunities: Emerging Markets, Health Products and Portfolio Reshaping
Emerging markets present significant opportunities for large untapped consumer groups, and production close to home, along with smaller pack sizes, can be used to get branded products to these customers. Health and protein-based products are high-value categories.
Acquisition of brands and selling of brands enables companies to shift investments to more rapidly growing categories, whereas digital data is used to personalize assortment, promotion, and price strategy across channels.
Recent Developments:
-
In October 2026, Nestlé announced a further USD 1.00 billion investment in Mexico for 2028 to 2030, to upgrade facilities and add production capacity.
-
In June 2026, Danone agreed to acquire Australia's MADE Group and Saputo's 49% stake in their Australian dairy venture.
-
In March 2026, Unilever agreed to sell its food division to McCormick in a deal valued at USD 44.80 billion.
Fast Moving Consumer Goods (FMCG) Market Key Players are
-
Nestlé S.A.
-
Unilever PLC
-
PepsiCo, Inc.
-
The Coca-Cola Company
-
The Procter & Gamble Company
-
Danone S.A.
-
Mars, Incorporated
-
Mondelez International, Inc.
-
The Kraft Heinz Company
-
Colgate-Palmolive Company
-
Kimberly-Clark Corporation
-
L'Oréal S.A.
-
Henkel AG & Co. KGaA
-
Reckitt Benckiser Group plc
-
Beiersdorf AG
-
General Mills, Inc.
-
ITC Limited
-
Hindustan Unilever Limited
-
Tata Consumer Products Limited
-
Reliance Consumer Products Limited
Fast Moving Consumer Goods (FMCG) Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.56 Billion |
| Market Size by 2035 | USD 9.80 Billion |
| CAGR | CAGR of 4.1% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Food and Beverages, Personal Care, Household Care, Healthcare and Others) • By Distribution Channel (Supermarkets and Hypermarkets, Convenience and Local Stores, Online Retail, Others) • By Price Tier (Mass, Mid-Range, Premium) • By Packaging Type (Plastic, Paper and Paperboard, Glass and Metal, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Nestlé S.A., Unilever PLC, PepsiCo, Inc., The Coca-Cola Company, The Procter & Gamble Company, Danone S.A., Mars, Incorporated, Mondelez International, Inc., The Kraft Heinz Company, Colgate-Palmolive Company, Kimberly-Clark Corporation, L'Oréal S.A., Henkel AG & Co. KGaA, Reckitt Benckiser Group plc, Beiersdorf AG, General Mills, Inc., ITC Limited, Hindustan Unilever Limited, Tata Consumer Products Limited, Reliance Consumer Products Limited |

Frequently Asked Questions
Key players include Nestlé S.A., Unilever PLC, PepsiCo, Inc., The Coca-Cola Company, The Procter & Gamble Company, Danone S.A., Mars, Incorporated and Mondelez International, Inc.
Key opportunities include emerging market growth, health and functional products, and portfolio reshaping through acquisitions and brand sales.
The major growth factor is rising incomes and urbanization, which bring more households into branded, packaged products.
By Product Type, the Food and Beverages segment dominated the market in 2025 with an estimated 46.00% share, supported by weekly household purchases of staples, snacks and drinks.
Asia Pacific dominated the market with a share of 35.50% in 2025, driven by large populations, rising incomes and expanding modern retail.
