
Connected Aircraft Market Report Scope & Overview:
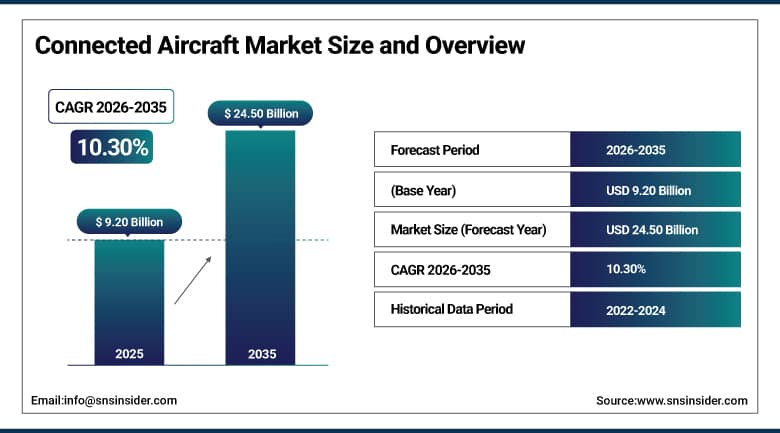
The Connected Aircraft Market was valued at USD 9.20 Billion in 2025 and is expected to reach USD 24.50 Billion by 2035, growing at a CAGR of 10.30% from 2026–2035.
A connected aircraft carries real-time data links, satellite antennas, onboard routers, and cabin Wi-Fi systems, that keep it in continuous contact with the ground, other aircraft, and the internet throughout a flight, turning what used to be a communications black hole above 10,000 feet into just another connected node. That connectivity now does far more than stream inflight movies: it feeds predictive maintenance systems real-time engine data, gives airlines live weather routing updates, and satisfies a regulatory mandate requiring real-time aircraft position tracking under ICAO's Global Aeronautical Distress and Safety System rules. Passenger expectations for gate-to-gate broadband have converged with genuine operational and safety requirements to make connectivity hardware something airlines now specify at the fleet level rather than retrofitting aircraft by aircraft.
Viasat's broadband aviation business surpassed 6,000 commercial aircraft and business jets in service by the end of its fiscal year 2025, with its newly integrated ViaSat-3 satellite alone serving well over 50,000 commercial flights across more than 2,000 different aircraft. Passenger satisfaction scores on that satellite reportedly matched Starlink's low-Earth-orbit service on comparable routes, a genuinely notable result given how much attention Starlink's entry into in-flight Wi-Fi has drawn, and a reminder that the newer, buzzier LEO satellite approach hasn't simply made older geostationary technology obsolete overnight.
To Get More Information On Connected Aircraft Market - Request Free Sample Report
Connected Aircraft Market Trends
-
Multi-orbit satellite strategies continue gaining traction, as airlines and connectivity providers combine geostationary and low-Earth-orbit constellations to balance coverage, latency, and capacity across different route types.
-
Managed connectivity models bundling satellite capacity, hardware, and airline digital passenger experience software into per-aircraft monthly fees continue displacing standalone equipment sales across the commercial aviation segment.
-
Regulatory mandates for real-time aircraft position tracking continue reinforcing baseline connectivity requirements across commercial fleets, independent of passenger Wi-Fi demand or airline discretionary technology investment decisions.
-
Direct-to-device and shared-infrastructure satellite approaches continue emerging as an alternative to single-operator constellations, with industry groups pursuing collaborative frameworks to expand aviation connectivity access.
-
Predictive maintenance and analytics platforms continue expanding as a genuine revenue category beyond passenger connectivity, using real-time aircraft data streams to reduce unscheduled maintenance events and flight delays.
U.S. Connected Aircraft Market Outlook
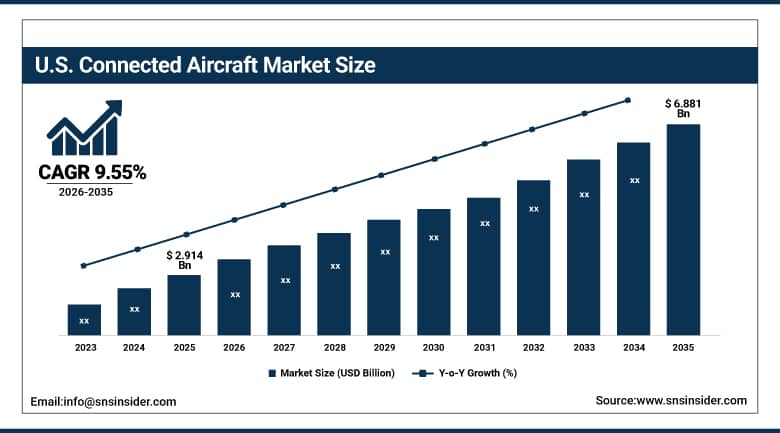
The U.S. Connected Aircraft Market was valued at approximately USD 2.914 Billion in 2025 and is expected to reach approximately USD 6.881 Billion by 2035, growing at a CAGR of approximately 9.55%.
Demand in the United States is anchored by early adoption among commercial carriers and extensive business jet penetration, giving domestic connectivity providers a deep, technologically sophisticated customer base to serve. A concentration of the world's leading satellite connectivity, avionics, and cabin systems manufacturers continues anchoring both innovation and production capacity domestically, with several providers running end-to-end networks spanning satellite fleets, ground infrastructure, and onboard terminals. Growing competitive intensity between geostationary satellite incumbents and newer low-Earth-orbit entrants continues reshaping how connectivity contracts get negotiated and priced across both commercial and business aviation segments.
Viasat, headquartered in Carlsbad, California, launched an incentive program in October 2025 offering business aviation operators up to $140,000 per aircraft to upgrade from Ku-band connectivity to its newer JetXP in-flight service, distributed through partners including Collins Aerospace, Gogo, and Honeywell. That kind of six-figure-per-aircraft incentive reveals just how much competitive pressure connectivity providers face to keep business jet operators, a customer base with far more discretionary switching power than commercial airlines locked into fleet-wide, years-long equipment contracts, from defecting to a rival satellite network.
Connected Aircraft Market Segment Analysis
-
By Offering, the Services segment dominated the Connected Aircraft Market with approximately 50.92% share in 2025, and is also the fastest growing with a CAGR of approximately 12.18%.
-
By Connectivity Type, the In-Flight Connectivity segment dominated the Connected Aircraft Market with approximately 61.85% share in 2025, while the Air-to-Ground Solutions segment is the fastest growing with a CAGR of approximately 13.55%.
-
By Connectivity Technology, the Satellite Ku-Band segment dominated the Connected Aircraft Market with approximately 49.20% share in 2025, while the Satellite Ka-Band segment is the fastest growing with a CAGR of approximately 12.88%.
-
By Application, the Commercial Aviation segment dominated the Connected Aircraft Market with approximately 69.55% share in 2025, while the General Aviation segment is the fastest growing with a CAGR of approximately 11.95%.
By Offering, services dominates and grows fastest
Services held the larger share of the offering segment in 2025, reflecting the aviation industry's decisive shift toward managed connectivity models that bundle satellite capacity, hardware maintenance, and airline digital passenger experience software into per-aircraft monthly fees. That subscription-style commercial structure lets airlines avoid large upfront capital investment while giving connectivity providers a more predictable, recurring revenue base than one-time equipment sales alone could deliver, keeping services the dominant offering category across the broader market.
Services are also the fastest-growing offering category, an unusual case where the already-dominant segment continues gaining share rather than ceding ground to hardware sales. Rising airline preference for fully managed connectivity contracts, combined with growing demand for predictive analytics and fleet management services layered on top of basic connectivity, continues reinforcing this above-average growth trajectory relative to standalone antenna and router hardware sales.
By Connectivity Type, in-flight connectivity dominates, air-to-ground grows fastest
In-flight connectivity held the majority share of the connectivity-type segment in 2025, serving as the primary passenger-facing and operational data link for the overwhelming majority of commercial and business aircraft currently in service. Its ability to provide continuous coverage over oceans and remote areas where ground-based alternatives simply can't reach keeps in-flight connectivity the dominant technology approach across nearly every long-haul and international route category.
Air-to-ground solutions are growing fastest as rising demand for cost-efficient connectivity on shorter domestic and regional routes, where ground-based cellular towers can provide reliable coverage without the cost of satellite capacity, continues expanding this technology's addressable market. Advancing 4G and emerging 5G ground network infrastructure is reinforcing this above-average growth trajectory relative to the broader, satellite-dominated connectivity-type mix.
By Connectivity Technology, satellite Ku-band dominates, satellite Ka-band grows fastest
Satellite Ku-band held the largest share of the connectivity-technology segment in 2025, valued for its established infrastructure, broad geographic coverage, and proven track record across commercial aviation's largest connectivity providers. That combination of maturity and reliability keeps Ku-band the technology of record for the majority of in-service aircraft connectivity systems, even as newer, higher-capacity technologies continue gaining ground elsewhere in the market.
Satellite Ka-band is growing fastest as its higher bandwidth capacity and improved data throughput continue winning favor for applications demanding faster, more reliable passenger broadband and operational data transmission. Multiple major providers integrating new Ka-band satellite capacity into their global networks continue reinforcing this above-average growth trajectory relative to the broader, Ku-band-dominated technology mix.
By Application, commercial aviation dominates, general aviation grows fastest
Commercial aviation accounted for the large majority of the application segment in 2025, reflecting the sheer scale of the global commercial airline fleet and the mandatory connectivity requirements increasingly built into new aircraft delivery specifications. That combination of fleet scale and regulatory-driven baseline connectivity requirements keeps commercial aviation the dominant application category by a wide margin over military and general aviation combined.
General aviation is growing fastest as business jet operators and smaller aircraft owners increasingly demand the same connectivity capability that commercial airline passengers have come to expect, extending connected aircraft technology well beyond its traditional commercial airline base. Rising business jet fleet expansion and growing operator willingness to invest in premium connectivity upgrades continue reinforcing this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.60% |
|
Europe |
France |
25.70% |
|
Asia Pacific |
China |
39.40% |
|
Latin America |
Brazil |
35.90% |
|
Middle East & Africa |
UAE |
31.20% |
North America Connected Aircraft Market Insights
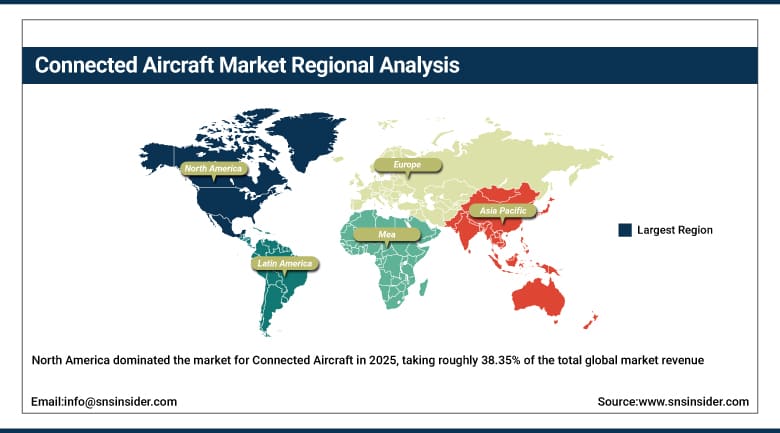
North America dominated the market for Connected Aircraft in 2025, taking roughly 38.35% of the total global market revenue, due to an early adaptation of the technology by commercial airlines and a large number of business jets in the region, owing to a well-established aviation industry. The combination of the two, along with the region being home to the best satellite companies and avionics manufacturers, has helped the region maintain leadership in both connectivity deployment and innovation in the region.
While Canada plays an important role via its commercial and business aviation market, the Mexican market is still in its developmental stages, relying heavily on connectivity technology and services from the northern country. The linkages of technology and service providers make a majority of North American demand interconnected, with connectivity in North America largely coming from providers based in the United States.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Connected Aircraft Market Insights
Asia Pacific is projected to grow at the highest CAGR during the forecast period, attributed to the improving economy of emerging countries such as India and China, where rising demand for new aircraft continues fueling connected aircraft technology adoption. Rapidly expanding regional airline fleets and growing passenger expectations for onboard connectivity across the region's largest and fastest-growing aviation markets continue reinforcing this accelerating growth trajectory.
China's expanding domestic airline fleet and growing aerospace manufacturing ambitions give the region substantial baseline demand, while India's rapidly growing aviation sector is drawing significant new investment in connectivity infrastructure. Japan and South Korea represent more mature, technology-forward markets with established connectivity adoption, while Southeast Asian markets continue following a similar fleet-expansion-driven growth trajectory.
Europe Connected Aircraft Market Insights
Europe represents a moderately growing connected aircraft market, supported by increasing passenger air traffic and the presence of prominent key players and original equipment manufacturers who play a major role in regional market growth. France anchors regional demand, home to Airbus and a deep base of aerospace suppliers investing in next-generation connectivity and avionics technology.
The United Kingdom and Germany contribute significant commercial and business aviation activity as well, with both countries hosting major airlines and aerospace component suppliers. Continued European investment in fleet modernization and regulatory compliance with real-time tracking mandates continues reinforcing steady regional demand growth.
MEA & Latin America Connected Aircraft Market Insights
The Middle East and Africa host a strategically significant share of the connected aircraft market, with the UAE driving demand through its position as a major global aviation hub and growing premium airline fleet requiring advanced passenger connectivity. Growth elsewhere in the region remains tied closely to the pace of broader aviation infrastructure development.
Latin America is a growing market led by Brazil, where expanding commercial aviation and a growing regional aerospace manufacturing base continue driving connected aircraft technology adoption. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing commercial aviation sectors.
Market Dynamics
Growth Drivers: Passenger connectivity expectations and regulatory tracking mandates fueling adoption
Rising passenger expectations for gate-to-gate broadband are one of the clearest forces behind rising connected aircraft demand, as travelers increasingly treat reliable inflight Wi-Fi as a baseline expectation rather than a premium amenity across both commercial and business aviation. That shift in passenger expectations has pushed airlines to treat connectivity hardware as a competitive necessity rather than an optional upgrade, particularly on long-haul international routes where connectivity gaps are most noticeable.
Mandated real-time tracking under ICAO's Global Aeronautical Distress and Safety System rule adds a second major driver, requiring commercial aircraft to maintain continuous position reporting regardless of passenger connectivity demand. Multi-orbit satellite deployments that cut latency and bandwidth cost continue reinforcing this demand base, making connectivity technology more accessible and cost-effective across a broader range of aircraft types and route profiles.
Restraints: High retrofit costs and installation complexity limiting adoption speed
The high costs involved in retrofits are a true constraint as retrofitting satellites, antennas, and other equipment onto an aircraft involves costly processes that airlines have to undertake knowing that the benefits they may accrue through passenger connectivity fees are not assured at all. The process is costly as well as time-consuming in terms of taking an aircraft out of operation and can affect the adoption even by airlines that understand the value of connectivity.
Technical complexities involved in installation are yet another constraint, especially in case of old generation aircrafts where the process of installing satellite systems is more complex than in case of new generation planes that come equipped with connectivity right from the manufacture.
Opportunities: Predictive analytics and multi-orbit hybrid connectivity opening new growth avenues
Predictive analytics and advanced passenger engagement platforms offer connectivity providers a genuine path to capturing higher-margin recurring revenue beyond basic passenger Wi-Fi, using real-time aircraft data streams to reduce unscheduled maintenance events and improve operational efficiency. Companies that build strong analytics and data platform capability alongside their core connectivity infrastructure are positioned to capture disproportionate growth as airlines increasingly value operational insight over connectivity alone.
Hybrid multi-orbit connectivity represents a second significant opportunity, as combining geostationary and low-Earth-orbit satellite capacity lets providers balance coverage, latency, and capacity more effectively than any single-orbit approach can achieve alone. Companies that build genuine multi-orbit integration capability are positioned to capture premium pricing from airlines seeking the most reliable, highest-performance connectivity available across their entire route network.
Recent Developments:
-
September 2025: Panasonic Avionics and Intellian Technologies began developing a LEO-only aviation antenna compatible with Eutelsat's OneWeb constellation, offering speeds up to 195 Mbps and under 100 milliseconds of latency.
-
December 2025: Gogo made a strategic investment in Farcast to fund development of aviation user terminals.
-
2025: Starlink's in-flight connectivity service went live on passenger flights in the United States, with test data showing high service quality.
-
2025: Viasat continued integrating multiple third-party satellite constellations into its global broadband network following its acquisition of Inmarsat, expanding capacity in high-demand geographic locations.
Connected Aircraft Market Key Players
-
Honeywell Aerospace (Honeywell International Inc.)
-
Collins Aerospace (RTX Corporation)
-
Thales Group
-
Viasat Inc.
-
Panasonic Avionics Corporation
-
Gogo Inc.
-
Anuvu
-
Cobham Limited
-
BAE Systems plc
-
Zodiac Aerospace (Safran)
-
Kontron AG
-
Digecor
-
SITAONAIR
-
Astronics Corporation
-
L3Harris Technologies, Inc.
-
Iridium Communications Inc.
-
Garmin Ltd.
-
The Boeing Company
-
Airbus SE
-
Sabre Corporation
Connected Aircraft Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.20 Billion |
| Market Size by 2035 | USD 24.50 Billion |
| CAGR | CAGR of 10.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Offering (Solutions, Services) • by Connectivity Type (In-Flight Connectivity, Air-to-Ground Solutions) • by Connectivity Technology (Satellite Ku-Band, Satellite Ka-Band, L-Band, Air-to-Ground (4G/5G)) • by Application (Commercial Aviation, Military Aviation, General Aviation) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell Aerospace (Honeywell International Inc.), Collins Aerospace (RTX Corporation), Thales Group, Viasat Inc., Panasonic Avionics Corporation, Gogo Inc., Anuvu, Cobham Limited, BAE Systems plc, Zodiac Aerospace (Safran), Kontron AG, Digecor, SITAONAIR, Astronics Corporation, L3Harris Technologies, Inc., Iridium Communications Inc., Garmin Ltd., The Boeing Company, Airbus SE, Sabre Corporation |
Frequently Asked Questions
Key players in the Connected Aircraft Market include Honeywell Aerospace, Collins Aerospace, Thales Group, Viasat Inc., and Panasonic Avionics Corporation, among others.
Key opportunities in the Connected Aircraft Market include predictive analytics and advanced passenger engagement platforms for higher-margin recurring revenue and hybrid multi-orbit connectivity balancing coverage, latency, and capacity.
The market is driven by rising passenger expectations for gate-to-gate broadband, combined with mandated real-time aircraft tracking under ICAO's Global Aeronautical Distress and Safety System rule.
The Commercial Aviation segment dominated the Connected Aircraft Market, accounting for approximately 69.55% market share.
The North America region dominated the Connected Aircraft Market in 2025 with approximately 38.35% share, driven by early adoption among commercial carriers and extensive business jet penetration.
