
eVTOL Aircraft Market Report Scope & Overview:
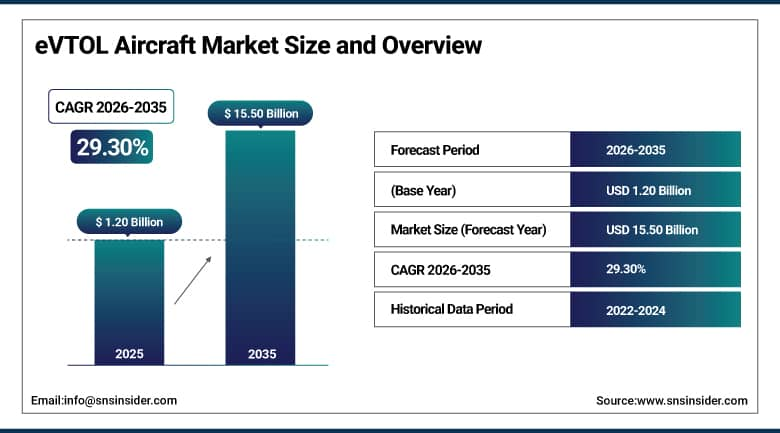
The eVTOL Aircraft Market was valued at USD 1.20 Billion in 2025 and is expected to reach USD 15.50 Billion by 2035, growing at a CAGR of 29.30% from 2026-2035.
The Growth in the eVTOL Aircraft Market is mainly fueled by the increase in the pace of urbanization and the rise in road traffic congestion, which has created a constant need for faster and point-to-point means of transportation offered by eVTOL aircrafts at much lower cost than conventional helicopters. The consistent improvements in the energy density of batteries and the power-to-weight ratio have continued to expand the maximum distance and load that the aircraft can carry, gradually narrowing the performance gap that used to exist between electric aircrafts and commercial passenger flights.
Joby Aviation announced on March 11, 2026 that it had begun flight testing its first FAA-conforming aircraft for Type Inspection Authorization, a major milestone on the path to type certification and a step the company achieved just days after the U.S. government cleared mature aircraft designs to begin early operations across ten states under the White House-backed eVTOL Integration Pilot Program.
To Get More Information On eVTOL Aircraft Market - Request Free Sample Report
eVTOL Aircraft Market Trends
-
Accelerating progress toward FAA and EASA type certification as leading developers complete Type Inspection Authorization testing.
-
Growing government support for dedicated air mobility testing corridors and eVTOL integration pilot programs across multiple states.
-
Rising developer focus on Middle East launch markets, including Dubai and Abu Dhabi, ahead of domestic U.S. certification completion.
-
Expanding vertically integrated manufacturing strategies reducing third-party supplier dependence and shortening development timelines.
-
Increasing airline partnership activity as commercial carriers explore integrated air taxi booking and ground transportation connections.
-
Growing interest in cargo and medical evacuation applications as complementary near-term revenue paths ahead of full passenger certification.
U.S. eVTOL Aircraft Market Outlook
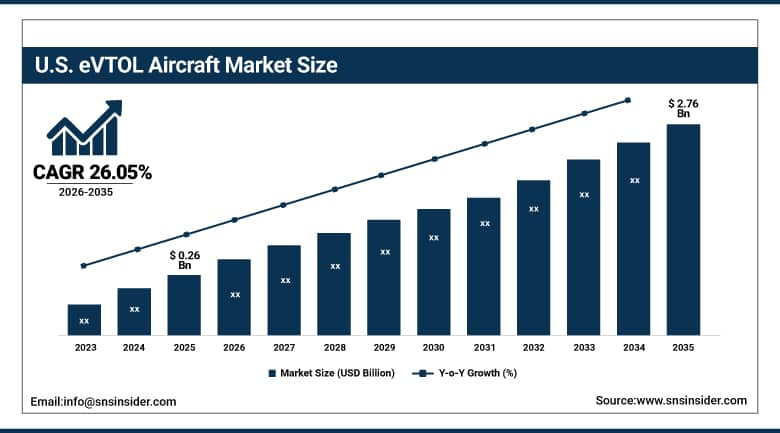
The U.S. eVTOL Aircraft Market was valued at USD 0.26 Billion in 2025 and is expected to reach USD 2.76 Billion by 2035, growing at a CAGR of 26.05% from 2026-2035.
U.S. eVTOL Aircraft Market growth is continuously bolstered by continued strong leadership from native developers such as Joby Aviation and Archer Aviation, all while seeking FAA type certification at the same time they forge commercial deals with major airlines and ground transport companies. The continuous backing by the federal government of advanced air mobility integration, through the creation of test corridors under recently enacted pilot programs, further accelerates progress from prototype testing to revenue-generating domestic commercial service.
The White House-backed eVTOL Integration Pilot Program cleared the way for mature aircraft designs to begin early operations across Arizona, Florida, Idaho, New Jersey, New York, North Carolina, Oklahoma, Oregon, Texas, and Utah beginning in 2026, marking a significant milestone for the domestic industry.
eVTOL Aircraft Market Segment Analysis
-
By Lift Technology, the Vectored Thrust segment dominated the eVTOL Aircraft Market with approximately 43.60% share in 2025, while the Multirotor segment is the fastest growing with a CAGR of approximately 31.80%.
-
By Mode of Operation, the Semi-Autonomous segment dominated the eVTOL Aircraft Market with approximately 38.60% share in 2025, while the Fully Autonomous segment is the fastest growing with a CAGR of approximately 33.40%.
-
By Application, the Urban Air Taxi segment dominated the eVTOL Aircraft Market with approximately 63.60% share in 2025, while the Medical Evacuation segment is the fastest growing with a CAGR of approximately 33.70%.
-
By Maximum Take-Off Weight, the Less than 250 kg segment dominated the eVTOL Aircraft Market with approximately 44.60% share in 2025, while the 250-500 kg segment is the fastest growing with a CAGR of approximately 30.40%.
By Lift Technology, Vectored Thrust Dominates the eVTOL Aircraft Market and Multirotor Grows Fastest
Designs using vectored thrust technology continue to dominate in the lift technology segment, with advantages such as being favored by prominent manufacturers like Joby Aviation and Archer Aviation due to their capabilities to achieve efficient forward cruise flights with vertical takeoff and landing. This characteristic makes them suitable for urban air taxi operations that require higher ranges. Designs using multirotor technology enjoy an easier route toward conducting flight tests because of the lack of complicated tilting systems which make their prototyping process fast.
Multirotor technology is currently experiencing accelerated growth in the lift-technology segment owing to the simple mechanical nature and reduced cost of development compared to the tilting-rotor vectored thrust. Increasing cargo and short-range urban mobility applications, where simple hover platforms will suffice, are some of the factors driving this growth.
By Mode of Operation, Semi-Autonomous Dominates the eVTOL Aircraft Market and Fully Autonomous Grows Fastest
Semi-autonomous operation currently leads the mode-of-operation segment, reflecting the near-term regulatory reality that most certification pathways still require a human pilot on board even as flight control systems increasingly automate routine functions. Cargo and logistics applications are emerging as the most likely near-term pathway toward fully autonomous certification, given their lower regulatory tolerance threshold than passenger-carrying missions where human oversight remains a near-term expectation.
Fully autonomous operation represents the fastest-growing category, as continued advancement in sensor fusion and flight control software gradually builds the safety case regulators require before removing the pilot entirely. Cargo and logistics applications are emerging as the most likely near-term pathway toward fully autonomous certification given their lower regulatory tolerance threshold than passenger-carrying missions.
By Application, Urban Air Taxi Dominates the eVTOL Aircraft Market and Medical Evacuation Grows Fastest
Urban air taxis remain the market segment leader within applications, given the nature of the innovation as being a means of addressing traffic problems and the significant amount of funding that has been allocated by key innovators to develop infrastructure and airline alliances related to passenger air mobility services. Rural health-care access programs are further solidifying the position of the above average growth rate within this market segment.
Medivac is the fastest-growing market segment application, owing to the growing recognition among health-care systems of the value of eVTOL aircraft for emergency air transport, which is faster, more silent, and less expensive than helicopter services. Rural health-care access programs are further solidifying the position of the above average growth rate within this market segment.
By Maximum Take-Off Weight, Less than 250 kg Dominates the eVTOL Aircraft Market and 250-500 kg Grows Fastest
Aircraft under 250 kg maximum take-off weight hold the largest share by weight class, reflecting strong adoption of small, unmanned eVTOL platforms for commercial delivery and light surveillance applications that require lower certification complexity than larger passenger-carrying designs. Regulatory pathways for this weight class typically involve less stringent certification requirements than larger passenger-carrying designs, allowing manufacturers to reach commercial deployment on a meaningfully faster timeline than multi-passenger aircraft developers currently face.
The 250-500 kg weight class represents the fastest-growing category, driven by rising demand for close-range and short-range eVTOL vehicles capable of carrying meaningful cargo or a single passenger while remaining within a more manageable regulatory and infrastructure footprint than larger multi-passenger designs. Manufacturers targeting this weight class are increasingly positioning their aircraft for both light cargo delivery and single-passenger air taxi applications, a dual-purpose design strategy that broadens the addressable commercial market beyond either application alone.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.80% |
|
Europe |
Germany |
27.20% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
26.40% |
|
Middle East & Africa |
UAE |
34.80% |
North America eVTOL Aircraft Market Insights
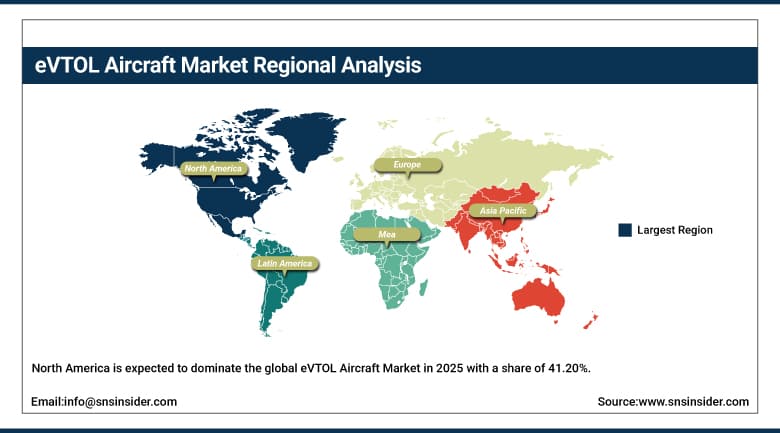
North America is expected to dominate the global eVTOL Aircraft Market in 2025 with a share of 41.20%. This is attributed to the presence of local aircraft developers such as Joby Aviation and Archer Aviation, which are working on achieving FAA type certification and establishing commercial alliances with major airlines in the U.S. Region. Consistent VC investments and governmental support for the integration of advanced air mobility further strengthen the dominance of this region. The ongoing development of dedicated testing corridors in multiple states ensures continuous growth. This is because, in recent times, local developers regard operational data obtained during these testing programs as necessary before nationwide certification is achieved.
The Canadian region adds more value to the North American market through its developing advanced air mobility regulations and growing developer alliances. Consistent growth in dedicated testing corridors in multiple states in the U.S. region helps sustain commercial growth momentum. Mexico, owing to its growing interest in advanced air mobility infrastructure, helps tie up the North American market.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe eVTOL Aircraft Market Insights
Europe is expected to grow with the highest CAGR for the eVTOL Aircraft Market during the forecast period 2026-2035, which stands at around 22.40%, thanks to Germany being well-established as a base for Volocopter – the pioneer in urban air mobility, which has been planning to introduce passenger air taxis in different European cities. The continuing development of the EASA regulatory framework will further fuel Europe's rapid development since its regulatory body keeps refining the safety standards, which are specific only to electric vertical take-off and landing aircraft instead of using helicopter regulations.
In the UK, Vertical Aerospace keeps pursuing EASA aviation safety certification and is working towards passenger flight certification until 2028. The continuing development of the EASA regulatory framework will further fuel Europe's rapid development. In France, the Groupe ADP continues building vertiports for the future launch of eVTOL aircraft.
Asia Pacific eVTOL Aircraft Market Insights
The Asia-Pacific market constitutes an important and quickly developing market for the industry with China's EHang Holdings being one of the leading manufacturers of passenger-grade autonomous aerial vehicles and XPeng AeroHT flying cars development program ongoing. The increase of domestic production capacities in the region will only solidify the region's importance as a major participant in the global eVTOL development with several governments actively courting manufacturers in their respective testing zones.
Other sources of demand in the region include Japan and South Korea with their growing initiatives in advanced air mobility. The increase of domestic production capacities in the region will only solidify the region's importance as a major participant in the global eVTOL development. India's increased interest in advanced air mobility along with increased interest in aerospace manufacturing will play an important role in the development of the Asia-Pacific region.
MEA & Latin America eVTOL Aircraft Market Insights
The Middle East and Africa region reflects growing strategic importance, with the UAE accounting for the largest regional contribution as both Joby Aviation and Archer Aviation have selected Dubai and Abu Dhabi respectively as likely locations for their first commercial passenger-carrying flights ahead of full U.S. certification completion. Gradual regional regulatory framework development continues to support steady market growth, as several Gulf state governments actively court international developers through dedicated air mobility investment zones and streamlined operational licensing processes.
Latin America remains a smaller contributor to global demand, with Brazil accounting for the majority of regional interest tied to its growing urban mobility infrastructure investment. Gradual regional regulatory framework development continues to support steady market growth. Mexico and Argentina contribute additional secondary demand tied to their respective urban mobility modernization programs, with both countries continuing to monitor international certification progress before committing to significant domestic infrastructure investment.
Market Dynamics
Growth Drivers: Urban Congestion and Battery Technology Advancement
Urbanization and increased congestion levels in the roads are the most important drivers for market growth, with eVTOLs providing significantly faster journeys and more economical cost compared to conventional helicopters for point-to-point transportation within the cities. Increased attention from developers towards air mobility testing corridors and international launch markets also helps in supporting the aforementioned demand trend, with increasing emphasis on early revenue creation before the completion of domestic certification process.
Increased efficiency in the development of batteries in terms of energy density and power-to-weight ratio also constitutes another major driver for growth, as increased efficiency improves the range and payload capacity of the vehicle. Increased financial investment by private and public entities also supports the aforementioned trend in terms of underlying demand dynamics. Increased government support towards air mobility testing corridors and regulatory harmonization also supports the underlying demand dynamics, as developers find it easier to obtain certifications.
Restraints: Certification Delays and High Development Costs
Persistently delayed regulatory certification timelines represent a significant restraint, as leading developers have repeatedly pushed back commercialization targets amid the substantial technical and safety validation required before any eVTOL aircraft can carry paying passengers. Public market skepticism toward pre-revenue aerospace developers has also contributed to meaningful stock price volatility, complicating capital raising efforts for companies still years away from sustained commercial passenger operations at scale.
The substantial capital investment required to reach certification, often totaling hundreds of millions of dollars annually with minimal near-term revenue, adds a further restraint, contributing to significant stock price volatility among publicly traded developers. Supply chain dependencies on specialized battery cells and lightweight composite materials add further complexity for developers seeking to scale production beyond current prototype and pre-certification manufacturing volumes.
Opportunities: International Launch Markets and Cargo Applications
Middle East launch markets present a substantial growth opportunity, as leading developers pursue earlier commercial revenue through UAE operations ahead of completing domestic U.S. or European certification, allowing real-world operational validation while regulatory processes continue. Suppliers that successfully validate compact, cost-competitive cargo and medical evacuation platforms are positioned to capture meaningful near-term commercial revenue while continuing to advance toward the more complex passenger certification pathway.
Cargo transport and medical evacuation applications represent a further opportunity, as these use cases often face a lower regulatory bar than passenger-carrying urban air taxi service, allowing developers to generate earlier revenue while continuing to pursue full passenger certification. Government-backed testing corridor programs are also expected to broaden the pool of markets where developers can generate early operational revenue, gradually normalizing what has historically been a tightly constrained pre-certification commercial pathway.
Recent Developments:
-
On February 28, 2025, Archer Aviation announced it had signed Abu Dhabi Aviation as its first international launch partner, while continuing work with United Airlines and Southwest Airlines to plan initial U.S. operations in Los Angeles, San Francisco, Miami, and New York City.
-
In December 2025, Joby Aviation completed its first piloted point-to-point air taxi flight in the United Arab Emirates, flying from its test facility in Margham to Al Maktoum International Airport ahead of the Dubai Airshow.
-
In November 2025, Joby Aviation became the first eVTOL manufacturer to reach Stage 4 of the FAA's certification process, positioning the company for potential Type Certificate issuance in late 2025 or early 2026.
-
Vertical Aerospace continued pursuing certification under the European Union Aviation Safety Agency throughout 2025, targeting passenger flight certification by 2028, even as the company's market value declined by nearly 58% over the course of the year.
eVTOL Aircraft Market Key Players
-
Joby Aviation, Inc.
-
Archer Aviation Inc.
-
EHang Holdings Ltd.
-
Eve Holding, Inc.
-
Airbus SE
-
Textron Inc. (Bell)
-
Embraer S.A.
-
Elbit Systems Ltd.
-
Kitty Hawk Corporation
-
Beta Technologies, Inc.
-
Volocopter GmbH
-
SkyDrive Inc.
-
Electra.Aero, Inc.
-
Lilium GmbH
-
Elroy Air, Inc.
-
Pipistrel d.o.o.
-
Wisk Aero LLC
-
Vertical Aerospace Group Ltd.
-
XPeng AeroHT
-
Overair, Inc.
eVTOL Aircraft Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.20 Billion |
| Market Size by 2035 | USD 15.50 Billion |
| CAGR | CAGR of 29.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Lift Technology (Vectored Thrust, Multirotor, Lift Plus Cruise) • by Range (Less than 50 km, 50-150 km, Greater than 150 km) • by Mode of Operation (Piloted, Semi-Autonomous, Fully Autonomous) • by Passenger Capacity (1-2 Seats, 3-6 Seats, Cargo/Unmanned) • by Application (Urban Air Taxi, Cargo Transport/Last-Mile Delivery, Medical Evacuation) • by Maximum Take-Off Weight (Less than 250 kg, 250-500 kg, 500-1,500 kg, Greater than 1,500 kg) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Joby Aviation, Inc., Archer Aviation Inc., EHang Holdings Ltd., Eve Holding, Inc., Airbus SE, Textron Inc. (Bell), Embraer S.A., Elbit Systems Ltd., Kitty Hawk Corporation, Beta Technologies, Inc., Volocopter GmbH, SkyDrive Inc., Electra.Aero, Inc., Lilium GmbH, Elroy Air, Inc., Pipistrel d.o.o., Wisk Aero LLC, Vertical Aerospace Group Ltd., XPeng AeroHT, Overair, Inc. |

Frequently Asked Questions
Key players include Joby Aviation, Inc., Archer Aviation Inc., EHang Holdings Ltd., Eve Holding, Inc., and Airbus SE, among other leading aerospace and air mobility developers.
Middle East launch markets ahead of full domestic certification and cargo transport and medical evacuation applications represent the primary opportunities.
Growth is primarily driven by rapid urbanization and rising road traffic congestion combined with continued improvement in battery energy density and power-to-weight ratios.
By Application, Urban Air Taxi dominated the market with approximately 63.60% share in 2025, reflecting the technology's origins as a solution for urban road congestion.
North America dominated the market with approximately 41.20% share in 2025, supported by domestic developers Joby Aviation and Archer Aviation advancing toward FAA certification.
