
Flight Simulator Market Report Scope & Overview:
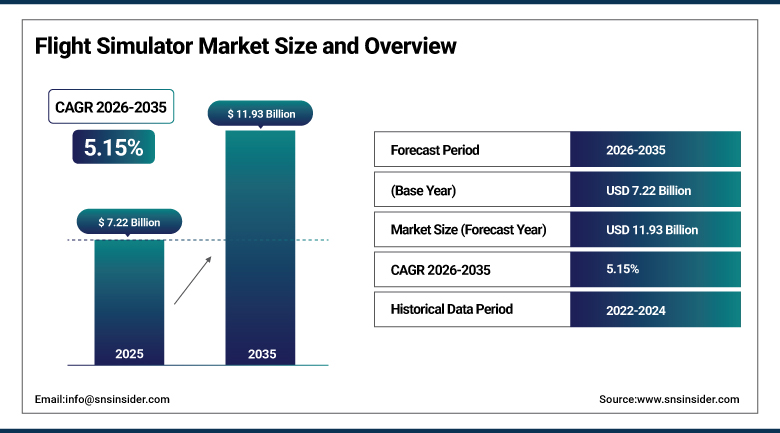
The Flight Simulator Market was valued at USD 7.22 Billion in 2025 and is expected to reach USD 11.93 Billion by 2035, growing at a CAGR of 5.15% from 2026 to 2035.
The Flight Simulator Market is expanding at a very fast rate due to increasing demands for efficient virtual training in the aviation industry. The flight simulators are modern training machines that imitate flight characteristics of an aircraft, cockpit instrumentations, and operating environments and revolutionize the process of pilots’ training and certification through advanced and safe training systems in commercial, military, and unmanned aircraft industries. Moreover, the growth of the market is supported by strict aviation safety regulations, extensive use of simulators by the commercial airlines, military bodies, and flight schools and increased investments in mixed reality and virtual reality procedural trainers indicating confidence in immersive training technologies.
FAA Part 419 sets a new type rating regime for powered lift aircraft with simulation training time as a must for airline-like urban air mobility operations using the CAE 700MXR that utilizes mixed reality visualizations, compact six axis motion and AI traffic generators to recreate urban scenario environments that cannot be replicated by the conventional helicopter simulators.
To Get more information Flight Simulator Market - Request Free Sample Report
Flight Simulator Market Trends
- Rising mixed-reality and virtual-reality procedural trainers are pacing the flight simulator market, signaling operator confidence in immersive technologies for non-maneuver training tasks.
- Growing regulatory frameworks, including FAA Part 419 establishing a new type-rating regime for powered-lift aircraft, are making simulator hours a prerequisite for emerging urban air mobility operations.
- Increasing demand for unmanned aerial vehicle pilot training is expanding simulator applications beyond traditional manned aircraft into diverse defense, surveillance, and commercial UAV operations.
- Expanding fleet of commercial aircraft and increasing air traffic continue to create sustained demand for new and skilled pilots, further contributing to simulator training market growth.
- Strategic partnerships among simulator manufacturers, airlines, and defense organizations are supporting development of increasingly advanced, application-specific flight training technology.
U.S. Flight Simulator Market Outlook
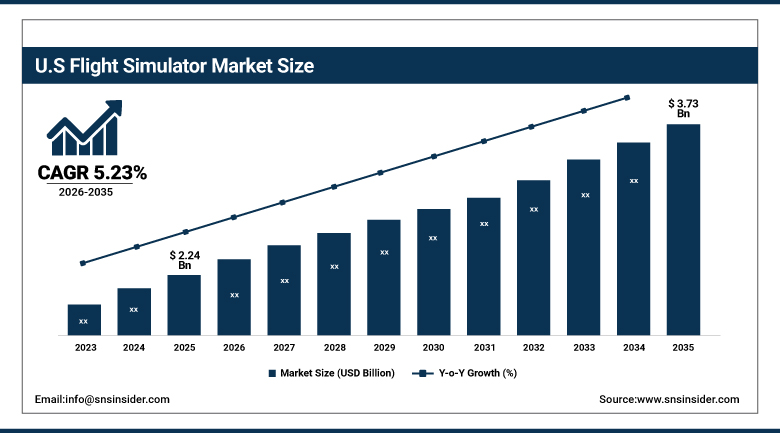
The U.S. Flight Simulator Market was valued at USD 2.24 Billion in 2025 and is projected to reach USD 3.73 Billion by 2035, growing at a CAGR of 5.23% during 2026–2035.
The companies that manufacture simulators in the country are continually expanding their production capacity due to the wide use of flight simulators in training pilots by the U.S. military and high demands from major commercial airlines. The increasing regulatory focus on advanced pilot training and certification, coupled with increased growth of commercial aviation fleets, is helping to bolster the continued domestic demand for flight simulators in the aviation training market in the country.
The United States is the leading country in North America with approximately 31% of global market share in the Flight Simulator Market due to the wide use of flight simulators in training pilots by the U.S. military and high demands from major commercial airlines.
Flight Simulator Market Segment Analysis
- By Simulator Type, full-flight simulator (FFS) dominated the flight simulator market with around 48.78% share in 2025, while mixed/virtual reality procedural trainers is the fastest-growing simulator type segment with a CAGR of 7.23% from 2026–2035.
- By Aircraft Platform, fixed-wing dominated the flight simulator market with around 59.92% share in 2025, while eVTOL/advanced air mobility is the fastest-growing aircraft platform segment with a CAGR of 9.42% from 2026–2035.
- By End User, commercial dominated the flight simulator market with around 61.70% share in 2025, while military/unmanned is the fastest-growing end user segment with a CAGR of 8.30% from 2026–2035.
- By Method, synthetic dominated the flight simulator market with a 68.60% share in 2025, while virtual is the fastest-growing method segment with a CAGR of 8.60% from 2026–2035.
By Simulator Type, Full-Flight Simulator (FFS) dominated the Flight Simulator Market, while Mixed/Virtual Reality Procedural Trainers is the fastest-growing segment.
The Full Flight Simulator accounted for 48.78% of total revenues in 2025. In the Flight Simulator Market, the Full Flight Simulator is the largest product type segment. The popularity of the full flight simulator segment results from the fact that regulations require sophisticated training of pilots in addition to the high quality and fidelity of such simulators in recreating the aircraft environment.
Mixed Reality & Virtual Reality procedural trainers continue to gain momentum within the flight simulator market, registering a CAGR of 7.23%. Operator faith in immersive technologies for non-manuever related operations has helped this segment register steady growth. Increased usage of Mixed reality visuals, six axis motion, and artificial intelligence traffic generators has contributed towards the increasing growth of this segment.
By Aircraft Platform, Fixed-Wing dominated the Flight Simulator Market, while eVTOL/Advanced Air Mobility is the fastest-growing segment.
Fixed-wing devices commanded 59.92% of the 2025 flight simulator market size on the back of commercial airline demand. The fixed-wing simulator segment dominated the market due to the expanding fleet of aircraft and increasing air traffic, which create sustained demand for new and skilled pilots, further contributing to segment growth across commercial and military fixed-wing aviation training worldwide.
The eVTOL segment is slated for the fastest expansion at 9.42% CAGR. FAA Part 419 establishing a new type-rating regime for powered-lift aircraft is making simulator hours a prerequisite for airline-style urban air mobility operations, driving rapid segment growth as advanced air mobility platforms increasingly enter commercial certification pathways requiring dedicated simulator training infrastructure.
By End User, Commercial dominated the Flight Simulator Market, while Military/Unmanned is the fastest-growing segment.
The commercial segment accounted for the largest share of the global flight simulator market at 61.70% in 2025, driven by increasing air passenger traffic and rising demand for commercial aircraft deliveries. Commercial applications remain the dominant end-user category owing to airlines' sustained investment in high-fidelity training infrastructure supporting pilot certification and recurrent training requirements worldwide.
The unmanned aircraft segment is expected to expand at the highest CAGR of 8.30% during 2026-2034, supported by rising deployment of unmanned aerial vehicles across defence, surveillance, logistics, and commercial applications. Growing investments in specialised UAV pilot training are driving rapid segment growth, as diverse UAV applications continue to expand across military and civilian operational contexts.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.20% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Flight Simulator Market Insights
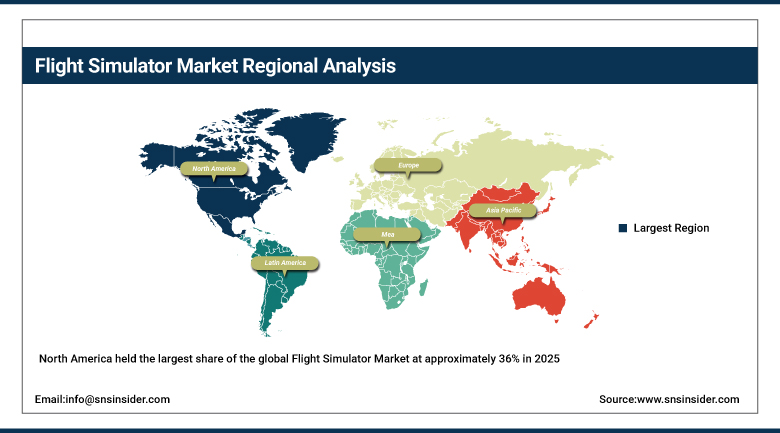
North America held the largest share of the global Flight Simulator Market at approximately 36% in 2025, driven by its large commercial aviation fleet, extensive military pilot-training requirements, and well-established aviation training infrastructure. The region benefits from the presence of leading flight simulator manufacturers and training solution providers, including CAE and L3Harris Technologies. Growing aircraft deliveries, pilot shortages, fleet modernization, and increasing emphasis on cost-effective and risk-free pilot training are further supporting demand for advanced flight simulation systems.
The U.S. was the leading country within the North America Flight Simulator Market in 2025, accounting for approximately 31% of the global market, supported by extensive military pilot-training programs and a large commercial aviation sector. The U.S. military relies heavily on simulation-based training to improve pilot readiness while reducing operational costs and aircraft wear. Canada is also contributing to regional growth through its expanding commercial and military aviation training infrastructure, alongside increasing adoption of advanced simulator technologies for pilot preparation and recurrent training.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Flight Simulator Market Insights
The Europe Flight Simulator Market was a major contributor in 2025, supported by the region’s strong commercial aviation ecosystem, established aerospace manufacturing base, and presence of leading flight simulation technology providers. Continued defense modernization, rising demand for advanced pilot training, and increasing adoption of simulator-based training are supporting regional expansion. The region’s emphasis on aviation safety, pilot proficiency, and cost-efficient training is further encouraging investments in high-fidelity flight simulation systems across commercial and military aviation.
Germany represents one of the major markets in Europe, supported by its strong aerospace manufacturing capabilities, established aviation industry, and growing investment in advanced pilot training infrastructure. France, with major aerospace and defense technology companies such as Thales Group, also contributes significantly to regional market development through advanced simulation and training solutions. The Netherlands further supports regional growth through its aviation and aerospace ecosystem, increasing adoption of sophisticated flight training systems, and demand for modern simulation technologies across commercial and military aviation applications.
Asia Pacific Flight Simulator Market Insights
The Asia Pacific Flight Simulator Market is expected to register the fastest regional growth during the forecast period. Market expansion is supported by rapid commercial aviation fleet growth, rising air passenger traffic, increasing aircraft deliveries, and development of domestic pilot-training infrastructure across major regional economies. Growing investments in aviation academies, simulator-based training, and advanced flight training technologies are helping airlines and training organizations address rising pilot requirements while improving training efficiency, safety, and operational readiness.
China is one of the primary growth drivers in the Asia Pacific Flight Simulator Market, supported by its expanding commercial aviation sector, increasing aircraft fleet, and rising demand for qualified pilots and domestic training capacity. India is also contributing significantly through rapid air traffic growth, airline fleet expansion, and investments in pilot-training infrastructure. Meanwhile, Southeast Asian countries are supporting regional growth through increasing passenger air travel, expanding airline fleets, and greater investment in aviation academies and advanced flight simulation technologies.
Middle East & Africa and Latin America Flight Simulator Market Insights
The Middle East & Africa Flight Simulator Market is gradually becoming larger due to the development of commercial airlines, military forces, and construction of infrastructure to train pilots in these regions. The growth in the number of airline fleets, an increasing number of passengers, and creation of high-end aviation academies are driving the need for highly advanced simulation technologies. UAE and Saudi Arabia are two main markets in this region, backed up with investments into national airline fleet expansion, aviation infrastructure, and military training facilities. The focus on the development of pilot skills and safety requirements is driving simulator use.
Brazil is projected to continue being one of the key regional markets due to the significant presence of the aircraft manufacturing company, Embraer, as well as the size of the local aviation industry and the increasing need for pilots. Aircraft deliveries and investments in the creation of aviation training centers are fueling the demand for flight simulation systems.
Market Dynamics
Growth Drivers: Rising cost-effective virtual training demand and safety regulation driving market growth
An increasing demand for affordable virtual training solutions in the aviation sector along with aviation safety regulations is expected to be the key factor propelling the Flight Simulator Market. The flight simulator market is fundamentally transforming the learning and certification process for pilots through advanced and risk-free training solutions, thereby maintaining robust demand among commercial airlines, defense forces, and flight training institutes across the globe.
Increasing usage of advanced simulators by commercial airlines and defense forces, increasing number of aircraft and air traffic, as well as the demand for pilots is fueling market growth. Increasing usage of UAVs in the defense, surveillance, and commercial sectors, increasing investments for UAV pilot training, and regulations for the certification of advanced air mobility are some other factors that will contribute to the demand during the forecast period.
Restraints: High equipment costs and long procurement cycles limiting market expansion
One of the main barriers to market growth is the substantial capital cost associated with full-flight simulator acquisition and maintenance, which continues to constrain broader adoption among smaller flight training academies and operators facing limited capital equipment budgets.
Additionally, extended procurement and certification timelines for advanced simulator platforms continue to introduce project delivery uncertainty for manufacturers and training providers negotiating complex regulatory approval processes. The technical complexity of continuously updating simulator software and hardware to match evolving aircraft platforms further requires substantial ongoing investment in technology refresh cycles.
Opportunities: Expansion of eVTOL certification pathways and unmanned pilot training creating new growth avenues
FAA Part 419 establishing a new type-rating regime for powered-lift aircraft represents a substantial market opportunity, as simulator hours become a prerequisite for airline-style urban air mobility operations, creating demand for purpose-built eVTOL training infrastructure.
There is a considerable growth opportunity in the continued expansion of specialized UAV pilot training programs addressing rising deployment across defense, surveillance, logistics, and commercial applications. The expansion of commercial aviation fleet growth and pilot training infrastructure investment in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2026: L3Harris Technologies expanded its military flight simulator production capacity, strengthening its ability to supply growing allied defense force demand for advanced pilot training infrastructure.
- 2026: FlightSafety International launched an updated full-flight simulator platform for business jet pilot training, offering operators enhanced fidelity and certification-ready training capability.
- 2025: CAE's 700MXR simulator leveraged mixed-reality visuals, compact six-axis motion, and AI traffic generators to create urban environment training scenarios that legacy helicopter simulators cannot replicate, supporting emerging urban air mobility pilot certification requirements.
- 2025: FAA Part 419 established a new type-rating regime for powered-lift aircraft, making simulator hours a prerequisite for airline-style urban air mobility operations across the domestic aviation training market.
Flight Simulator Market key players are:
- CAE Inc.
- L3Harris Technologies, Inc.
- Collins Aerospace (RTX Corporation)
- Thales Group
- Lockheed Martin Corporation
- FlightSafety International Inc.
- Frasca International, Inc.
- Indra Sistemas, S.A.
- Elite Simulation Solutions AG
- Boeing Global Services (The Boeing Company)
- TRU Simulation + Training Inc. (Textron)
- Rheinmetall AG
- Kongsberg Gruppen ASA
- Saab AB
- Microsoft Corporation
- Laminar Research
- Dovetail Games
- Redbird Flight Simulations, Inc.
- VRM Switzerland AG
- Precision Flight Controls Inc.
Flight Simulator Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.22 Billion |
| Market Size by 2035 | USD 11.93 Billion |
| CAGR | CAGR of 5.15% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Simulator Type (Full-Flight Simulator (FFS), Mixed/Virtual Reality Procedural Trainers) • By Aircraft Platform (Fixed-Wing, eVTOL/Advanced Air Mobility) • By End User (Commercial, Military/Unmanned) • By Method (Synthetic, Virtual) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CAE Inc.; L3Harris Technologies, Inc.; Collins Aerospace (RTX Corporation); Thales Group; Lockheed Martin Corporation; FlightSafety International Inc.; Frasca International, Inc.; Indra Sistemas, S.A.; Elite Simulation Solutions AG; Boeing Global Services (The Boeing Company); TRU Simulation + Training Inc. (Textron); Rheinmetall AG; Kongsberg Gruppen ASA; Saab AB; Microsoft Corporation; Laminar Research; Dovetail Games; Redbird Flight Simulations, Inc.; VRM Switzerland AG; Precision Flight Controls Inc. |
Frequently Asked Questions
The market is driven by rising demand for cost-effective virtual training in the aviation industry and stringent aviation safety regulations.
The North America region dominated the Flight Simulator Market in 2025, holding approximately 36% market share.
Some of the major companies that operate in the global flight simulator market are CAE, L3Harris Technologies, Collins Aerospace, Thales Group, Lockheed Martin, FlightSafety International, Frasca International, Indra Sistemas, Elite Simulation Solutions, and Boeing Global Services.
Expansion of eVTOL certification pathways and unmanned pilot training creating new growth avenues
The Full-Flight Simulator (FFS) segment dominated the Flight Simulator Market, accounting for approximately 48.78% market share.
