
Frozen Food Packaging Market Report Scope & Overview:
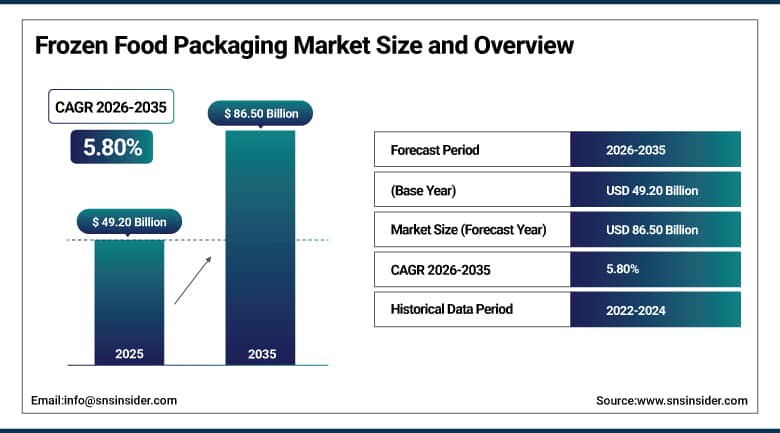
The Frozen Food Packaging Market was valued at USD 49.20 Billion in 2025 and is expected to reach USD 86.50 Billion by 2035, growing at a CAGR of 5.80% from 2026 to 2035.
The frozen food packaging has to solve a problem that most other packaging categories do not: surviving weeks or months at sub-zero temperatures without cracking, delaminating, or letting in enough moisture to cause freezer burn, then performing just as well once it hits a microwave or oven. That dual demand, freezer durability and heat performance, is what keeps this category technically interesting even though frozen food itself is a mature product category in most developed markets. Growth right now is coming less from new frozen food categories and more from packaging upgrades: recyclable mono-material films replacing multilayer barrier structures, portion-controlled formats replacing family-size bags, and e-commerce-ready packaging built for home delivery rather than just retail freezer cases.
In November 2025, Amcor plc launched a recycle-ready frozen-food packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
To Get More Information On Frozen Food Packaging Market - Request Free Sample Report
Frozen Food Packaging Market Trends
- Recyclable mono-material films are replacing multilayer barrier structures across frozen vegetable and meat packaging.
- Portion-controlled tubs and cups are gaining share as single-person households and meal-prep habits grow.
- E-commerce grocery delivery is driving demand for insulated, tamper-evident packaging built for last-mile frozen shipping.
- Paperboard cartons with freezer-grade coatings are expanding in ice cream and bakery categories chasing recyclability targets.
- Smart labels tracking cold-chain temperature history are appearing on premium frozen seafood and meat packaging.
The U.S. Frozen Food Packaging Market Outlook
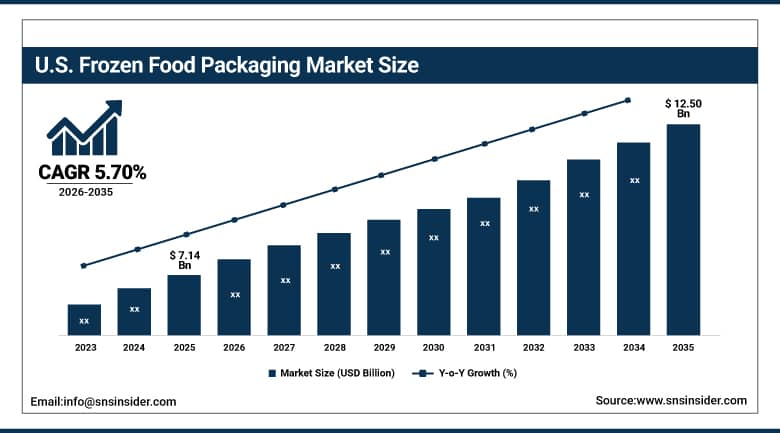
The U.S. frozen food packaging market was valued at USD 7.14 Billion in 2025 and is projected to reach USD 12.50 Billion by 2035, growing at a CAGR of 5.70% during 2026-2035.
Grocery retailers have been steadily expanding frozen aisle footprint over the past several years, and that shelf-space growth is pulling packaging demand along with it as brands compete for visibility in a more crowded freezer case. Portion-controlled and single-serve formats are growing faster than family-size packaging here, tracking a broader shift toward smaller households and grab-and-go eating habits. State-level packaging laws are also having a real effect, pushing frozen food brands toward recyclable paperboard and mono-material film options faster than they might have moved otherwise. Meal-kit and grocery-delivery services have added a newer demand line too, requiring insulated packaging engineered specifically for multi-hour transit rather than retail freezer storage.
In August 2025, Sonoco Products Company introduced a recyclable paperboard tray system for frozen retail packs, designed to replace multilayer plastic trays across major U.S. grocery chains.
Frozen Food Packaging Market Segment Analysis
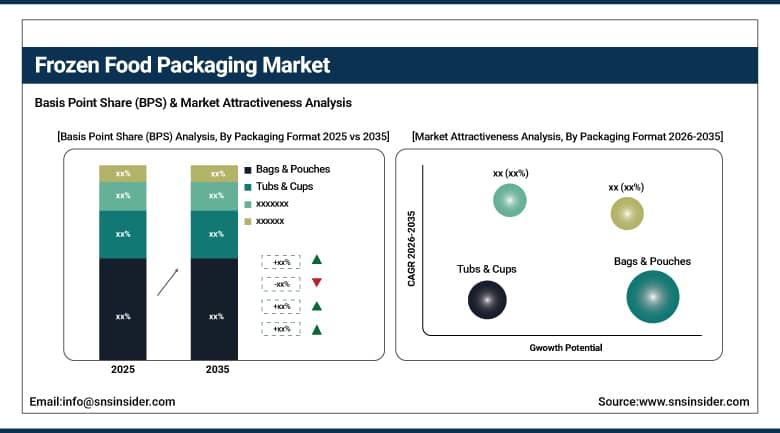
- By Packaging Format, bags & pouches segment dominated the frozen food packaging market in 2025 with 38% share; tubs & cups segment is the fastest-growing segment, registering a CAGR of 8.40% from 2026 to 2035.
- By Material, plastic segment dominated the frozen food packaging market in 2025 with 58% share; paperboard segment is the fastest-growing segment, registering a CAGR of 9.10% from 2026 to 2035.
- By Packaging Type, flexible packaging segment dominated the frozen food packaging market in 2025 with 56% share; rigid packaging segment is the fastest-growing segment, registering a CAGR of 7.20% from 2026 to 2035.
- By Application, meat & poultry segment dominated the frozen food packaging market in 2025 with 34% share; ready meals & bakery segment is the fastest-growing segment, registering a CAGR of 9.80% from 2026 to 2035.
By Packaging Format, bags & pouches dominates the frozen food packaging market, while tubs & cups grows fastest
Bags & pouches hold 38% of the frozen food packaging market, largely because they are the most material-efficient way to package frozen vegetables, fruit, and bulk meat, using less plastic per unit of product than rigid alternatives while still delivering the barrier protection frozen food needs. Resealable zipper closures have become close to standard on this format, which matters for consumers portioning out multi-serving bags over several meals rather than using the whole contents at once.
Tubs & cups are growing at an 8.40% CAGR, the fastest pace among formats, pulled forward largely by ice cream, frozen yogurt, and single-serve dessert categories where the rigid, stackable format suits both retail shelf presentation and at-home portion control. Growing demand for premium and artisanal frozen desserts has reinforced this format's growth, since tubs allow for more elaborate label design and shelf differentiation than a simple bag.
By Material, plastic dominates the frozen food packaging market, while paperboard grows fastest
Plastic remains the dominant material at 58% share, largely because it is still the most reliable option for maintaining a moisture and oxygen barrier at freezer temperatures without cracking or becoming brittle over months of storage. Polyethylene-based films in particular have a long track record in frozen applications, and existing manufacturing infrastructure across the industry is built almost entirely around plastic film and rigid plastic tooling.
Paperboard is growing fastest among materials, at a 9.10% CAGR, as brands respond to plastic-reduction regulations and consumer pressure for curbside-recyclable packaging. Freezer-grade coatings that resist moisture without relying on heavy plastic lamination have improved enough in recent years to make paperboard genuinely viable for ice cream cartons, bakery boxes, and some frozen meal trays, categories where it would have struggled a decade ago.
By Packaging Type, flexible packaging dominates while the frozen food packaging market, rigid packaging grows fastest
Flexible packaging leads the packaging-type category with 56% share, reflecting its lower material use, lighter shipping weight, and compatibility with high-speed automated packing lines used across frozen vegetable and meat processing facilities. Flexible formats also take up less freezer case space per unit of product than rigid alternatives, which retailers value given how limited and expensive frozen aisle real estate has become.
Rigid packaging is growing fastest, at a 7.20% CAGR, driven by rising demand for ready-to-cook and ready-to-eat frozen meals where a tray or bowl format supports direct oven or microwave use without needing to transfer food to separate cookware. Premiumization in the frozen ready-meal category has also favored rigid formats, since they support more elaborate compartmentalized designs than a flexible pouch can offer.
By Application, meat & poultry dominates the frozen food packaging market, while ready meals & bakery grows fastest
Meat & poultry accounts for 34% of application demand, the largest single category, reflecting both the sheer volume of frozen meat sold globally and the more demanding barrier requirements needed to prevent freezer burn and maintain color and texture over extended frozen storage. Vacuum-sealed and modified-atmosphere formats are especially common in this category, given how directly package integrity affects perceived product quality at the point of sale.
Ready meals & bakery is the fastest-growing application, expanding at a 9.80% CAGR, as busy households and rising grocery delivery adoption drive demand for convenient, heat-and-eat frozen options. Packaging for this category has to do more work than most, supporting freezer storage, microwave or oven heating, and often direct table presentation, all in a single format, which is pushing continued innovation in compartmentalized trays and dual-ovenable materials.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
82.40% |
|
Asia Pacific |
China |
33.70% |
|
Europe |
Germany |
25.60% |
|
Middle East & Africa |
UAE |
17.10% |
|
Latin America |
Brazil |
26.40% |
North America Frozen Food Packaging Market Insights
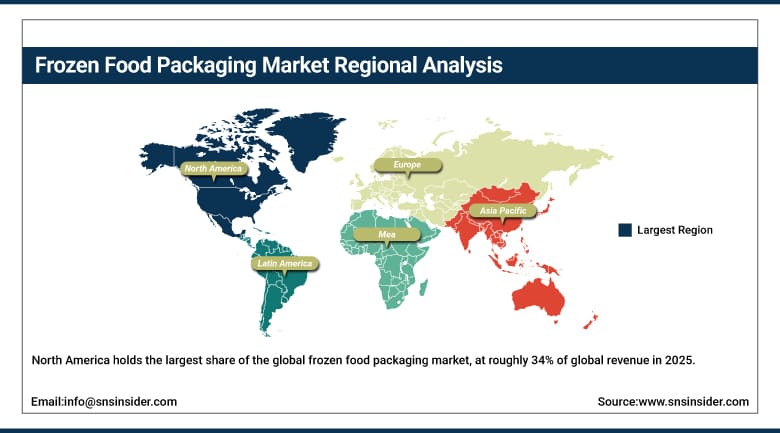
North America holds the largest share of the global frozen food packaging market, at roughly 34% of global revenue in 2025, supported by deeply established frozen food consumption habits and a grocery retail infrastructure built around large dedicated freezer sections. What has changed recently is not demand volume so much as packaging specification, retailers and state regulators are both pushing brands toward recyclable formats faster than in most other regions.
The United States accounts for approximately 82.40% of the North American market, reflecting its large frozen food manufacturing base and extensive grocery and club-store distribution infrastructure. Canada contributes a smaller but steady share, tied to its own packaging waste regulations and a comparably mature frozen food retail sector.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Frozen Food Packaging Market Insights
Europe's frozen food packaging market is mature and steady, shaped by strong frozen food consumption traditions and among the strictest packaging recyclability regulations in the world. The EU's packaging waste rules are forcing faster material transitions here than almost anywhere else, pushing brands toward paperboard and mono-material film alternatives ahead of regulatory deadlines rather than waiting for them.
Germany leads the European market with a 25.60% share, supported by its large frozen food manufacturing base and strict sustainability compliance standards. The United Kingdom and France follow, with the UK's growth tied to its well-established frozen food retail sector and France's driven by expanding ready-meal consumption.
Asia Pacific Frozen Food Packaging Market Insights
Asia Pacific is growing faster than any other region in this market, expanding at roughly a 7.10% CAGR through 2035, as urbanization, rising disposable incomes, and expanding cold-chain retail infrastructure combine to grow frozen food consumption from a much smaller starting base than in North America or Europe. Modern retail formats replacing wet markets in Chinese and Southeast Asian cities are a major part of what is driving this shift, since frozen food essentially requires the kind of retail infrastructure that only organized grocery chains provide.
China holds roughly 33.70% of the regional market, supported by its expanding frozen food manufacturing base and rapidly growing organized retail sector. India and Southeast Asian markets are growing quickly as cold-chain logistics investment expands, while Japan and South Korea contribute through their mature, well-established frozen food retail sectors.
Middle East & Africa and Latin America Frozen Food Packaging Market Insights
The Middle East & Africa region is growing steadily as cold-chain retail infrastructure expands across the Gulf states, supported by rising frozen food import volumes and growing modern grocery penetration. Latin America's growth follows a similar arc, driven by expanding frozen food manufacturing capacity in Brazil and growing urban demand for convenient, ready-to-cook meal options.
The UAE leads the Middle East & Africa market with a 17.10% share, supported by its role as a regional distribution hub for imported frozen food and expanding cold-chain retail infrastructure. Brazil represents 26.40% of the Latin American market, reflecting its sizable frozen food manufacturing base, with Mexico also contributing through its growing organized retail footprint.
Market Dynamics
Growth Drivers: Convenience Demand and Cold-Chain Expansion Fueling Market Growth
Rising demand for convenient, ready-to-eat frozen meals is the clearest driver behind this market's growth, as busy households across both mature and emerging economies lean on frozen food to cut daily meal-prep time. Expanding cold-chain retail infrastructure in emerging markets is opening up frozen food consumption in regions where it barely existed as a retail category a decade ago, creating a second significant growth line alongside steady demand in mature markets.
E-commerce grocery delivery is reinforcing both trends at once, since it is expanding where and how frozen food reaches consumers while simultaneously requiring new packaging formats engineered for multi-hour transit rather than retail freezer storage.
Restraints: Material Cost Volatility and Recyclability Gaps Limiting Market Expansion
Resin and paperboard costs have both been volatile in recent years, making it difficult for packaging suppliers to hold pricing steady with frozen food brands operating on already thin margins. A meaningful share of multilayer barrier packaging, still common across much of the frozen food category, is not accepted in most curbside recycling programs, which puts brands under growing pressure as extended producer responsibility fees increasingly get tied to recyclability.
Freezer-grade performance requirements also limit how quickly brands can switch to newer sustainable materials, since a paperboard or mono-material substitute that fails to prevent freezer burn or moisture ingress is not a viable substitute no matter how much more recyclable it is.
Opportunities: Recyclable Barrier Materials and Smart Packaging Creating New Growth Avenues
The clearest opportunity right now lies in recyclable barrier coatings that let brands move away from multilayer plastic structures without sacrificing the freezer performance frozen food packaging absolutely requires. Suppliers who can commercialize genuinely freezer-grade, curbside-recyclable formats at scale stand to win share as retailers and regulators keep tightening packaging specifications.
Smart, temperature-tracking packaging represents a second opportunity, particularly for premium frozen meat and seafood categories where buyers are willing to pay for verified cold-chain integrity. Partnerships between packaging suppliers and grocery-delivery platforms could also open a distribution-specific packaging category that is still relatively underdeveloped.
Recent Developments:
- 2025: Amcor plc launched a recycle-ready frozen-food packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
- 2025: Sonoco Products Company introduced a recyclable paperboard tray system for frozen retail packs, designed to replace multilayer plastic trays across major U.S. grocery chains.
- 2025: Tetra Pak International S.A. launched ISCC PLUS certified recycled polymer packaging materials in India, containing certified recycled content sourced under the mass balance attribution method.
- 2025: Huhtamaki Oyj launched new compostable and recyclable ice cream cups made from certified paperboard with a bio-based coating, keeping plastic content below 10%.
Frozen Food Packaging Market key players are:
- Amcor plc
- Mondi Group
- Sonoco Products Company
- Sealed Air Corporation
- Huhtamaki Oyj
- International Paper Company
- Smurfit Westrock plc
- Crown Holdings Inc.
- Graphic Packaging International, LLC
- Tetra Pak International S.A.
- Uflex Limited
- Ampac Holdings, LLC
- KOROZO Ambalaj San. ve Tic. A.Ş.
- Alto Packaging Ltd.
- Tray-Pak Corporation
- Amerplast Ltd.
- Constantia Flexibles Group GmbH
- ProAmpac LLC
- Coveris Holdings S.A.
- Winpak Ltd.
Frozen Food Packaging Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 49.20 Billion |
| Market Size by 2035 | USD 86.50 Billion |
| CAGR | CAGR of 5.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Packaging Format (Bags & Pouches, Boxes & Cartons, Trays, Tubs & Cups, Others) • By Material (Plastic, Paperboard, Aluminum Foil, Others) • By Packaging Type (Flexible Packaging, Rigid Packaging) • By Application (Meat & Poultry, Fruits & Vegetables, Seafood, Ready Meals & Bakery, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Mondi Group, Sonoco Products Company, Sealed Air Corporation, Huhtamaki Oyj, International Paper Company, Smurfit Westrock plc, Crown Holdings Inc., Graphic Packaging International, LLC, Tetra Pak International S.A., Uflex Limited, Ampac Holdings, LLC, KOROZO Ambalaj San. ve Tic. A.Ş., Alto Packaging Ltd., Tray-Pak Corporation, Amerplast Ltd., Constantia Flexibles Group GmbH, ProAmpac LLC, Coveris Holdings S.A., Winpak Ltd. |
Frequently Asked Questions
The Bags & Pouches segment dominated the Frozen Food Packaging Market in 2025.
Key players include Amcor plc, Mondi Group, Sonoco Products Company, Sealed Air Corporation, Huhtamaki Oyj, International Paper Company, Smurfit Westrock plc, and Crown Holdings Inc., alongside other established food packaging manufacturers.
Key opportunities include recyclable barrier coatings that maintain freezer-grade performance, smart temperature-tracking packaging for premium categories, and packaging formats engineered specifically for grocery-delivery and e-commerce transit.
The North America region dominated the Frozen Food Packaging Market in 2025, accounting for approximately 34% of global market share.
