
Glyphosate Market Report Scope & Overview:
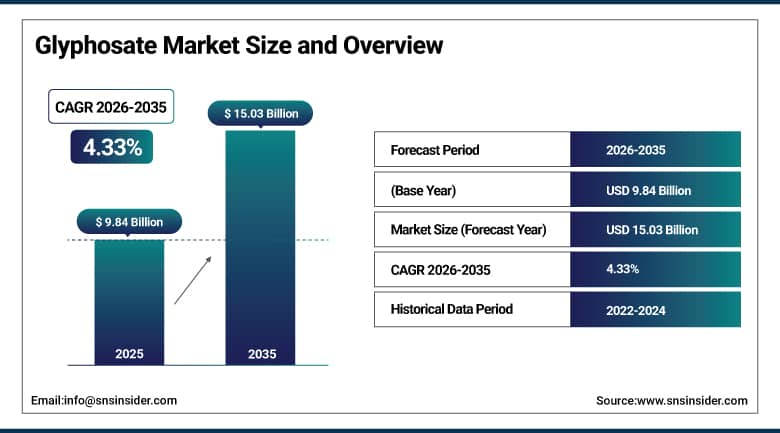
The Glyphosate Market was valued at USD 9.84 Billion in 2025 and is expected to reach USD 15.03 Billion by 2035, growing at a CAGR of 4.33% from 2026-2035.
The Glyphosate Market continues to expand at a steady pace as growers depend on one affordable herbicide for burndown and in-crop weed control. Herbicide-tolerant soybean, corn, cotton and canola systems keep demand anchored in the Americas. Asia Pacific adds volume through expanding generic supply and rising farm mechanization. Liquid concentrates remain the preferred product form because they mix easily and suit standard sprayers. Producers are investing in capacity and supply security while regulators revisit approvals and label rules. Resistant weeds are pushing users toward tank mixtures rather than away from glyphosate. These factors lift market value by about USD 5.19 Billion over the forecast period.
⮞In July 2025, the Food and Agriculture Organization (FAO) reported that global pesticide use reached 3.73 Million tonnes of active ingredient in 2023. Demand on that scale keeps broad-spectrum products such as glyphosate central to crop protection programs.
To Get More Information On Glyphosate Market - Request Free Sample Report
Glyphosate Market Trends:
-
Wider adoption of herbicide-tolerant crop traits keeps glyphosate central to soybean, corn and cotton programs.
-
Tank mixtures with new modes of action are extending the useful life of glyphosate against resistant weeds.
-
Producers are consolidating assets and securing phosphorus supply to protect continuity of glyphosate output.
-
Regulators are resetting approval terms and label rules, which reshapes use patterns and product portfolios.
-
Precision spraying, dry formats and online sales are gaining ground in emerging farm markets.
U.S. Glyphosate Market Outlook:
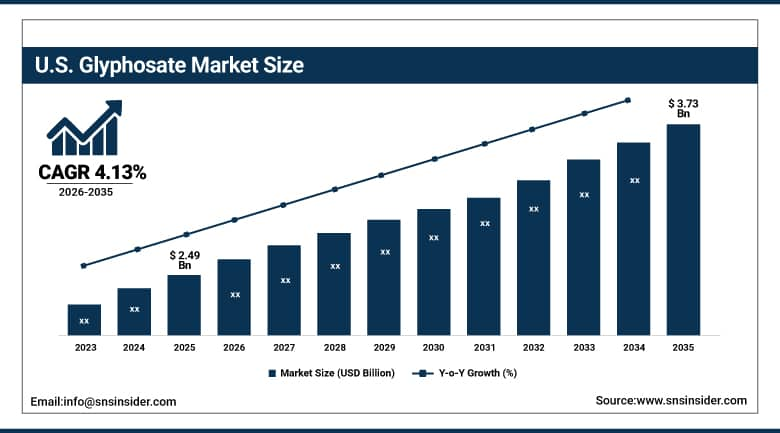
The U.S. Glyphosate Market was valued at USD 2.49 Billion in 2025 and is expected to reach USD 3.73 Billion by 2035, growing at a CAGR of 4.13% from 2026-2035.
The U.S. Glyphosate Market accounts for 86.20% of North American sales and is projected to reach USD 2.59 Billion in 2026. Corn, soybean and cotton growers rely on glyphosate for pre-plant burndown and no-till systems. Herbicide-tolerant seed dominates plantings, so spray programs are built around the molecule. Formulators supply branded and generic products through agricultural retailers and cooperatives. Weed resistance is raising the value of tank mixtures and stewardship services. Federal attention to supply security and label rules adds another layer of planning for suppliers and buyers. Steady acreage and consistent herbicide use support moderate expansion. Retail and cooperative networks keep supply reliable during short spray windows.
⮞In December 2025, the USDA Economic Research Service reported that herbicide-tolerant seed was planted on about 96% of U.S. soybean acres in 2025. Such near-universal adoption keeps post-emergence glyphosate sprays embedded in standard U.S. production practice.
Glyphosate Market Segment Analysis:
-
By Formulation, the Liquid Formulations segment dominated the Glyphosate Market with approximately 74.00% share in 2025, while the Dry Formulations segment is the fastest growing with a CAGR of approximately 5.33%.
-
By Crop Type, the Grains and Cereals segment dominated the Glyphosate Market with approximately 41.00% share in 2025, while the Commercial Crops segment is the fastest growing with a CAGR of approximately 4.83%.
-
By Application, the Agriculture segment dominated the Glyphosate Market with approximately 84.00% share in 2025, while the Non-Agricultural segment is the fastest growing with a CAGR of approximately 5.13%.
-
By Distribution Channel, the Direct Sales segment dominated the Glyphosate Market, while the E-Commerce segment is the fastest growing with a CAGR of approximately 5.93%.
By Formulation, Liquid Formulations Dominate Glyphosate Market; Dry Formulations to Register Fastest Growth.
Liquid concentrates lead because growers can dilute and spray them with equipment already on the farm. They blend smoothly in the tank with partner herbicides and adjuvants and they spread evenly across leaf surfaces so plants absorb the active ingredient quickly. Dosing stays precise on large acreages and works with precision sprayers. Surfactant systems improve rainfastness while established distribution keeps jugs and drums available at nearly every rural retailer. Labor needs per hectare remain low for busy commercial farms.
Dry formats are gaining ground where logistics decide purchases. Granules and powders weigh less per unit of active ingredient, so freight costs and warehouse space requirements both fall. These products tolerate poor water quality and remain stable in hot storage conditions. Village retailers across Africa and parts of Asia can sell small packs without leakage risk or bulk containers. Manufacturers also view water-dispersible granules as a practical route into smallholder markets that liquid drums reach only with great difficulty.
By Crop Type, Grains and Cereals Dominate Glyphosate Market; Commercial Crops to Register Fastest Growth.
Cereal and grain acreage forms the largest base for glyphosate sales because pre-plant burndown is standard practice before maize and wheat seeding. In the Americas corn and soybean rotations run on herbicide-tolerant varieties that allow post-emergence sprays without crop injury. No-till systems protect soil moisture and reduce fuel use across these fields. Large farm sizes and strong mechanization encourage repeated passes with low-cost chemistry. Thin margins per hectare on commodity grain also favor inexpensive weed control across growing seasons.
Cotton and sugarcane lead the expansion in commercial crops as growers seek higher-value harvests. Pre-harvest desiccation improves cotton fiber quality and helps planners schedule sugarcane cutting. Supportive rules for glyphosate-tolerant cotton in Argentina have widened the adoption base for this segment. Because these crops carry higher revenue per hectare, growers are willing to spend on inputs that protect yield and fiber or sugar quality. Processor contracts that reward uniform harvest timing reinforce the habit among large estates and cooperatives.
⮞In June 2026, the USDA National Agricultural Statistics Service reported U.S. soybean plantings of 85.4 Million acres, up 5% from the previous year. Larger plantings of herbicide-tolerant oilseed and row crops translate directly into higher burndown and in-crop spray demand.
By Application, Agriculture Dominates Glyphosate Market; Non-Agricultural to Register Fastest Growth.
Farm use accounts for most glyphosate volumes because the herbicide fits every stage from pre-planting weed clearance to pre-harvest crop management. It reduces hired labor and suits mechanized operations while supporting conservation tillage that protects soil structure. Population growth and food security goals keep cropped area under pressure, and glyphosate remains cheaper than most alternatives per treated hectare. Carbon-credit programs that reward no-till practices add a further financial reason for growers to retain proven herbicide-based systems over several seasons.
Non-agricultural uses are expanding as public agencies and contractors manage vegetation across golf courses, sports fields, utility corridors and transport networks. Urbanization is increasing the area of lawns, turf, stadiums and playgrounds that need dependable weed control. Industrial site managers value a single product that clears broad plant types and cuts the labor cost of mowing or manual removal. Access restrictions around power lines and railways further favor chemical control where safety rules limit crew exposure near live equipment.
⮞In June 2026, the U.S. Supreme Court held in Monsanto v. Durnell that the Federal Insecticide, Fungicide, and Rodenticide Act preempts state failure-to-warn claims in that case. The ruling did not decide whether glyphosate causes cancer, and it addresses labeling requirements for products used on farms and landscapes alike.
By Distribution Channel, Direct Sales Dominate Glyphosate Market; E-Commerce to Register Fastest Growth.
Large growers and cooperatives buy glyphosate in bulk under seasonal supply agreements negotiated directly with manufacturers or their appointed distributors. Direct contracts secure volume ahead of planting, fix pricing across the spray season and deliver agronomic guidance together with stewardship training. Formulators prefer these relationships because they simplify demand forecasting and reduce credit risk across fragmented retail layers. Label compliance and traceability are also easier to document when product moves through a short and accountable chain to every farm.
Online ordering is growing quickly because smallholders and small contractors gain price transparency and doorstep delivery that physical retail rarely matches. Farm input platforms offer smaller pack sizes and digital payment options that suit buyers with limited cash flow. Rising smartphone use in rural areas of Asia and Latin America lowers the barrier to trying new suppliers. Manufacturers also use online channels to reach remote districts where building physical dealer networks is costly and slow to scale in rural areas.
⮞In September 2026, the input distributors association Andav and the Cepea research center reported that Brazil had 1,254 agricultural cooperatives with 1.13 Million members at the end of 2025. Such member networks pool purchases and give manufacturers an organized route for bulk supply to many farms at once.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
52.40 |
|
North America |
United States |
86.20 |
|
Europe |
France |
22.00 |
|
Latin America |
Brazil |
71.30 |
|
Middle East & Africa |
South Africa |
33.60 |
Asia Pacific Glyphosate Market Insights
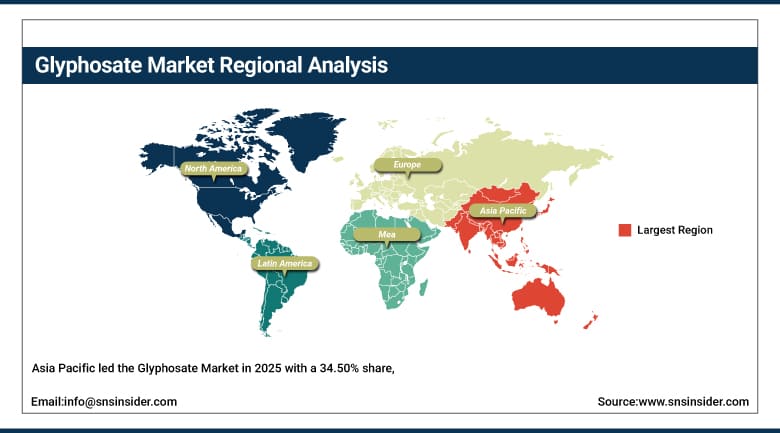
Asia Pacific led the Glyphosate Market in 2025 with a 34.50% share, supported by vast farmland and a large base of price-sensitive growers. China represents 52.40% of regional sales and anchors both consumption and manufacturing, while India, Australia and Southeast Asia add volume through double cropping and expanding generic supply. Glyphosate costs far less than manual weeding in labor-scarce districts, and government programs promoting farm modernization continue to widen access to sprayers and branded inputs. Chinese producers also ship large volumes to Brazil, the United States and Indonesia, which anchors long-term regional capacity planning.
The region is also the fastest growing, with a projected CAGR of 4.93% during 2026-2035. Approvals of herbicide-tolerant corn in China are widening the technology base, and Chinese technical exports keep global supply stable. India is adding mechanization and herbicide-tolerant cotton, while rising farm wages in Southeast Asia push growers away from hand weeding. Pre-plant burndown ahead of double-cropped plantings creates repeat demand across seasons and strengthens volume growth for producers serving local retailers. Large producers are also converting intermediate capacity and integrating raw materials, which supports competitive export pricing and steadier supply to formulators worldwide.
⮞In October 2026, the South Asia Biotechnology Centre reported that unauthorised HTBt cotton covers between 24% and 30% of India’s cotton area. Such spread of tolerant seed lifts glyphosate sprays and shows how informal channels shape demand across the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Glyphosate Market Insights
North America held a 29.40% share in 2025 and is defined here as the United States and Canada because Mexico is reported within Latin America. The United States contributes 86.20% of regional sales through corn, soybean and cotton systems built on herbicide-tolerant seed. Canadian demand is tied to canola and spring wheat, where pre-seed burndown and pre-harvest timing drive purchases. Professional distribution, precision application and mature stewardship practices keep the region among the most value-intensive. Distributor buying groups and agronomic advisers also influence product choice, which rewards suppliers with strong field service.
Competition among brand owners and generic suppliers keeps pricing disciplined, and growers increasingly buy glyphosate as one component of a layered program that includes residual and alternative modes of action. Conservation tillage remains widespread across the Great Plains and the Canadian Prairies, which protects soil moisture and preserves steady burndown volumes. Growth is moderate because planted area is mature, yet any change in acreage mix feeds directly into spray volumes. Resistance management programs in the Midwest and Southern states are lifting use of premixes and tank partners alongside glyphosate. Supply security has also become a boardroom topic for suppliers and large buyers.
⮞In June 2026, Statistics Canada reported canola seeded area of 23.4 Million acres, a record that was up 8.4% from the previous year. Larger canola plantings expand the acreage that requires pre-seed burndown and in-crop weed control.
Europe Glyphosate Market Insights
Europe represented 11.10% of the Glyphosate Market in 2025, with France holding 22.00% of regional sales. Use is concentrated in cereal stubble management, vineyards, olive groves, orchards and vegetation control along infrastructure. Permanent crops on slopes and in dry regions benefit from vegetation control that avoids tillage and the erosion that follows. Authorities in several member states restrict public-space and household applications, and farmers face tighter record-keeping on timing and dose. Integrated weed management and mechanical alternatives therefore compete for share in a market where growth is slow and uneven.
Product development in Europe centers on stewardship and application efficiency. Manufacturers are positioning low-drift nozzles, adjuvant systems that permit reduced doses and training for professional applicators. Rail operators evaluate glyphosate against costlier thermal and mechanical alternatives, and some are reconsidering earlier phase-outs because the alternatives deliver weaker control on gravel and track beds. Conservation agriculture programs that limit plowing also sustain demand for pre-planting burndown. Suppliers with strong regulatory dossiers and local technical teams hold an advantage because registration of formulations remains a national responsibility. Premium adjuvant technology and tank-mix partners are promoted as ways to protect effectiveness at lower doses.
⮞In May 2026, Eurostat reported that plant protection product sales in the European Union reached about 316,000 tonnes in 2024, an increase of 8%. The rebound indicates stronger crop protection spending that benefits established herbicides such as glyphosate.
MEA & Latin America Glyphosate Market Insights
The Middle East and Africa accounted for 4.50% of the Glyphosate Market in 2025, with South Africa holding 33.60% of regional sales. Large commercial farms in South Africa anchor consumption, while Saudi Arabia, the United Arab Emirates, Turkey and Nigeria add smaller volumes. Smallholder demand across East and West Africa relies on village-level retailers who favor compact packs and dry formats. Registration reviews and import controls are tightening, which favors suppliers with local regulatory capability. Imported generic products dominate shelves and price competition among traders is intense. Plantation crops also need regular vegetation control.
⮞In June 2025, the Kenya Pest Control Products Board reviewed 430 end-use pesticide products and withdrew 77 of them. The review did not name glyphosate but it shows the tighter registration scrutiny now applied to products sold through African retail.
Latin America held 20.50% of the market in 2025, led by Brazil with 71.30% of regional sales and followed by Argentina. Mexico belongs to this region and is counted here rather than in North America. Brazil and Argentina together account for a large share of global biotech soybean and corn planting, and those fields depend on glyphosate for burndown and in-crop control. Wide farm sizes and double-cropping systems create several spray windows each year while competitive imports keep prices attractive. Cooperatives and large distributors in Brazil deliver bulk supply and agronomic services directly to growers, which shapes channel structure across the region.
⮞In February 2026, Brazil’s national supply company Conab estimated 2025/26 soybean production at 177.99 Million tonnes. A harvest of that size sustains large annual herbicide programs across the producing states.
Market Dynamics:
Growth Drivers: Wider herbicide-tolerant crop adoption and no-till farming are lifting glyphosate demand
Herbicide-tolerant crop adoption remains the largest single force behind glyphosate demand. Seed companies bundle tolerance with insect resistance and drought traits, so growers seldom separate the herbicide decision from the seed decision. Spraying after weeds emerge simplifies scheduling and supports no-till systems that conserve soil and fuel. Capacity consolidation among producers has also steadied prices, which makes budgeting easier for distributors and farmers. Growers in Brazil, Argentina and the United States have built entire spray calendars around tolerant varieties, which creates predictable demand for burndown and post-emergence applications each season. Stable pricing from consolidated capacity reinforces this routine.
Labor shortages and food security priorities add a second layer of support. Manual weeding is expensive and scarce in many farming regions, and glyphosate treatment costs far less per hectare. Governments are treating herbicide supply as a strategic input, which encourages investment in raw material security and plant upgrades. Carbon-credit programs that pay for no-till practices give growers further reason to keep herbicide-based systems. Expansion of cropped area in South America and Asia adds fresh volume each season while intensification lifts the number of sprays per hectare across major crops.
⮞In February 2026, a White House order under the Defense Production Act noted that only one U.S. producer makes elemental phosphorus and glyphosate-based herbicides and warned that reduced output would threaten food-supply security. The action shows that glyphosate supply is now treated as a matter of agricultural resilience.
Restraints: Regulatory limits and spreading weed resistance are restraining glyphosate sales growth
Regulatory scrutiny constrains growth in several mature markets. Approval renewals, phased use limits and bans on practices such as pre-harvest desiccation reduce the addressable volume for formulators. Health and environmental concerns also shape purchasing decisions by food companies, retailers and public landowners who prefer to avoid the product. Litigation in the United States has added cost and uncertainty for brand owners. Several countries restrict use in public spaces and on household land, and campaigns by advocacy groups keep the issue visible to consumers. These pressures lengthen registration timelines and raise compliance costs for smaller formulators.
Weed resistance is eroding the effectiveness of glyphosate as a stand-alone treatment. Resistant populations have been documented across dozens of countries, which forces growers to add residual herbicides and alternative modes of action to every program. Each added product raises cost per hectare and can shift spending away from glyphosate. Venture funding is also moving toward bio-based herbicides, and low-residue production systems are expanding, which together slow growth in premium segments. Resistance management therefore shifts part of the value chain toward premixes and new chemistry. Growers also face higher scouting and record-keeping workloads.
⮞The European Commission lists glyphosate as approved in the EU until 15 December 2033 and states that desiccation uses are not permitted. Approval terms of this kind cap pre-harvest use and keep European volumes under continuous review.
Opportunities: Herbicide-tolerant corn approvals and emerging farm markets are creating new demand for glyphosate producers
Approval of additional herbicide-tolerant crops opens new acreage for glyphosate in markets that have so far depended on manual weeding or older chemistry. Corn and soybean traits expanding in Asia and Latin America would carry glyphosate into fields where adoption has been slow. Suppliers that bundle seed partnerships, technical support and stewardship services can capture higher value per hectare. Export-focused registration reforms in China also shorten the path to market for producers serving overseas customers. Joint ventures between Chinese producers and overseas distributors can lock in demand in importing markets.
Emerging agricultural economies provide a second path. Dry and water-dispersible granule formats sold through village retailers and cooperatives can reach smallholders who buy in small lots. Improved adjuvants and low-residue formulations allow lower use rates and help suppliers meet tightening standards. Precision spraying tools and digital stewardship records let service providers charge for application quality rather than volume alone. Contract application services and cooperative bulk purchasing in Brazil and India offer further routes to scale for suppliers with the right formulation range. Online sales platforms and farmer financing programs reduce the cost of reaching buyers outside established dealer networks.
⮞In January 2026, China’s Ministry of Agriculture and Rural Affairs granted a production biosafety certificate to GG2 herbicide-tolerant corn. Commercial planting of the trait would extend glyphosate use into one of the world’s largest corn-growing areas.
Recent Developments:
-
In July 2026, Bayer announced that it would consolidate its U.S. glyphosate business into a distinct entity named Ruveon LLC, based in St. Louis. The entity covers pricing, production, logistics and sales for agricultural and industrial, turf and ornamental customers, and it gives the business a separate operating structure within the group.
-
In April 2026, Syngenta launched Virestina, a selective grass herbicide with the active ingredient metproxybicyclone for soybean and cotton, with first approval in Argentina. The product targets glyphosate-resistant and clethodim-resistant grasses and gives growers a new partner for programs that still rely on glyphosate.
-
In January 2026, Xingfa Chemicals Group reported thermal-process phosphoric acid capacity of 150,000 tonnes a year with a plan to reach 225,000 tonnes a year during 2026. The expansion strengthens control over a key raw material for glyphosate production and supports supply continuity for downstream customers.
Glyphosate Market Key Players:
-
Bayer
-
Syngenta
-
Albaugh
-
Nufarm
-
ADAMA
-
UPL
-
Zhejiang Xinan Chemical Industrial Group
-
Zhejiang Wynca Chemical
-
Sichuan Fuhua Tongda Agro-Chemical Technology
-
Jiangsu Yangnong Chemical
-
Nantong Jiangshan Agrochemical and Chemicals
-
Hubei Taiseng Chemical
-
Hebang Chemical
-
Xingfa Chemicals Group
Glyphosate Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.84 Billion |
| Market Size by 2035 | USD 15.03 Billion |
| CAGR | CAGR of 4.33% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Formulation (Liquid Formulations and Dry Formulations) • By Crop Type (Grains and Cereals, Commercial Crops, Pulses and Oilseeds, Fruits and Vegetables, and Other Crops) • By Application (Agriculture and Non-Agricultural) • By Distribution Channel (Direct Sales, Retail, and E-Commerce) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bayer, Syngenta, Albaugh, Nufarm, ADAMA, UPL, Zhejiang Xinan Chemical Industrial Group, Zhejiang Wynca Chemical, Sichuan Fuhua Tongda Agro-Chemical Technology, Jiangsu Yangnong Chemical, Nantong Jiangshan Agrochemical and Chemicals, Hubei Taiseng Chemical, Hebang Chemical, Xingfa Chemicals Group |

Frequently Asked Questions
Albaugh, Nufarm, ADAMA, UPL and Zhejiang Wynca Chemical are among the key players in the Glyphosate Market, among others.
Key opportunities include approvals of herbicide-tolerant crops in new countries, dry and granule formats for smallholder retail, and precision application and stewardship services that raise value per hectare.
The major growth factor is the spread of herbicide-tolerant crops and no-till farming, which make glyphosate the base layer of weed control programs for soybean, corn, cotton and canola.
The Liquid Formulations segment dominated the Glyphosate Market with approximately 74.00% share in 2025, as liquids mix easily, suit standard and precision sprayers, and move through established distribution.
Asia Pacific dominated the Glyphosate Market in 2025 with a 34.50% share, supported by large farmland, price-sensitive growers, expanding generic supply and a strong manufacturing base in China.
