
Heat Recovery Ventilation Market Report Scope & Overview:
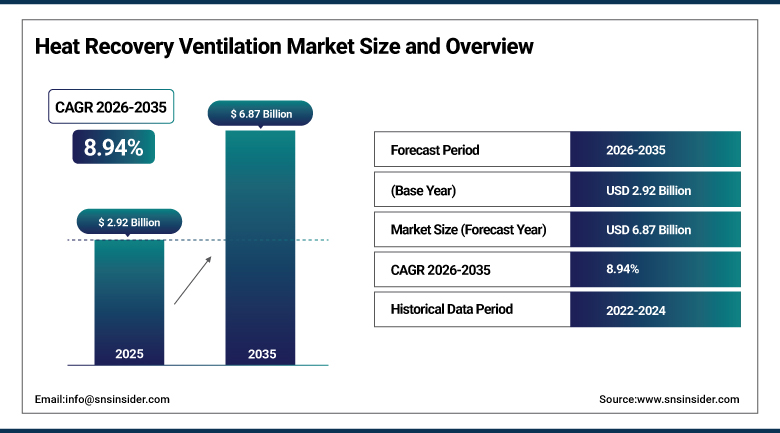
The Heat Recovery Ventilation Market was valued at USD 2.92 Billion in 2025 and is expected to reach USD 6.87 Billion by 2035, growing at a CAGR of 8.94% from 2026-2035.
Heat Recovery Ventilation market is on the path of expansion, where people are trying to improve the quality of indoor air and minimize energy consumption for heating and cooling of the building. Heat recovery ventilation units provide outdoor fresh air and exhaust indoor contaminated air while transferring heat energy from one airstream to another, which means that building will be able to recover a lot of energy, which would have been wasted otherwise. Since building envelope is being built tighter in accordance with energy building codes, mechanical ventilation with heat recovery has become mandatory in order to control indoor moisture, carbon dioxide, odors and other indoor contaminants. Building codes such as ASHRAE 62.2, International Energy Conservation Code, EU Energy Performance of Buildings Directive and Passive House requirements are pushing this technology into new and existing buildings. Higher consciousness regarding air contaminants and healthy buildings, as well as increasing number of green building certifications is also contributing to demand for such systems.
To Get more information Heat Recovery Ventilation Market - Request Free Sample Report
⮞Integrated commercial ventilation products came into focus following the announcement by FläktGroup in June 2026, where the company indicated the launch of its new generation of its product known as ReCooler R32, which integrates heating, ventilation, and air conditioning using low GWP refrigerants.
Heat Recovery Ventilation Market Trends
-
Rising adoption of high-efficiency counterflow heat exchangers recovering up to 90% of heat.
-
Growing integration of smart controls, Wi-Fi connectivity, and IAQ sensors in ventilation units.
-
Expanding use of EC motors to reduce fan energy consumption and noise.
-
Increasing demand for MERV 13 and HEPA-grade filtration in residential and commercial systems.
-
Rising adoption of heat recovery ventilation in Passive House and net-zero building projects.
-
Growing combination of heat recovery ventilation with heat pumps in all-electric buildings.
U.S. Heat Recovery Ventilation Market Outlook
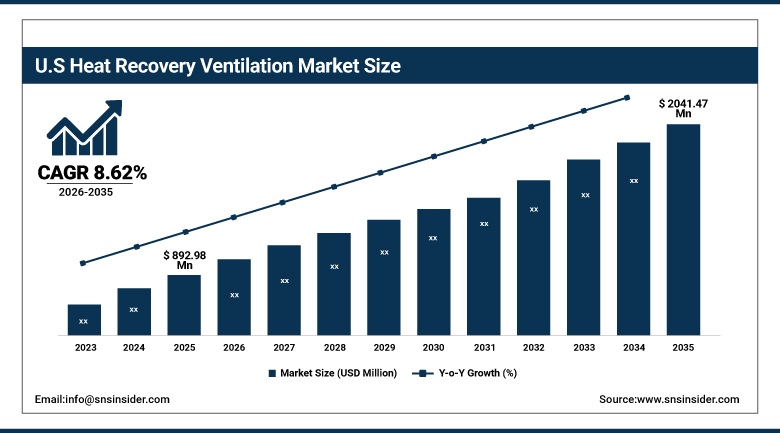
The U.S. Heat Recovery Ventilation Market was valued at USD 892.98 Million in 2025 and is expected to reach USD 2,041.47 Million by 2035, growing at a CAGR of 8.62% from 2026-2035.
The U.S. Heat Recovery Ventilation Market is flourishing due to increased energy efficiency codes in building construction, growing need for healthier indoor environment, and increasing number of high-performance houses and commercial constructions. International Energy Conservation Code and ASHRAE 62.2 ventilation standards mandate mechanical ventilation in more and more airtight houses, hence motivating the installation of heat and energy recovery ventilators. Cold climates in Northeast, Midwest, and Pacific Northwest are showing a great deal of adoption, while hot and humid climates prefer energy recovery ventilators along with moisture control. Major suppliers operating in the market in the country include Broan-NuTone, Panasonic, Zehnder America, Carrier, Lennox, Trane Technologies, and Johnson Controls. Federal tax credits for energy efficient home improvements, state and utility rebates, and green building certifications such as LEED, ENERGY STAR, and Passive House are helping in purchasing by builders, homeowners, and commercial property owners.
⮞The progress in residential ventilation technology in the United States came about in 2026 when Panasonic Eco Systems North America released its BalancedHome 210 energy recovery ventilator, which achieved 83 percent sensible recovery efficiency with MERV 13 filtration and Wi-Fi capability.
Heat Recovery Ventilation Market Segment Analysis
-
By Heat Exchanger Type, the Crossflow segment dominated the Heat Recovery Ventilation Market with approximately 45.12% share in 2025, while the Counterflow segment is the fastest growing with a CAGR of approximately 10.36%.
-
By Mounting Type, the Ceiling-Mounted segment dominated the Heat Recovery Ventilation Market with approximately 41.24% share in 2025, while the Wall-Mounted segment is the fastest growing with a CAGR of approximately 9.68%.
-
By Application, the Residential segment dominated the Heat Recovery Ventilation Market with approximately 52.86% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 9.84%.
-
By Distribution Channel, the Offline segment dominated the Heat Recovery Ventilation Market with approximately 68.42% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 11.06%.
By Heat Exchanger Type, Crossflow Dominates the Heat Recovery Ventilation Market and Counterflow Grows Fastest
Crossflow heat exchangers were dominant in 2025 because of their simplicity, affordability, and compactness which makes them suitable for installation in conventional residential and light commercial ventilation systems. Crossflow cores exchange heat through perpendicular airstreams with moderate efficiency, low pressure loss, and easy maintenance. Low cost and proven reliability have made crossflow units a preferred option for builders who operate under budget constraints and for replacement installations. The widespread availability of crossflow heat exchangers from major suppliers has continued to ensure dominance of this type in the heat recovery ventilation market.
The fastest growing heat exchanger type is counterflow due to increasing demand for highly efficient ventilation in energy-efficient homes, passive house projects, and net-zero buildings. Counterflow heat exchangers exchange heat by directing airstreams in opposite direction through a larger surface area resulting in heat recovery efficiencies of 90% or more. Major suppliers such as Zehnder utilize counterflow technology in their ComfoAir range of products in order to comply with strict energy standards. Growth in this segment has been driven by increasing performance requirements resulting from tightening building codes and reduced heating and cooling loads.
By Mounting Type, Ceiling-Mounted Dominates the Heat Recovery Ventilation Market and Wall-Mounted Grows Fastest
The Ceiling-Mounted units were dominant in 2025, as they take less floor space and can be easily incorporated into ducted distribution systems in residential homes, apartments, offices, and commercial buildings. Installation of the units can be done above the suspended ceilings or even in attics, ensuring that the equipment is not seen while also keeping the noise away from living and workspaces. These units have been extensively used in the commercial projects wherein the ventilation is distributed to different rooms. Space-saving and flexibility of the ceiling-mounted systems ensure that they are the largest mounting type segment in the market.
The Wall-Mounted units were the fastest-growing mounting type due to the increasing use of decentralized and room-based ventilation in the retrofit projects, apartments, and places where ductwork installations are difficult and expensive. Single-room and wall-mounted heat recovery units can be easily installed without any significant disturbance, which makes them a good choice for the renovation of existing residential homes, schools, and offices. The compact size of the units with quiet EC fans and smart control systems is making them more accepted by the users.
By Application, Residential Dominates the Heat Recovery Ventilation Market and Commercial Grows Fastest
Residential applications dominated the market in 2025 owing to the increasing installation of heat recovery ventilation in order to comply with energy codes, increase comfort, and preserve indoor air quality in airtight homes. The whole-house systems enable humidity control, condensation and mold prevention, removal of indoor contaminants while minimizing heat loss. In particular, cold-climate zones in North America and Europe have high adoption rates, and the trend toward balanced ventilation is growing in both single-family and multifamily constructions. Rising awareness about healthy homes keeps residential applications the largest segment in North America, Europe, and Asia Pacific.
The fastest growing segment is represented by commercial applications, including office buildings, educational facilities, healthcare facilities, hotels, and retail buildings that purchase ventilation systems to ensure indoor air quality compliance along with reduced energy expenses. Ventilation in commercial buildings requires large amounts of outside air, which makes heat recovery especially beneficial for minimizing heating and cooling loads. The green building certifications, sustainability goals of corporations, and post-COVID emphasis on healthy workplaces contribute to rising investments in this area. FläktGroup, Systemair, and Swegon keep developing their commercial product lines, and this is what drives the fastest growth among applications throughout the forecast period.
⮞In June 2026, Daikin Europe launched its VKM-JM decentralized fresh-air unit for commercial buildings, integrating heat recovery, humidity control, filtration and heating and cooling functions, with airflow capacities ranging from 500 to 1,000 m³/h
By Distribution Channel, Offline Dominates the Heat Recovery Ventilation Market and Online Grows Fastest
Offline distribution channels were dominating the market in 2025 due to the fact that most heat recovery ventilation systems are sold via HVAC distributors, wholesalers, contractors, and builders, who design, install, and commission the systems. Professional installation is crucial for proper design of the system, its airflow balancing, and compliance with all standards, which explains why traditional channels have the advantage. Offline sales also rely on contractor training programs and technical assistance from manufacturers, which further underlines the need for professional advice. Therefore, the role of expertise and installation services is likely to preserve the dominance of offline distribution channels, especially for commercial and new construction applications that require engineered design.
Online sales represent the most rapidly growing distribution channel since private homeowners, small-scale contractors, and facilities managers are more and more likely to do the research about the equipment and order the ventilation systems, replacement filters, and related accessories online. E-commerce represents an opportunity for more visibility of the products, their specifications, and comparison of prices. Replacement filters and small-scale decentralized systems are perfectly fit for online purchase. Growing efforts in digital marketing and expanding home improvement e-commerce contribute the most to this trend.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.62% |
|
Asia Pacific |
China |
38.24% |
|
Europe |
Germany |
24.86% |
|
Latin America |
Brazil |
41.38% |
|
Middle East & Africa |
United Arab Emirates |
29.64% |
North America Heat Recovery Ventilation Market Insights
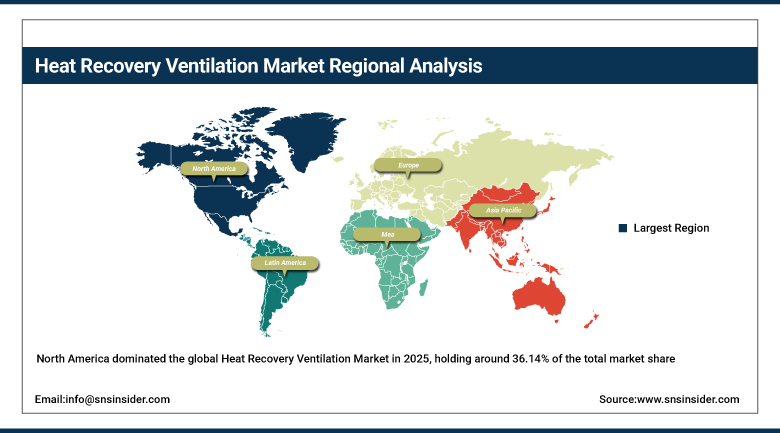
North America dominated the global Heat Recovery Ventilation Market in 2025, holding around 36.14% of the total market share, driven by stringent ventilation and indoor air quality regulations, prevalence of energy efficient HVAC systems, and installation of heat recovery ventilators in green buildings. Heat recovery is very useful in reducing heating bills because of cold climatic conditions prevailing in Canada and northern parts of the US. Major manufacturers like Broan-NuTone, Panasonic, Zehnder America, Carrier, Lennox, and Johnson Controls help maintain an extensive network of distribution and installation of the product across the region.
US will continue to drive regional consumption backed by energy codes, ASHRAE ventilation guidelines, federal tax credits, utility rebates, and increasing construction of high performance and all electric homes. Retrofits in school buildings, office spaces and healthcare facilities have been adding to commercial demand. Canada also contributes to strong demand owing to adoption of heat recovery ventilators in new homes for complying with ventilation regulations due to cold climatic conditions based on ENERGY STAR. Mexico provides small but increasing demand from commercial constructions.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Heat Recovery Ventilation Market Insights
Asia Pacific is the fastest-growing regional market, registering a CAGR of around 10.42% during 2026-2035 owing to rapid urbanization, high construction of residential and commercial buildings, increasing awareness about air pollution, and adoption of green building standards. Governments of China, Japan, South Korea, and India have been tightening building energy efficiency requirements and providing healthy indoor environment. Regional major players such as Panasonic, Daikin, Mitsubishi Electric, and LG Electronics manufacture a diverse range of heat and energy recovery ventilation products.
Regional demand is led by China due to high urban construction, strong emphasis on indoor air quality in polluted cities, and green buildings. Demand in Japan is driven by high maturity of energy recovery ventilation system in homes and offices along with building regulations for mechanical ventilation. South Korea is supporting demand via apartment construction and fine dust, whereas India is driving growth via commercial building construction and increasing awareness about air quality. Australia and New Zealand are increasingly adopting energy efficient homes, making Asia Pacific the fastest-growing market.
⮞In July 2025, Holtop reported delivering 12 rotary heat recovery air handling units for Wazhou Group's wind-power spindle bearing manufacturing project in Dalian, supporting industrial ventilation and energy recovery at the facility.
Europe Heat Recovery Ventilation Market Insights
Europe accounts for a considerable share of the global Heat Recovery Ventilation Market, thanks to some of the toughest building energy regulations in the world, which include the EU Energy Performance of Buildings Directive, near-zero energy building guidelines, and widespread application of Passive House standards. Mechanical ventilation with heat recovery systems are popular in newly built residential and commercial buildings in Northern and Western Europe. Top vendors like Zehnder, Systemair, FläktGroup, Swegon, Vent-Axia, Nilan, and Brink drive the maturity of this market and constant innovation in highly efficient counterflow and decentralized systems.
Germany drives regional demand as a pioneer in Passive House construction and energy-efficient building renovation, due to government funding schemes. The United Kingdom contributes through building regulations and high demand for MVHR systems in new builds, while Nordic nations drive penetration due to their cold climate and energy-efficient construction. France, the Netherlands, Belgium, and Austria drive demand through energy renovation schemes and healthy building concepts. EU commitment to building decarbonization and renovation is expected to drive Europe's steady market growth during the forecast period.
MEA & Latin America Heat Recovery Ventilation Market Insights
The Middle East & Africa market is witnessing growth due to investments by Gulf nations in sustainable buildings, smart cities, and green building certifications to lower energy consumption in hot climatic conditions. Energy recovery ventilation can help lower cooling loads in buildings that require high volumes of fresh air and is thus favored in offices, hotels, hospitals, and malls in the United Arab Emirates, Saudi Arabia, and Qatar. Saudi Arabia's Vision 2030 projects and green building regulations in Dubai are driving the demand for this product. The demand from Africa comes from South Africa owing to commercial construction and energy efficiency initiatives.
Latin America's market is growing because of commercial construction, green building certifications, and awareness about indoor air quality in the region. The key demand driver from Latin America is Brazil, which is driven by office, healthcare, and hospitality construction. Mexico's contribution comes from commercial and industrial construction due to nearshoring activity, while Chile and Argentina contribute demand from colder southern areas where heat recovery is very energy efficient. Colombia is adopting ventilation solutions in commercial buildings. Growth is anticipated on account of rising sustainability awareness.
Market Dynamics
Growth Drivers: Stricter Building Energy Codes and Rising Focus on Indoor Air Quality
Strengthening building energy codes will become the key impetus for the development of the Heat Recovery Ventilation Market, since governments tend to construct airtight building envelopes that would consume less energy on heating and cooling operations. In tight buildings, the lack of natural airflow makes mechanical ventilation essential for providing indoor environments with adequate ventilation. In case of heat recovery ventilation, it is possible to satisfy requirements of ventilation and to recover significant amounts of energy from exhaust airflow. Energy codes and standards, including the International Energy Conservation Code, ASHRAE 62.2, the EU Energy Performance of Buildings Directive, and Passive House standard, contribute to its widespread usage in both new constructions and renovations.
⮞In October 2025, Vent-Axia obtained Passivhaus certification for four models in its Sentinel Apex commercial mechanical ventilation with heat recovery range, including the HR06, HR10, HR15 and HR21, supporting high-efficiency building specifications.
The growing emphasis on the quality of indoor air quality is another key growth factor for the market. People usually spend most part of their lives indoors; therefore, they get more concerned about the health impact of carbon dioxide, volatile organic compounds, particulates, and pathogens on their well-being. The continuous supply of fresh air, which is provided by heat recovery ventilation systems, can also include filtration of pollutants such as pollen and dust through filters with high grade of purification.
Restraints: High Installation Costs and Limited Awareness in Emerging Markets
High costs of installation pose an important restraint to growth in the market, as heat recovery ventilation systems will require units, ducting, controls, and professional installation and commissioning. Installation in old buildings can be even more expensive and disruptive, as ducts need to be installed inside the walls and ceiling that have already been finished. Homeowners and building owners may find it hard to justify such high upfront costs, especially in regions with mild climate, where energy savings will not be significant enough. Regular maintenance, including filter changing and system cleaning, is another cost that discourages people from buying such systems.
Low awareness in emerging markets poses another important restraint to growth in the market, as builders, contractors, and consumers in developing countries may not know about heat recovery ventilation and its advantages. Building codes in these markets do not require installation of mechanical ventilation or energy recovery. Lack of professionals to install such systems properly may result in low-quality installation and poor system performance. Competition from traditional exhaust fans and natural ventilation, as well as improper sizing and balancing, can also restrain growth in the market.
Opportunities: Building Retrofits and Decarbonization and Smart and Integrated Ventilation Solutions
Building retrofits and decarbonization provide significant growth potential as governments in Europe, North America, and the Asia Pacific roll out major initiatives to enhance energy efficiency in existing buildings. Building renovations will generally involve better insulation and airtightness, which will necessitate the installation of mechanical ventilation with heat recovery. Decentralized and wall-mounted units will be especially suitable for building retrofit projects that make it difficult to install ductwork. Heating using heat pumps can also be integrated easily with mechanical ventilation with heat recovery.
⮞In July 2025, Vent-Axia launched the Lo-Carbon Sentinel Econiq-Cool in partnership with KERS, integrating mechanical ventilation with heat recovery and a Coolboost heat pump to provide renewable hot water and cooling for residential buildings.
Smart and integrated ventilation solutions present another growth opportunity, as manufacturers increasingly integrate heat recovery units with IAQ sensors, demand-controlled ventilation, Wi-Fi integration, and building management systems. This will ensure that ventilation is automatic and responsive to occupancy, carbon dioxide concentrations, and humidity, which will enhance comfort and energy savings. Ventilation units integrated with heat pumps and all-in-one heating, cooling, and ventilation systems will also become more popular. Growing construction activities and green building adoption in Asia Pacific, the Middle East, and Latin America provide good long-term growth prospects for the industry.
Recent Developments:
-
June 2026: Zehnder Group became a Champion Sponsor of the Passive House Accelerator, supporting high-performance building education and promoting its ComfoAir counterflow heat recovery ventilation systems that can recover upwards of 90% of exhaust air energy.
-
June 2026: Swegon merged its German HVAC units under a new name, consolidating its ventilation and indoor climate operations to strengthen its position in the European commercial ventilation market.
Heat Recovery Ventilation Market Key Players
-
Zehnder Group AG
-
Panasonic Holdings Corporation
-
Daikin Industries, Ltd.
-
Mitsubishi Electric Corporation
-
Systemair AB
-
FläktGroup
-
Swegon Group AB
-
Broan-NuTone LLC
-
Carrier Global Corporation
-
Johnson Controls International plc
-
Trane Technologies plc
-
Lennox International Inc.
-
LG Electronics Inc.
-
Vent-Axia (Volution Group plc)
-
Nilan A/S
-
Brink Climate Systems
-
Nortek Air Solutions
-
Greenheck Fan Corporation
-
RenewAire LLC
-
Ventilation Systems JSC (VENTS)
Heat Recovery Ventilation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.92 Billion |
| Market Size by 2035 | USD 6.87 Billion |
| CAGR | 8.94% from 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Heat Exchanger Type: Dominant – Crossflow (45.12% share in 2025); Fastest-Growing – Counterflow (CAGR 10.36%) • By Mounting Type: Dominant – Ceiling-Mounted (41.24% share in 2025); Fastest-Growing – Wall-Mounted (CAGR 9.68%) • By Application: Dominant – Residential (52.86% share in 2025); Fastest-Growing – Commercial (CAGR 9.84%) • By Distribution Channel: Dominant – Offline (68.42% share in 2025); Fastest-Growing – Online (CAGR 11.06%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Zehnder Group AG, Panasonic Holdings Corporation, Daikin Industries, Ltd., Mitsubishi Electric Corporation, Systemair AB, FläktGroup, Swegon Group AB, Broan-NuTone LLC, Carrier Global Corporation, Johnson Controls International plc, Trane Technologies plc, Lennox International Inc., LG Electronics Inc., Vent-Axia (Volution Group plc), Nilan A/S, Brink Climate Systems, Nortek Air Solutions, Greenheck Fan Corporation, RenewAire LLC, Ventilation Systems JSC (VENTS) |

Frequently Asked Questions
Key players include Zehnder Group AG, Panasonic Holdings Corporation, Daikin Industries, Ltd., Mitsubishi Electric Corporation, Systemair AB, FläktGroup, and Swegon Group AB, among other global ventilation manufacturers.
Building retrofits and decarbonization programs, along with smart and integrated ventilation solutions, represent the primary opportunities.
Growth is primarily driven by stricter building energy codes combined with a rising focus on indoor air quality.
By Application, Residential dominated the market with approximately 52.86% share in 2025, reflecting rising adoption in energy-efficient homes.
North America dominated the market with approximately 36.14% share in 2025, driven by strict ventilation codes and strong adoption of energy-efficient HVAC systems.
