
Heat Resistant Coatings Market Report Scope & Overview:
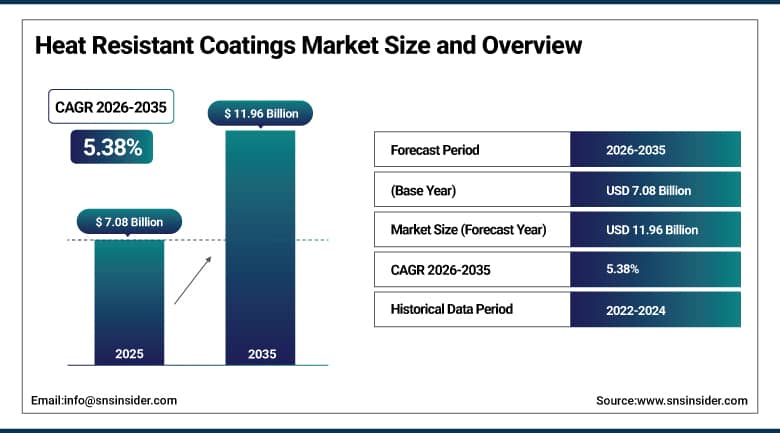
The Heat Resistant Coatings Market size was valued at USD 7.08 Billion in 2025 and is expected to reach USD 7.46 Billion in 2026, climbing to USD 11.96 Billion by 2035. The market is forecast to grow at a CAGR of 5.38% during 2026–2035. Heat resistant coatings are engineered films, based on silicone, epoxy, acrylic and ceramic binders, that protect metal and other surfaces exposed to sustained high temperatures. Demand rises with power generation, refining, vehicle production and fire safety requirements, since each of these relies on equipment that must resist heat, oxidation and corrosion.
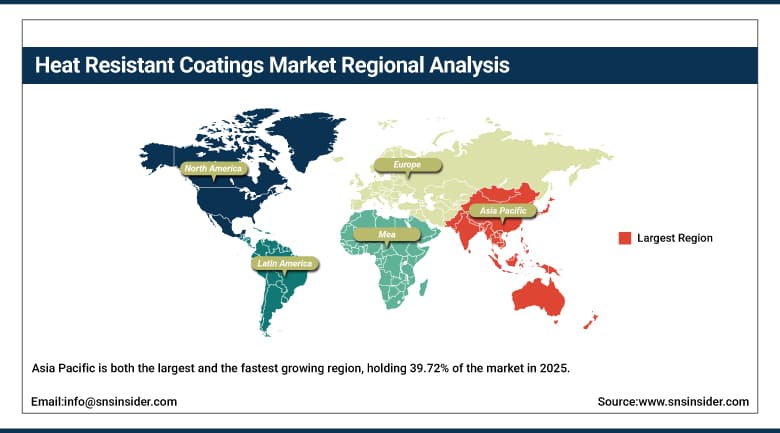
Asia Pacific accounted for the largest share of the market, at 39.72% in 2025, supported by large power, steel, chemical and vehicle industries in China, India, Japan and South Korea. North America follows, helped by refinery maintenance and rising electricity use, while Europe is shaped by strict chemical and building rules. Asia Pacific is also the fastest growing region, as new thermal power, petrochemical and battery manufacturing capacity enters operation across the region. Latin America and Middle East & Africa remain smaller regions, although refining and gas projects keep their pipelines active through the forecast period.
To Get More Information On Heat Resistant Coatings Market - Request Free Sample Report
Key Report Takeaways:
-
By resin type, silicone held a 33.74% share in 2025 and is also the fastest growing.
-
By technology, waterborne held a 37.62% share in 2025, while UV/EB-cured is the fastest growing.
-
By end-user industry, industrial equipment held a 30.84% share in 2025, while power generation is the fastest growing.
-
By region, Asia Pacific held a 39.72% share in 2025 and is also the fastest growing.
Market Trends and Insights:
Waterborne and powder systems are gaining ground in applications once dominated by solvent products. Improved binders now hold their film integrity at several hundred degrees Celsius, which lets plants cut solvent emissions without giving up thermal performance.
Coatings are being asked to do more than withstand heat. Thick-film insulating coatings, intumescent fire protection layers and ceramifying silicones now serve as thermal barriers on tanks, steel frames and battery housings, which widens the range of surfaces they protect.
Asset owners increasingly specify coating systems as part of corrosion-under-insulation programs. Instead of repainting at short intervals, operators select systems qualified for thermal cycling and long maintenance intervals, which favors suppliers with testing data and technical service.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Growing electricity demand and thermal power capacity |
+2.31% |
Global |
Long term (4 years or more) |
|
Oil, gas and petrochemical asset protection |
+1.52% |
Global |
Medium term (2 to 4 years) |
|
Battery and electric vehicle thermal safety |
+0.97% |
Asia Pacific and Europe |
Medium term (2 to 4 years) |
|
Stricter fire safety rules in construction |
+0.63% |
Europe and North America |
Short term (2 years or less) |
|
Advances in silicone, waterborne and powder systems |
+0.39% |
Global |
Medium term (2 to 4 years) |
Growing Electricity Demand and Thermal Power Capacity
Boilers, turbines, exhaust stacks and heat recovery units operate at high temperatures for years, and every new or refurbished plant needs coatings that resist oxidation and thermal cycling. In July 2026, the U.S. Energy Information Administration forecast record electricity consumption in both 2026 and 2027, with commercial demand overtaking residential demand for the first time. Data centers, electrification and industrial load growth keep gas-fired and coal-fired fleets busy, which raises the frequency of maintenance coating work. Utilities also retrofit older units to extend service life, and each retrofit specifies high temperature finishes for hot casings, ducts and flues.
Oil, Gas and Petrochemical Asset Protection
Refineries, gas plants and chemical sites contain miles of hot piping, vessels and flues that corrode quickly once insulation traps moisture. In May 2026, the International Energy Agency projected that global natural gas investment would rise by more than 10.00% to a ten year high, led by liquefied natural gas projects. New process trains need coating specifications for hot surfaces, and operators of older assets increasingly replace cladding with coating systems that tolerate cycling between ambient and elevated temperatures. Contractors also favor systems that cure quickly, since shutdown windows are short and delays carry a high cost for plant owners.
Battery and Electric Vehicle Thermal Safety
Traction batteries can release intense heat during cell failure, so housings, busbars and neighboring parts need barriers that keep a fire from spreading. The Ministry of Industry and Information Technology of China made GB 38031-2025 mandatory from 1 July 2026, requiring that a battery must not catch fire or explode after thermal runaway. Ceramifying silicones, intumescent layers and thick insulating powders help designers meet such limits, and they open a new application area beyond exhaust systems and engine components. Supply chains in China, South Korea and Europe are adopting these materials early, and automakers expect validated test data before approving each new pack design.
Stricter Fire Safety Rules in Construction
Building owners and engineers face growing pressure to show how structural steel and service installations behave in a fire. The revised Construction Products Regulation of the European Union became applicable on 8 January 2026, and it introduces a gradual update of product families, performance declarations and technical specifications. Intumescent and heat resistant coatings that carry tested fire ratings gain from clearer documentation requirements, especially where infrastructure and industrial buildings use exposed steel. Specifiers increasingly request environmental product declarations as well, which favors low emission waterborne products with transparent, independently verified documentation. Approval times shorten when ratings are well documented.
Advances in Silicone, Waterborne and Powder Systems
Binder chemistry is improving the performance range of coatings. Silicone resins, hybrid silicone epoxy systems and inorganic fillers allow films to survive higher temperatures while remaining flexible during heating and cooling. Waterborne and powder versions lower solvent emissions and wastage, which suits plants under air quality rules. Thicker single-pass films also shorten application time on large structures. These advances let applicators replace multi-coat schemes and give suppliers room to differentiate on cost in use. Suppliers that publish test data on adhesion, color stability and thermal shock help buyers compare options, and this transparency supports trade-up from basic aluminum paints to engineered systems.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Raw material and silicone price volatility |
-0.21% |
Global |
Medium term (2 to 4 years) |
|
PFAS and VOC regulation of coating chemistries |
-0.12% |
Europe and North America |
Medium term (2 to 4 years) |
|
Surface preparation and curing complexity |
-0.07% |
Global |
Long term (4 years or more) |
|
Competition from insulation and cladding systems |
-0.04% |
Global |
Short term (2 years or less) |
Raw Material and Silicone Price Volatility
Silicone resins, specialty pigments, aluminum flake and ceramic fillers make up a large share of formulation cost, and their prices move with energy, metal and feedstock markets. Producers pass part of each increase to coating makers, who then renegotiate with distributors and industrial customers that buy under annual contracts. Sudden swings make quoting harder for large maintenance projects, and some buyers switch to lower rated systems when budgets tighten, which slows the adoption of premium formulations. Smaller formulators with limited purchasing power feel these swings most, and they may delay product launches until input costs stabilize.
PFAS and VOC Regulation of Coating Chemistries
On 2 March 2026, the Committee for Risk Assessment of the European Chemicals Agency adopted its final opinion on the proposed restriction of PFAS, while the socio-economic committee is expected to finalize its opinion by the end of 2026. Fluoropolymer binders and additives have long supported non-stick and chemical resistant heat coatings, so suppliers must qualify alternatives. Reformulation requires testing, new approvals and sometimes lower performance, which adds cost and delays launches in regulated markets. Larger companies can fund this work, but smaller regional producers may withdraw products, which concentrates supply among a few global suppliers and may raise prices for buyers.
Surface Preparation and Curing Complexity
High temperature coatings rely on clean, profiled surfaces and specific cure schedules, and many sites lack the labor or shutdown time needed to follow them. Blasting standards, film thickness control and oven or in-service curing all affect results. When application falls short, films may blister, crack or lose adhesion, and owners must repeat the work. These risks make some operators cautious about new products and lengthen the approval cycle for unfamiliar systems. Training programs and certified applicator schemes help, but skilled labor remains scarce in several regions, and project schedules rarely leave room for corrections.
Competition from Insulation and Cladding Systems
Mineral wool, ceramic fiber blankets and metal cladding remain the default choice for many hot surfaces, because contractors know how to install them and specifications already exist. Coatings must prove that they offer equal thermal results and lower lifetime cost, which requires field trials and long reference lists. In sectors with conservative engineering practice, such as power utilities and refineries, change moves slowly, and coating suppliers must invest in technical service to shift habits. The lower upfront cost of traditional materials also keeps them attractive to contractors who bid on price alone and have little incentive to try new methods.
Heat Resistant Coatings Market Segment Analysis:
By Resin Type, Silicone Dominates Heat Resistant Coatings Market and Is Also Set to Register Fastest Growth.
Silicone resins hold a 33.74% share in 2025 because their silicon-oxygen backbone resists oxidation and ultraviolet exposure at temperatures where organic binders break down. Pigmented with aluminum flake or ceramic fillers, they coat stacks, exhaust systems, boilers and ovens, and they stay flexible through thermal cycling. Operators also value their long service life, which reduces repainting and downtime across process plants and power stations worldwide. Long field records in refineries and power stations give specifiers confidence in its performance.
The same chemistry supports the fastest growth, with a CAGR of 7.66% projected for 2026–2035. New hybrid silicone epoxy and ceramifying grades extend use to battery housings, insulating topcoats and corrosion-under-insulation systems, where earlier binders were too brittle. Suppliers keep widening temperature ratings and improving adhesion on hot, uneven steel, while applicators gain from simpler products that cure with moderate heat. Rising demand for fire resistant and heat shielding layers in electric vehicles also supports adoption by automakers.
By Technology, Waterborne Dominates Heat Resistant Coatings Market; UV/EB-Cured to Register Fastest Growth.
Waterborne products lead with a 37.62% share in 2025 as air quality rules and plant safety goals steer buyers away from solvent-heavy paints. Modern dispersions and silicone emulsions form films that tolerate moderate to high heat, dry quickly and clean up with water, which helps contractors working in occupied buildings, appliances and light industrial equipment. Low odor and simpler storage add appeal where flammable solvents are restricted. Regulatory pressure on emissions in Europe and North America reinforces this preference.
UV and electron beam curable coatings are expected to expand at a CAGR of 7.43% over 2026–2035. They cure within seconds under radiation, which saves energy and floor space on production lines for metal parts, electronics and automotive components. Formulators are tuning acrylate and hybrid systems to survive higher service temperatures, and equipment makers are developing lamps and shielding that handle three dimensional shapes. Faster cure also reduces inventory of semi-finished parts and cuts waste, which suits lean manufacturing.
By End-User Industry, Industrial Equipment Dominates Heat Resistant Coatings Market; Power Generation to Register Fastest Growth.
Industrial equipment accounts for a 30.84% share in 2025, covering furnaces, ovens, kilns, heat exchangers, compressors and process machinery that operate continuously at high temperature. Owners schedule coating work during planned shutdowns and favor products that reduce downtime, resist thermal shock and protect against chemical attack. Broad plant bases in steel, cement, glass and chemicals provide steady repeat demand for maintenance and original equipment finishes. Equipment makers also specify coatings during design, which locks in supply for years.
Power generation is projected to record the highest CAGR, at 9.37% from 2026 to 2035. New gas turbines, combined cycle plants, waste-to-energy units and refurbished coal fleets need coatings for casings, ducts and stacks, while data center growth strengthens baseload demand. Plant owners also seek systems that extend inspection intervals, so premium silicone and ceramic products gain preference in utility specifications. Turbine makers and engineering firms are testing coatings that handle high temperature scaling and condensation, supporting longer contracts.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
44.27% |
|
North America |
United States |
81.67% |
|
Europe |
Germany |
26.74% |
|
Middle East & Africa |
Saudi Arabia |
35.62% |
|
Latin America |
Brazil |
51.26% |
Asia Pacific Heat Resistant Coatings Market
Asia Pacific is both the largest and the fastest growing region, holding 39.72% of the market in 2025 and projected to register a CAGR of 7.70% over 2026–2035. China leads, supported by very large steel, chemical, power and vehicle industries and by local coating producers that supply industrial customers. Rapid expansion of battery plants also raises demand for thermal barrier coatings. India and Southeast Asia add new refineries, cement lines and power plants. Electricity demand growth across the region further supports new coating orders.
In India, the Central Electricity Authority reported in its March 2026 National Generation Adequacy Plan that about 86.44 GW of additional thermal capacity is needed by FY2035-36. Japan and South Korea contribute high specification products for electronics, automotive and shipbuilding, while Australia supplies mining and energy demand. Local production, large project pipelines and rising environmental standards should keep regional growth above the global rate. Government programs for industrial upgrades and energy security also encourage local producers to invest in plants that serve local and export customers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Heat Resistant Coatings Market
North America accounted for 26.45% of the market in 2025. The U.S. market was valued at USD 1.53 Billion in 2025 and is expected to register a CAGR of 5.08% during 2026–2035. Refineries, petrochemical plants, power stations and aerospace suppliers use high temperature coatings, and maintenance budgets for aging assets support recurring orders. Corrosion under insulation remains a major concern for operators of Gulf Coast facilities. Strong aerospace and defense programs add demand for specialty ceramic and silicone products used on engine and exhaust parts.
Canada adds demand through oil sands processing, mining and pipelines, and Mexico is covered within Latin America in this report. Rising electricity consumption and new gas-fired plants create further projects, while building owners specify fire protective coatings for steel. Environmental limits on volatile compounds push suppliers toward waterborne and powder products, and consolidation among distributors shapes how products reach contractors. Contractors increasingly bid on long term service agreements, which encourages asset owners to choose higher rated systems and to document performance across inspection cycles at their sites.
Europe Heat Resistant Coatings Market
Europe held 22.86% of the market in 2025. Germany leads the region, helped by a large machinery, chemical and automotive base that requires heat resistant finishes for engines, exhausts, ovens and process equipment. Chemical safety rules under REACH and strict emission limits steer suppliers toward low solvent and fluorine free formulations, and European coating makers invest heavily in research on durable binders. Energy efficiency rules for buildings and industry also encourage insulating coatings, and equipment makers in Baden-Württemberg and Bavaria specify heat resistant finishes for ovens and boilers.
France, the United Kingdom, Italy and Spain contribute through energy, aerospace and construction projects, while Nordic countries support offshore and marine demand. The energy transition adds work on biomass, waste-to-energy and hydrogen-ready plants. Building safety reforms raise interest in certified fire protective coatings, so the region remains a leading center for technical standards and product innovation. Universities and testing institutes partner with producers on new binders, while certification bodies provide recognized fire test results that support exports throughout Europe and into neighboring markets.
Middle East & Africa Heat Resistant Coatings Market
Middle East & Africa held 6.34% of the market in 2025. Saudi Arabia leads, with large refining, petrochemical and gas processing complexes that operate in hot, humid conditions and need coating systems for pipes, flues and vessels. The United Arab Emirates and Qatar add demand through liquefied natural gas and downstream expansion, and utilities in the Gulf invest in new power and desalination plants. Free zones and industrial cities in the Gulf attract new fabrication yards, which also need protective finishes for steelwork and equipment.
In Africa, South Africa and Egypt use heat resistant coatings in mining, metals and power generation, while new refineries in Nigeria and other producers create future demand. High ambient temperatures and salt exposure favor premium products with proven field performance. Dependence on imported materials and uneven maintenance budgets limit growth outside the major energy centers. Several governments are building local fabrication capacity and technical training, and these programs should gradually raise demand for certified applicators and higher rated and certified products.
Latin America Heat Resistant Coatings Market
Latin America accounted for 4.63% of the market in 2025. Brazil leads, with an established oil and gas sector, steel and pulp mills, and a strong industrial coatings producer base that serves refineries, power plants and equipment makers. Offshore platform maintenance and new gas infrastructure support recurring orders for high temperature and corrosion protection systems that tolerate salt laden air. Pulp, sugar and ethanol plants also operate boilers and dryers that need regular recoating, which broadens the customer base beyond energy.
Mexico adds demand through its refining, automotive and appliance industries, and Argentina benefits from shale gas development in the Vaca Muerta formation. Chile and Colombia contribute through mining and power. Currency swings and uneven public investment affect project timing, yet nearshoring and energy infrastructure plans are expected to sustain steady growth across the region over the forecast period. Local coating producers compete on price and delivery time, and multinational groups respond by adding technical service centers and distribution partnerships in major industrial cities.
Competitive Landscape:
The Heat Resistant Coatings Market is moderately consolidated. A small group of global paint and coatings groups, including PPG, AkzoNobel, Sherwin-Williams, Jotun and Hempel, supplies a large part of protective and high temperature products, while regional and specialty producers serve local industrial customers. Competition centers on temperature rating, adhesion, certified fire performance, technical service and the ability to support large maintenance programs.
Vendors follow several strategies. Leading groups launch products for corrosion under insulation, fire protection and battery safety, extend powder and waterborne ranges, and strengthen regional production close to energy and industrial clusters. Mergers, acquisitions of specialty businesses and approvals from certification bodies are also common.
Heat Resistant Coatings Market Industry Leaders:
1. PPG Industries: U.S. coatings group with a wide protective and industrial range.
2. AkzoNobel: Dutch coatings group with high temperature powder and protective lines.
3. The Sherwin-Williams Company: U.S. coatings maker with a Heat-Flex thermal range.
4. Jotun: Norwegian supplier of protective and fire protection coatings.
5. Hempel: Danish provider of protective coatings for process industries.
Companies Covered in this Report:
-
PPG Industries, Inc.
-
AkzoNobel N.V.
-
The Sherwin-Williams Company
-
Jotun A/S
-
Hempel A/S
-
Axalta Coating Systems Ltd.
-
KCC Corporation
-
Wacker Chemie AG
Recent Industry Developments:
-
November 2025: Jotun introduced Jotachar 1709 XT, an intumescent fire protection coating for oil, gas and petrochemical facilities.
-
January 2026: KCC developed a thick powder coating for secondary batteries and power devices that builds over 250 microns in a single pass.
-
February 2026: PPG introduced STEELGUARD 652, a water-based intumescent coating that protects interior structural steel for up to two hours.
-
June 2026: Sherwin-Williams launched Heat-Flex AEB, a thick-film thermal insulating coating for equipment operating up to 177 °C.
-
July 2026: Hempel launched Hempafire Optima 515, a waterborne fire protection coating rated up to 150 minutes.
-
August 2026: AkzoNobel shareholders approved an all-stock merger of equals with Axalta.
-
October 2026: Wacker showed ELASTOSIL CM 146 US A/B, a sprayable ceramifying silicone coating for battery barrier systems.
Scope and Research Methodology
This study estimates the Heat Resistant Coatings Market for 2025 as the base year and forecasts it through 2035. The scope covers coatings designed to protect surfaces exposed to sustained elevated temperatures, including silicone, epoxy, acrylic and other binder systems, in solvent-based, waterborne, powder and radiation-cured forms. Values are reported in USD at the point of sale to applicators, original equipment manufacturers and asset owners. Segmentation covers resin type, technology, end-user industry and region. Architectural paints and general anticorrosion coatings without a heat rating are excluded. Technical products sold only as insulation materials are not part of this study, and coatings are counted at the value of the finished film.
Secondary research included company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, procurement managers and technical specialists across the value chain. These inputs were used to validate adoption rates, pricing and the mix of resins, technologies and end uses in current projects. Interviews covered resin and pigment suppliers, coating manufacturers, distributors, applicators, plant engineers and specifiers, which allowed assumptions on temperature ratings, film thickness and maintenance cycles to be tested against field practice.
Market size was built from the bottom up using supplier revenue, industrial output and coating consumption per asset type, and was cross-checked from the top down against protective coatings demand and energy and manufacturing activity. Triangulation across these views fixed the base year value. Forecasts reflect energy investment, safety and chemical regulation, technology cost and macroeconomic conditions, and segment and regional shares were assigned from consumption patterns in each setting. An analyst quality review checked consistency before release. Growth rates for each segment were set so that the parts remain consistent with the whole, and the model was run under conservative, base and optimistic cases.
Heat Resistant Coatings Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.08 Billion |
| Market Size by 2035 | USD 11.96 Billion |
| CAGR | CAGR of 5.38% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Silicone, Epoxy, Acrylic, and Others) • By Technology (Waterborne, Solventborne, Powder, and UV/EB-Cured) • By End-User Industry (Industrial Equipment, Building and Construction, Automotive and Transportation, Oil and Gas, Power Generation, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AkzoNobel N.V., The Sherwin-Williams Company, Jotun A/S, Hempel A/S, Axalta Coating Systems Ltd., KCC Corporation, Wacker Chemie AG |

Frequently Asked Questions
The market was valued at USD 7.08 Billion in 2025 and is projected to reach USD 11.96 Billion by 2035, growing at a CAGR of 5.38% during 2026–2035.
Asia Pacific leads, with a 39.72% share in 2025, supported by large power and industrial output.
Asia Pacific is also expected to grow fastest, at a CAGR of 7.70% during 2026–2035, led by China and India.
Silicone, waterborne and industrial equipment lead, while silicone, UV/EB-cured and power generation grow fastest within their segments.
PPG Industries, AkzoNobel, The Sherwin-Williams Company, Jotun and Hempel lead.
Raw material price swings, PFAS and VOC rules, application complexity and competition from insulation systems restrain faster adoption.
