
Calcium Carbonate Market Report Scope & Overview:
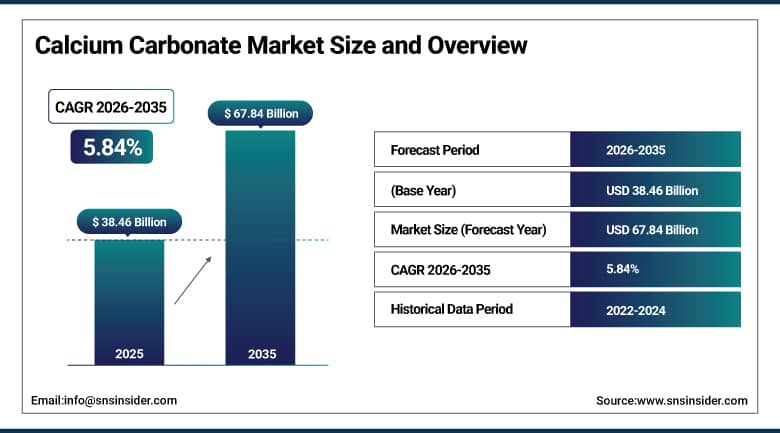
The Calcium Carbonate Market size was valued at USD 38.46 Billion in 2025 and is expected to reach USD 40.71 Billion in 2026, rising to USD 67.84 Billion by 2035. The market is forecast to expand at a CAGR of 5.84% during 2026–2035. Calcium carbonate is produced by grinding limestone, marble or chalk, or by precipitating it from lime, and it serves as a filler, pigment, neutralizer and mineral supplement. Buyers in packaging, plastics, paint, construction and food use it to lower cost and improve whiteness, stiffness and flow. It is widely traded.
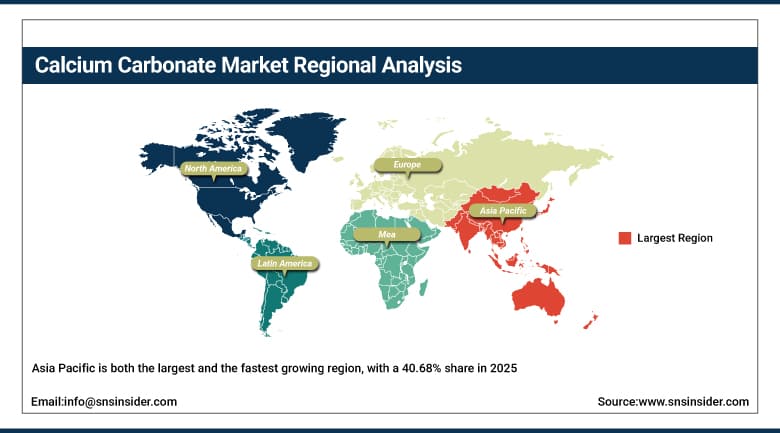
Asia Pacific accounted for the largest share of the market, at 40.68% in 2025, because of its large paper, plastics and construction industries and its abundant limestone deposits. North America follows, supported by building activity and a large base of specialty compounders. Asia Pacific is also the fastest growing region, as China, India and Southeast Asia add cement, housing, packaging and compounding capacity. Europe contributes through paper, paint and specialty plastics demand, while Latin America and Middle East & Africa add volume from farm liming, mining and housing projects over the forecast period.
To Get More Information On Calcium Carbonate Market - Request Free Sample Report
Key Report Takeaways
-
By product, ground calcium carbonate held 73.12% in 2025, while precipitated calcium carbonate is the fastest growing.
-
By end use, paper held 30.42% in 2025, while building and construction is the fastest growing.
-
By grade, industrial grade held 87.36% in 2025, while pharmaceutical grade is the fastest growing.
-
By surface treatment, uncoated products held 68.74% in 2025, while coated products are the fastest growing.
-
By particle size, the 1 to 5 micron range held 46.28% in 2025, while products below 1 micron are the fastest growing.
-
By region, Asia Pacific held 40.68% in 2025 and is also the fastest growing.
Market Trends and Insights
Producers are shifting output from commodity paper fillers toward plastics, coatings, adhesives and food-grade lines where margins are higher. Surface-treated and ultrafine grades allow compounders to raise filler loadings while preserving impact strength and surface finish.
Satellite precipitated calcium carbonate plants built beside customer mills, and grinding plants located near construction demand, are cutting freight costs. Producers also invest in electrified kilns, waste heat recovery and carbon capture to lower the emissions of lime-based processes.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Construction and infrastructure activity |
+3.46% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Plastics, masterbatch and packaging compounding |
+2.52% |
Global |
Medium term (2 to 4 years) |
|
Paperboard and packaging coatings |
+1.74% |
Asia Pacific |
Short term (2 years or less) |
|
Food, pharmaceutical and supplement use |
+1.05% |
Global |
Long term (4 years or more) |
|
Agriculture and environmental applications |
+0.54% |
Asia Pacific and Latin America |
Long term (4 years or more) |
Construction and Infrastructure Activity
Calcium carbonate enters buildings through cement and mortar additives, paints, sealants, flooring, pipe and profile compounds. The United States Geological Survey estimated in January 2026 that the country produced about 1.50 Billion tons of crushed stone in 2025, of which limestone and dolomite made up roughly 70.00%. Housing programs in India and Southeast Asia, road and utility projects in the Middle East and renovation waves in Europe keep this demand steady, and each project consumes large volumes of locally ground product.
Plastics, Masterbatch and Packaging Compounding
Compounders add calcium carbonate to polyolefin films, pipes, cables, injection molded parts and masterbatch to reduce resin use and improve stiffness and heat resistance. Resin price swings make fillers attractive, since a higher loading can hold down cost without losing performance. Lightweight packaging, breathable films for hygiene products and stone paper all rely on fine coated grades, and growth in flexible packaging in Asia and Latin America adds volume for producers. Compounders also value the stable supply of locally produced mineral fillers.
Paperboard and Packaging Coatings
Although writing and printing paper is declining, board and packaging grades keep growing with e-commerce and food delivery. Precipitated and ground calcium carbonate provide brightness, opacity and smooth printing surfaces at a lower cost than titanium dioxide and kaolin. Mills in Asia are adding board machines and coating lines, and satellite plants located beside these mills supply slurry directly, which secures long-term contracts for producers. Packaging brands also ask for recycled content and lower coat weights, which favors efficient mineral pigments over costly alternatives.
Food, Pharmaceutical and Supplement Use
High-purity calcium carbonate is a common calcium source in dietary supplements, antacids, tablets, fortified foods and plant-based drinks, and it acts as an excipient and a whitening agent. Aging populations, concern about bone health and the spread of fortified products raise demand for food and pharmaceutical grades. These grades sell at prices several times those of industrial material, and strict quality standards protect suppliers that hold certifications. Plant-based drinks and infant nutrition products also use it as a calcium additive.
Agriculture and Environmental Applications
Ground limestone raises soil pH, supplies calcium and improves nutrient uptake, and it is applied widely on acidic soils in Brazil, India and Southeast Asia. Water treatment plants use it to neutralize acidity and stabilize hardness, and power plants and industrial users apply limestone to remove sulfur compounds from flue gases. Stricter environmental rules and national soil programs create a base of steady purchases. Rising attention to soil health and organic farming programs adds further demand, and coated granules improve spreading on large farms.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Decline in graphic paper demand |
-1.43% |
Europe and North America |
Medium term (2 to 4 years) |
|
High freight, energy and compliance costs |
-1.08% |
Global |
Short term (2 years or less) |
|
Competition from alternative fillers |
-0.64% |
Global |
Medium term (2 to 4 years) |
|
Quarry permitting and environmental scrutiny |
-0.32% |
Europe and North America |
Long term (4 years or more) |
Decline in Graphic Paper Demand
Paper has been the largest single user of calcium carbonate, so falling use of printing and writing paper cuts demand for fillers and coatings. The Confederation of European Paper Industries reported on 2 July 2026 that European paper and board production fell 1.60% to 77.40 Million tonnes in 2025, with graphic papers down 7.30%. Mill closures remove satellite plants and contracts, and producers must redirect capacity toward packaging, plastics and other markets. Digital media continues to accelerate this structural shift.
High Freight, Energy and Compliance Costs
Calcium carbonate is a low-value, heavy product, so transport can account for a large part of the delivered price. Grinding, drying and calcining need electricity and fuel, and precipitated grades depend on lime kilns that emit carbon dioxide. Rising energy prices and carbon charges in Europe squeeze margins, while dust and noise rules add compliance costs at plants, which limits the distance over which producers can compete. Producers respond with local plants and long-term freight contracts, but cost pressures remain a constant challenge.
Competition from Alternative Fillers
Talc, kaolin, silica, aluminum trihydrate, barium sulfate and recycled glass powder can replace calcium carbonate in some uses, and designers sometimes choose them for stiffness, flame retardancy or optical effects. Titanium dioxide remains the benchmark white pigment, and new extender technologies aim to cut its use. Producers must prove value through consistent particle size, brightness and surface treatment, which requires investment in laboratories and technical service. Customers often run trials before switching, and this slows the loss of share to substitutes.
Quarry Permitting and Environmental Scrutiny
New quarries and expansions need permits that cover land use, water, dust, blasting and habitat protection, and local opposition can delay approvals for years. Reserve quality also varies, and high-brightness deposits are limited. Rehabilitation obligations raise long-term costs, and companies must report emissions and water use in more detail. These pressures slow the opening of new capacity in mature regions. Producers respond by investing in rehabilitation, community programs and early engagement with regulators, but approvals still take longer than in the past.
Calcium Carbonate Market Segment Analysis
By Surface Treatment, Uncoated Products Dominate Calcium Carbonate Market; Coated Products to Register Fastest Growth.
Uncoated products hold a 68.74% share in 2025 because paper, construction and many paint uses need no special treatment. Slurry shipped to mills and dry powder sold into mortar or paint disperse well without coatings, and skipping the treatment step lowers cost. Buyers in cost-sensitive applications therefore choose standard grades from nearby plants in large volumes. Local producers have a freight advantage in these markets, and their products meet national standards with minimal processing. Switching suppliers is rare.
Coated products are expected to grow at a CAGR of 7.43% from 2026 to 2035. A thin layer of stearic acid or similar agents makes the particle compatible with polymers, improving dispersion, moisture resistance and processing speed. Compounders of polyolefin films, cables and automotive parts value these properties, and coated grades allow higher filler loading without brittleness. Producers invest in coating lines that apply the treatment during milling, which improves consistency. Tailored grades for cables command higher prices.
By Product, Ground Calcium Carbonate Dominates Calcium Carbonate Market; Precipitated Calcium Carbonate to Register Fastest Growth.
Ground calcium carbonate accounts for 73.12% of the market in 2025 because it is made by crushing and milling natural limestone or marble, which is cheaper than chemical precipitation. Plants can be built close to quarries and customers, and the product suits construction materials, paints, plastics and paper. Wide availability of deposits and low capital needs allow many regional producers to compete. Producers also vary the grind to meet different specifications of paper, paint and plastic buyers. Quality is monitored.
Precipitated calcium carbonate is projected to grow at a CAGR of 6.58% during 2026–2035. Its particle size, shape and purity can be controlled, which gives higher brightness and better performance in coated paper, sealants, inks, food and pharmaceutical products. Satellite plants beside customer mills reduce freight, and demand for ultrafine grades in plastics and adhesives is widening the use of the product. Newer plants add on-site slurry storage and classification equipment, which improves consistency for large coating buyers.
By End Use, Paper Dominates Calcium Carbonate Market; Building and Construction to Register Fastest Growth.
Paper holds a 30.42% share in 2025 because mills use calcium carbonate as a filler inside the sheet and as a pigment in coatings. It replaces more expensive fibers and brightens the surface, and alkaline papermaking has made it the standard mineral choice. Packaging and board mills are the main buyers today, and long supply contracts tie producers to individual mills. Stable demand from board and tissue mills offsets weaker graphic paper, and Asian capacity additions support further purchases.
Building and construction is expected to expand at a CAGR of 7.12% from 2026 to 2035. Calcium carbonate is used in cement mixes, mortars, tile adhesives, paints, joint compounds, flooring and plastic pipes. Urban housing programs and renovation in Asia, the Middle East and Africa raise volumes, and manufacturers are using the mineral to partly replace cement clinker and reduce emissions. Green building codes and low carbon cement standards in several countries encourage this shift and support steady order growth.
By Grade, Industrial Grade Dominates Calcium Carbonate Market; Pharmaceutical Grade to Register Fastest Growth.
Industrial grade accounts for 87.36% of the market in 2025 because most volume goes to paper, plastics, paints and construction, which do not require food or drug certification. These applications value consistent whiteness, particle size and moisture control rather than extreme purity. Large integrated producers supply them in bulk by truck, rail and ship, and price competition is shaped by freight and energy. Long-term supply agreements with mills and manufacturers give producers stable volumes across business cycles. Contracts renew regularly.
Pharmaceutical grade is projected to grow at a CAGR of 8.94% during 2026–2035. Tablet makers use it as a calcium source and excipient, and supplement brands rely on it for bone health products. Compliance with pharmacopoeia standards, heavy metal limits and good manufacturing practice allows premium pricing, and aging populations in Asia and Europe add steady demand. Regulatory audits and certifications create entry barriers, and major suppliers invest in dedicated lines to separate pharmaceutical output from industrial production.
By Particle Size, 1 to 5 Micron Dominates Calcium Carbonate Market; Below 1 Micron to Register Fastest Growth.
Products in the 1 to 5 micron range account for 46.28% of the market in 2025 because they balance cost, opacity and flow in paper, paints, sealants and plastics. Milling to this size is efficient, and the powder handles well in compounding and coating lines. Most standard paper and paint specifications fall in this window, which makes it the volume workhorse of the industry. Large paper and paint customers specify it in contracts, which gives suppliers stable volumes.
Products below 1 micron are projected to grow at a CAGR of 8.41% over 2026–2035. Ultrafine and nano-scale particles improve gloss, tensile strength, impact resistance and printability, and they are used in high-end coatings, inks, adhesives and engineered plastics. Producers are adding fine grinding and classifying lines, and precipitation routes offer tight size control for demanding customers. Research on surface chemistry and dispersion technology helps producers keep particles from clumping, which is essential for fine particles in polymers.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.52% |
|
Europe |
Germany |
22.41% |
|
Asia Pacific |
China |
49.37% |
|
Middle East & Africa |
Saudi Arabia |
28.64% |
|
Latin America |
Brazil |
43.28% |
Asia Pacific Calcium Carbonate Market
Asia Pacific is both the largest and the fastest growing region, with a 40.68% share in 2025 and a projected CAGR of 6.89% over 2026–2035. China leads the region, with huge paper, plastics, cement and paint industries and abundant limestone reserves. Local producers dominate ground grades, and large precipitated plants sit beside board mills. Government plans for housing and rural development keep construction material demand strong, and regional investment in packaging board capacity supports precipitated output at satellite plants beside new mills.
India is expanding housing, packaging and compounding capacity, and its producers are investing in finer grades. Japan and South Korea supply high-purity and ultrafine products for electronics, food and pharmaceutical customers, while Vietnam, Indonesia and Thailand add paper and plastics volume. Government programs for infrastructure and agriculture keep regional growth above the global rate. Australia exports high-grade limestone and marble products, and Malaysia and the Philippines are growing plastics and packaging markets that consume coated grades in steadily rising volumes across the wider region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Calcium Carbonate Market
North America held 25.41% of the market in 2025, led by the United States. The U.S. market was valued at USD 8.46 Billion in 2025 and is expected to register a CAGR of 5.37% during 2026–2035. Large quarry networks, a strong building products industry and a mature base of compounders and coating makers support steady demand. The country has deep limestone reserves in Pennsylvania, Texas, Florida and the Midwest, and producers operate grinding plants and slurry terminals that serve paper, plastics and building product makers.
Canada contributes through paper, plastics and construction, and Mexico is counted in Latin America although it is closely linked through trade. Producers in the region focus on high-brightness grades, specialty coated products and satellite plants, and rising use of recycled content and lightweight packaging gives compounders reasons to raise filler loadings. Specialty compounders in the Great Lakes and the Southeast buy coated grades for automotive and packaging parts, and distributors provide technical support to smaller paint, adhesive and sealant manufacturers across the continent.
Europe Calcium Carbonate Market
Europe accounted for 20.57% of the market in 2025, with Germany as the leading country. The region has long-established mineral producers, high-quality marble and chalk deposits and strong technical service for paper, paint and plastics customers. Demand is stable in construction chemicals and specialty plastics, while paper volumes are shrinking. Large paper and board mills remain customers, but producers are shifting capacity toward plastics, coatings and construction chemicals, and they invest in energy efficiency to cope with high electricity and carbon prices.
France, Italy, Spain, the United Kingdom and the Nordic countries are important markets. Italy and Norway supply high-whiteness marble products, and Finland is a key source for paper-grade material. Carbon pricing and environmental rules push producers toward electrified processes, efficient logistics and products that lower the footprint of customers. Recycled content rules for packaging and rising use of mineral-filled plastics in automotive interiors and pipes create new openings, while distributors in the region supply small and mid-sized formulators with technical guidance.
Middle East & Africa Calcium Carbonate Market
Middle East & Africa held 7.15% of the market in 2025. Saudi Arabia and the United Arab Emirates lead regional demand, where large construction programs, cement plants and paint makers consume ground limestone. Local deposits and growing investment in plastics and packaging support local output and exports to neighboring markets. Cement producers, tile makers and paint companies buy locally ground material, and new industrial zones create demand for fillers in plastics, adhesives and building chemicals across the wider Gulf region and North Africa.
Turkey, Egypt, Iran and Oman have large limestone and marble industries, and South Africa and Morocco are the more active markets in Africa. Housing shortages, urbanization and agricultural liming needs support long-term growth, although limited rail links and power constraints raise costs for producers away from the coast. Partnerships with international groups bring technology for fine grinding and surface treatment, and investment in industrial minerals as part of national diversification plans is expected to lift output and exports of processed material.
Latin America Calcium Carbonate Market
Latin America accounted for 6.19% of the market in 2025, with Brazil as the leading country. Brazil has large paper, pulp, plastics and agricultural industries, and ground limestone is applied widely on farmland to correct soil acidity. Mexico is the second major market, supported by construction, paint and plastic manufacturing tied to regional trade. Sugar cane, soybean and coffee growers apply large volumes of ground limestone, and paint makers in São Paulo and Mexico City supply regional building markets. Housing programs add steady demand.
Argentina, Chile and Colombia add demand from mining, construction and food processing. Import costs and currency swings affect pricing, and logistics over long distances raise delivered costs. Regional producers are expanding grinding capacity close to demand centers, and mills are exploring satellite precipitated plants for packaging board. Brazilian mills producing pulp, board and tissue are among the largest in the world, and they create a base for satellite precipitated plants, while Peru and Chile add demand from mining and fertilizer use.
Competitive Landscape
The Calcium Carbonate Market is fragmented. A few global mineral groups operate quarries, grinding plants and precipitation sites on several continents, while many regional producers serve local construction, agricultural and plastics buyers. Competition rests on deposit quality, freight cost, technical service and the ability to supply consistent brightness and particle size.
Vendors pursue capacity additions, satellite plants, coated and ultrafine grades, and efficiency programs. Acquisitions of regional grinding plants and distribution partnerships are also used to widen local reach.
Calcium Carbonate Market Industry Leaders
1. Minerals Technologies: U.S. mineral group with a large precipitated calcium carbonate network.
2. Huber: U.S. maker of ground and treated calcium carbonate for coatings and plastics.
3. Carmeuse: Belgian-based producer of lime and limestone products.
4. Sibelco: Belgian supplier of industrial minerals.
5. Nordkalk: Finland-based producer of limestone products.
Companies Covered in this Report
-
Minerals Technologies
-
Huber
-
Carmeuse
-
Sibelco
-
Nordkalk
-
Mississippi Lime Company
Recent Industry Developments
-
May 2025: Nordkalk announced it was strengthening its operations in the north.
-
May 2025: Mississippi Lime Company broke ground on a dolomitic lime operation in Bonne Terre, Missouri.
-
May 2026: Carmeuse announced an agreement to deploy autonomous hauling across its truck fleet at its Drummond Island quarry in Michigan.
-
June 2026: Huber Specialty Minerals expanded calcium carbonate distribution into 11 southeastern U.S. states through a distributor.
-
July 2026: Sibelco announced plans to separate its Jundu joint venture in Brazil.
Scope and Research Methodology
This study estimates the Calcium Carbonate Market for 2025 as the base year and forecasts it through 2035. The scope covers ground and precipitated calcium carbonate supplied as powder, granules or slurry for paper, plastics, paints, construction, adhesives, food, pharmaceutical and agricultural uses. Values are reported in USD at the point of sale by producers to industrial and commercial buyers. Quicklime, hydrated lime and crushed stone sold as aggregate are outside the scope. Segmentation covers product, end use, grade, surface treatment, particle size and region, and both ground and precipitated output are included. All values are rounded to two decimals. Recycled and by-product sources are also excluded.
Secondary research included company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, mill managers, compounders and distributors across the value chain. These inputs were used to validate volumes, pricing and the share of ground and precipitated grades. Interviews covered quarry operators, plant managers, mill buyers, compounders and distributors, which allowed assumptions on pricing, grade mix and freight cost to be tested against practice.
Market size was built from the bottom up using producer revenue, plant capacity and tonnage data, and was cross-checked from the top down against paper, plastics, paint and construction output. Triangulation across these views fixed the base year value. Forecasts consider energy and freight cost, industrial output, building activity and macroeconomic conditions, and segment and regional shares were assigned from adoption patterns in each setting. An analyst quality review checked consistency before release. The forecast was run under conservative, base and optimistic cases, and growth rates for each segment were set so that the parts remain consistent with the whole. Estimates are reviewed periodically as new data becomes available.
Calcium Carbonate Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 38.46 Billion |
| Market Size by 2035 | USD 67.84 Billion |
| CAGR | CAGR of 5.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Ground Calcium Carbonate and Precipitated Calcium Carbonate) • By End Use (Paper, Plastics, Paints and Coatings, Building and Construction, Adhesives and Sealants, and Others) • By Grade (Industrial, Food, and Pharmaceutical) • By Surface Treatment (Uncoated and Coated) • By Particle Size (Above 5 Micron, 1 to 5 Micron, and Below 1 Micron) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Minerals Technologies, Huber, Carmeuse, Sibelco, Nordkalk, Mississippi Lime Company |

Frequently Asked Questions
The Calcium Carbonate Market was valued at USD 38.46 Billion in 2025 and is projected to reach USD 67.84 Billion by 2035, growing at a CAGR of 5.84% during 2026–2035.
Asia Pacific leads, with a 40.68% share in 2025, and is also expected to grow fastest, at a CAGR of 6.89% during 2026–2035.
Ground carbonate, paper, industrial grade, uncoated products and the 1 to 5 micron range lead, while precipitated carbonate, construction, pharmaceutical grade, coated products and submicron grades grow fastest.
Construction activity, plastics compounding, paperboard coatings, and food and pharmaceutical use drive demand.
Minerals Technologies, Huber, Carmeuse, Sibelco and Nordkalk lead, along with Mississippi Lime Company.
