
Stratospheric UAV Payload Technology Market Report Scope & Overview:
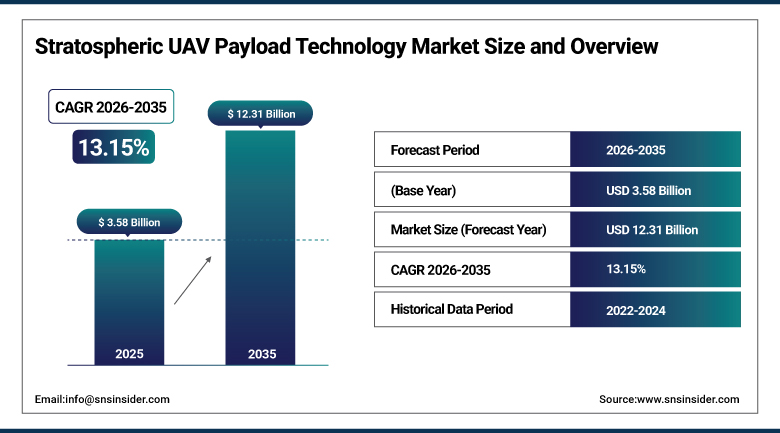
The Stratospheric UAV Payload Technology Market was valued at USD 3.58 Billion in 2025 and is expected to reach USD 12.31 Billion by 2035, growing at a CAGR of 13.15% from 2026-2035.
The Stratospheric UAV Payload Technology Market will be influenced by the increased need for persistent and high-altitude surveillance and communication that can work over weather and air traffic and are less costly than the satellite-based system. Governments and defense agencies have been continuously investing in high-altitude and long-endurance unmanned aerial vehicles, which come fitted with modern payloads used in surveillance, intelligence and reconnaissance missions. Increased need for internal and external security and border monitoring requirements has continued to stimulate the need. The market is fueled by improved solar and battery technologies that increase the endurance of the stratospheric aircraft to remain active for weeks and even months without a break.
Incorporation of artificial intelligence and machine learning in the payload system, and the regulatory changes that have been put in place, to enable the operation of stratospheric platforms, will open up new applications for the market.
In June 2024, AALTO, the Airbus-majority-owned subsidiary developing the Zephyr High Altitude Platform Station, secured a USD 100 million investment from a Japanese consortium led by NTT DOCOMO and Space Compass Corporation, aimed at deploying Zephyr for Asia-Pacific broadband connectivity services by 2026.
To Get more information Stratospheric UAV Payload Technology Market - Request Free Sample Report
Stratospheric UAV Payload Technology Market Trends
- Growing integration of artificial intelligence and machine learning into stratospheric payload systems.
- Rising commercial interest in stratospheric platforms for broadband connectivity and Earth observation services.
- Continued advancement of solar-powered and battery technology extending stratospheric flight endurance.
- Increasing government investment in high-altitude platforms for border surveillance and security applications.
- Expanding regulatory frameworks facilitating commercial deployment of stratospheric unmanned platforms.
U.S. Stratospheric UAV Payload Technology Market Outlook
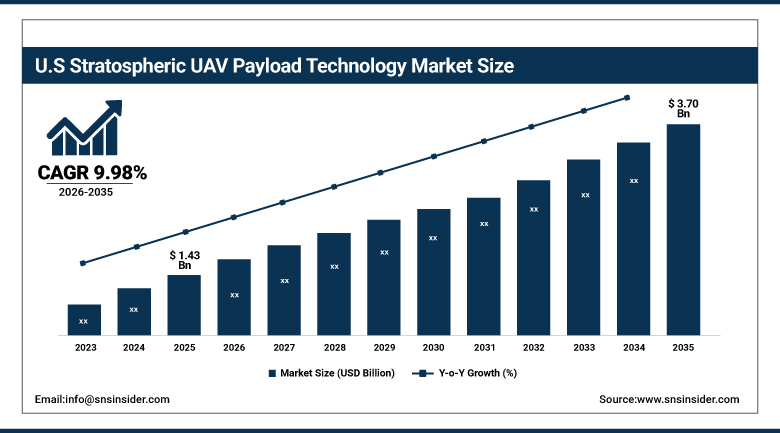
The U.S. Stratospheric UAV Payload Technology Market was valued at USD 1.43 Billion in 2025 and is expected to reach USD 3.70 Billion by 2035, growing at a CAGR of 9.98% from 2026-2035.
U.S. growth of Stratospheric UAV Payload Technology Market will remain supported by continuous defense modernization expenditures, increasing government initiatives with regards to investment in high-altitude platforms, and presence of prominent aerospace and defense contractors in the country that are working on the development of payload technology. In terms of the demand drivers, it should be noted that domestic demand will benefit from military and defense applications still being the biggest segment, and commercial applications being the fastest growing segment. The latter will be driven by innovations and entry into the market through the increase in funding initiatives for commercial platform developers.
In August 2024, AeroVironment's Sunglider stratospheric platform, developed under the formerly independent HAPSMobile joint venture with SoftBank Corp., conducted further trials with the U.S. Department of Defense in New Mexico.
Stratospheric UAV Payload Technology Market Segment Analysis
- By Payload Type, the Surveillance segment dominated the Stratospheric UAV Payload Technology Market with approximately 44.50% share in 2025, while the Scientific & Research segment is the fastest growing with a CAGR of approximately 15.90%.
- By Technology, the Electro-Optical segment dominated the Stratospheric UAV Payload Technology Market with approximately 52.50% share in 2025, while the Radar segment is the fastest growing with a CAGR of approximately 15.80%.
- By Application, the Military and Defense segment dominated the Stratospheric UAV Payload Technology Market with approximately 58.50% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 16.90%.
By Payload Type, Surveillance dominates and Scientific & Research grows fastest
Surveillance payloads constitute the leading segment among stratospheric UAV payload technology market share and this is because of the continuous government and defense sector’s spending in the area of persistent ISR capabilities, which stratospheric platforms have been able to offer uniquely with their high endurance and wide-area capabilities. The increasing border security and internal security issues across the world that are contributing to the increasing demands for continuous high altitude monitoring are supporting this segment.
Scientific & Research payloads constitute the most rapidly growing segment in the stratospheric UAV payload technology market due to increasing interest in space research, atmospheric research, and high altitude environmental data gathering requirements, where the stratospheric platforms offer better value proposition compared to satellites in some cases. The scientific payload segment is oriented towards unique sensor suites for climate and atmosphere research purposes.
By Technology, Electro-Optical dominates and Radar grows fastest
Electro-Optical technology remains the dominant technology segment within the Stratospheric UAV Payload Technology Market, reflecting its widespread use in high-resolution imaging and surveillance applications that form the core mission profile for most stratospheric platforms currently in operation. This segment benefits from continued advancement in steerable, high-resolution optical camera systems capable of providing very high resolution imagery and near-real-time video from the stratosphere.
Radar technology is emerging as the fastest-growing technology segment, driven by its ability to provide all-weather, day-and-night surveillance capability that complements the visibility limitations of purely optical systems. This segment focuses on lightweight, power-efficient radar systems suited to the strict weight and power constraints of solar-powered stratospheric platforms, positioning radar technology to capture growing demand from defense customers requiring continuous, weather-independent monitoring capability.
By Application, Military and Defense dominates and Commercial grows fastest
Military & Defense applications account for the majority of applications segments of the Stratospheric UAV Payload Technology Market, thanks to heavy government investments in platforms for intelligence, surveillance, and reconnaissance operations aimed at securing national defense purposes. This market segment is enjoying stable defense spending on modernizing their military capacities and platforms due to the increasing interest in the persistent surveillance capability of stratospheric platforms besides other satellite and aircraft reconnaissance platforms.
Commercial applications represent one of the most rapidly growing application segments of the market owing to the increased interest in the use of stratospheric platforms for broadband services, Earth observation services, and extending telecommunication networks. This market segment will be characterized by the establishment of a regulatory framework and financial support programs which will make way for new commercial platform providers and thereby capturing an increasing portion of total demand of the market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.50% |
|
Asia Pacific |
China |
44.60% |
|
Europe |
United Kingdom |
32.80% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
Israel |
41.20% |
North America Stratospheric UAV Payload Technology Market Insights
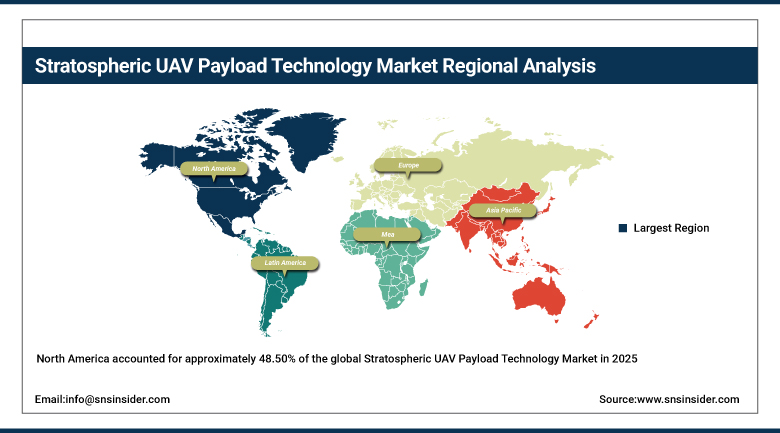
North America accounted for approximately 48.50% of the global Stratospheric UAV Payload Technology Market in 2025, driven by strong military, defense, and commercial investment in high-altitude unmanned aerial vehicles. The United States accounts for the substantial majority of regional demand, reflecting both its large defense budget and its concentration of leading aerospace and defense contractors developing stratospheric platform and payload technology.
Canada contributes additional regional demand through its participation in North American defense research and development programs. Continued technological advancements in payload systems, particularly the integration of artificial intelligence and machine learning transforming operational efficiencies, further reinforce North America's position as the largest regional market for stratospheric UAV payload technology.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Stratospheric UAV Payload Technology Market Insights
Asia Pacific is anticipated to witness the highest CAGR of approximately 13.50% among all regional segments of the Stratospheric UAV Payload Technology Market throughout the forecast period from 2026 to 2035 on account of increasing defense modernization projects and enhanced border security concerns in the region. The largest contributor among all countries within the region will be China owing to massive government spending on both military and commercial high-altitude platforms.
The contribution from Japan will be in the form of commercial telecom activities that look to experiment with stratospheric connectivity services, and India will have a growing contribution in terms of increasing defense modernization activities that drive the demand for stratospheric UAV payload technology.
Europe Stratospheric UAV Payload Technology Market Insights
Europe represents a significant regional market for stratospheric UAV payload technology, anchored by the United Kingdom's substantial defense aerospace industry and its role as the origin of several leading stratospheric platform development programs. The United Kingdom's share within the European market reflects its established defense procurement programs and home-market presence of major stratospheric platform developers.
Germany and France contribute additional regional demand, supported by established aerospace manufacturing sectors and growing investment in high-altitude platform development. Continued European Union investment in defense modernization and border security capability supports steady regional demand for stratospheric payload technology.
MEA & Latin America Stratospheric UAV Payload Technology Market Insights
The Middle East & Africa remains an increasing area of strategic significance, with demand arising from such countries as Israel, which has already developed a robust ecosystem for the development of defense aerospace and unmanned aerial system technologies for its own use as well as exports. Markets within the Gulf Cooperation Council add to the regional demand because of increased military spending and interest in persistent surveillance capabilities.
In Latin America, the Stratospheric UAV Payload Technology Market is dominated by Brazil, which represents the major share of the regional demand owing to its developed aerospace industry and increased interest in applications related to border and environmental surveillance. Growth of domestic surveillance and monitoring capabilities is gradually leading to increased regional demand.
Market Dynamics
Growth Drivers: Persistent Surveillance Demand and Defense Modernization
The increasing need for border surveillance and increased security threats both internally and externally have been identified as the key driver of growth of the Stratospheric UAV Payload Technology Market because governments and defense authorities keep on making investments in high-altitude platforms with sophisticated payloads for surveillance purposes.
On one hand, the innovations in the field of payload systems increase the capacity of stratospheric platforms in terms of surveillance, communication, and research operations. On the other hand, improvements in the technology of batteries, solar power, and fuel cells are the other key driver of demand because they increase the operational capacity of stratospheric platforms and their payload capacities.
Restraints: High Development Costs and Technical Reliability Challenges
High development and testing costs associated with stratospheric platform and payload technology represent a significant restraint on the Stratospheric UAV Payload Technology Market, as manufacturers must validate systems capable of sustained operation in extreme high-altitude environmental conditions over extended flight durations. This dynamic is compounded by the technical reliability challenges inherent in maintaining continuous operation at altitudes above 60,000 feet, where unusual weather patterns and equipment stress can result in platform loss.
Limited regulatory clarity in certain jurisdictions restricts the pace of commercial stratospheric platform deployment, as airspace management and safety certification frameworks continue evolving alongside the underlying technology. Continued technical complexity in achieving multi-month continuous flight endurance adds further uncertainty to commercial service timelines across the industry.
Opportunities: Commercial Connectivity Expansion and AI Integration
Continued expansion of commercial stratospheric connectivity services presents a substantial growth opportunity for the Stratospheric UAV Payload Technology Market, as platform developers pursue broadband connectivity and Earth observation applications that extend beyond traditional military surveillance use cases. Developers that can demonstrate validated, commercially viable stratospheric platform performance are well positioned to capture share as telecommunications companies continue exploring stratospheric infrastructure as a complement to satellite and terrestrial networks.
Rising integration of artificial intelligence and machine learning into payload systems presents a longer-term opportunity for suppliers to extend platform capabilities beyond basic surveillance and communication into more sophisticated, autonomous data analysis functions. As military modernization initiatives continue advancing globally, suppliers with established payload technology development capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2026: Airbus and Kawasaki Heavy Industries signed an MoU to explore a Japanese anti-submarine warfare variant of the Eurodrone, including integration of Japanese sensors and mission payloads. The Eurodrone is designed for long-endurance missions with payload capacity of up to 2.3 tonnes.
- 2026: Airbus showcased its expanded uncrewed systems portfolio at ILA Berlin, including the long-endurance Eurodrone and other advanced UAS platforms, highlighting increasing development of high-payload, autonomous, and multi-mission capabilities for defense applications.
- 2023: BAE Systems' PHASA-35 stratospheric platform, developed via the company's FalconWorks unit, achieved a 24-hour stratospheric flight at 66,000 feet from Spaceport America, New Mexico, with a stated target of operational availability from 2026 or 2027.
Stratospheric UAV Payload Technology Market Key Players are:
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- RTX Corporation
- Airbus SE
- The Boeing Company
- General Atomics Aeronautical Systems, Inc.
- Thales Group
- Leonardo S.p.A.
- AeroVironment, Inc.
- Elbit Systems Ltd.
- BAE Systems plc
- L3Harris Technologies, Inc.
- QinetiQ Group plc
- Textron Inc.
- Israel Aerospace Industries Ltd.
- Saab AB
- Kratos Defense & Security Solutions, Inc.
- World View Enterprises, Inc.
- Aerostar International, Inc.
- Sierra Nevada Corporation
Stratospheric UAV Payload Technology Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.58 Billion |
| Market Size by 2035 | USD 12.31 Billion |
| CAGR | CAGR of 13.15% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Payload Type (Surveillance, Communication, Navigation, Imaging, Scientific & Research, Others) • By Technology (Electro-Optical, Infrared, Radar, LIDAR, Others) • By Application (Military and Defense, Commercial, Environmental Monitoring, Telecommunications, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lockheed Martin Corporation; Northrop Grumman Corporation; RTX Corporation; Airbus SE; The Boeing Company; General Atomics Aeronautical Systems, Inc.; Thales Group; Leonardo S.p.A.; AeroVironment, Inc.; Elbit Systems Ltd.; BAE Systems plc; L3Harris Technologies, Inc.; QinetiQ Group plc; Textron Inc.; Israel Aerospace Industries Ltd.; Saab AB; Kratos Defense & Security Solutions, Inc.; World View Enterprises, Inc.; Aerostar International, Inc.; Sierra Nevada Corporation. |
Frequently Asked Questions
Leading companies in the Stratospheric UAV Payload Technology Market include Lockheed Martin, Northrop Grumman, RTX Corporation, Airbus, and Boeing, among others.
Key opportunities include continued expansion of commercial stratospheric connectivity services extending beyond military surveillance use cases, and rising integration of artificial intelligence and machine learning into payload systems.
Rising demand for border surveillance and growing internal and external security risks, combined with advancements in solar-powered and battery technology extending flight endurance, is the major factor driving market growth.
The Military and Defense segment dominated the Stratospheric UAV Payload Technology Market with approximately 58.50% share in 2025.
North America dominated the Stratospheric UAV Payload Technology Market in 2025 with approximately 48.50% share, driven by strong military, defense, and commercial investment in high-altitude UAVs, led by the United States.
