
Digital Battlefield Market Report Scope & Overview:
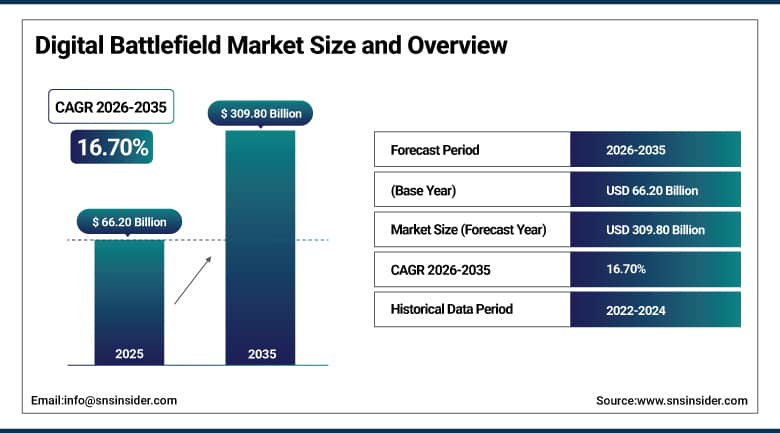
The Digital Battlefield Market was valued at USD 66.20 Billion in 2025 and is expected to reach USD 309.80 Billion by 2035, growing at a CAGR of 16.70% from 2026-2035.
The Digital Battlefield Market growth is being driven primarily by escalating geopolitical tensions and the urgent military requirement for persistent, real-time situational awareness, enhanced threat identification, and unified command structures capable of enabling swift, coordinated action across joint land, naval, air, and space forces. Solutions including live digital maps, augmented reality displays for troops, and networked radios help military units move together and react quickly amid difficult operational environments, while command and control systems serve as the crucial operational backbone where intelligence, surveillance, and reconnaissance data is consumed and translated into action. Growing importance of cyber warfare, alongside advancements in unmanned vehicles and secure communication technologies, continues to reinforce digital battlefield investment as nations worldwide accelerate defense modernization programs. Digital system integration increased 37% across 49 major military programs between 2020 and 2024, while autonomous surveillance usage rose 29% and AI-enabled decision systems improved situational awareness by 31%, reflecting the rapid pace of digital transformation across modern military operations.
On December 19, 2025, the U.S. Space Development Agency awarded USD 3.5 billion in contracts to Lockheed Martin, Northrop Grumman, L3Harris Technologies, and Rocket Lab USA to build 72 satellites for the Tranche 3 Tracking Layer of the Proliferated Warfighter Space Architecture, the largest deal to date for the agency's low-Earth-orbit missile warning and tracking constellation.
To Get More Information On Digital Battlefield Market - Request Free Sample Report
Digital Battlefield Market Trends
-
Rising integration of AI-enabled decision-support systems to improve real-time battlefield situational awareness.
-
Growing investment in proliferated low-Earth-orbit satellite constellations for resilient missile warning and tracking.
-
Expanding adoption of digital twin simulation technology for mission planning and equipment maintenance forecasting.
-
Increasing deployment of autonomous surveillance systems across land, naval, and airborne military platforms.
-
Rising defense budget allocation toward cyber warfare capability given intensifying digital threat landscapes.
-
Growing preference among defense ministries for outcome-based contracts bundling installation, cybersecurity, and uptime guarantees.
U.S. Digital Battlefield Market Outlook
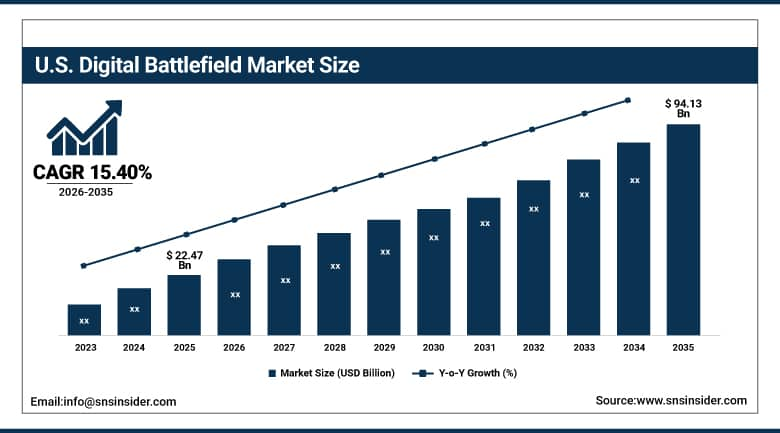
The U.S. Digital Battlefield Market was valued at USD 22.47 Billion in 2025 and is expected to reach USD 94.13 Billion by 2035, growing at a CAGR of 15.40% from 2026-2035.
Growth of the U.S. Digital Battlefield Market will still be driven by the status of the country as one of the biggest spenders on defense in the world, where there is continued investment in the modernization of digital command and control infrastructure from the air, space, and the ground. Contractors in the country's defense industry will continue competing for large contracts from the Department of Defense and Space Development Agency, which are aimed at missile warning, tracking and defense systems, showing continuous support from the government on digitization of the battlefield in the next generation. Continuous development of AI-powered analytics in order to process data collected by high-resolution sensors will keep driving investments in advanced processing and decision-making capabilities by contractors, with the military industry responsible for more than 60% of global ISR activities.
As part of the Space Development Agency's USD 3.5 billion Tranche 3 Tracking Layer award announced in December 2025, L3Harris Technologies secured a contract worth up to USD 843 million to build and deliver 18 satellites carrying missile warning and tracking sensors, extending the company's role across every missile tracking tranche within the Proliferated Warfighter Space Architecture to date.
Digital Battlefield Market Segment Analysis
-
By Component, the Hardware segment dominated the Digital Battlefield Market with approximately 52.60% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 19.80%.
-
By Technology, the Artificial Intelligence segment dominated the Digital Battlefield Market with approximately 30.20% share in 2025, while the Digital Twin Simulation segment is the fastest growing with a CAGR of approximately 19.40%.
-
By Platform, the Land segment dominated the Digital Battlefield Market with approximately 40.60% share in 2025, while the Space segment is the fastest growing with a CAGR of approximately 18.60%.
-
By Application, the Command & Control Systems segment dominated the Digital Battlefield Market with approximately 34.60% share in 2025, while the Cyber Warfare segment is the fastest growing with a CAGR of approximately 19.60%.
By Component, Hardware Dominates the Digital Battlefield Market and Services Grows Fastest
The hardware segment dominates the market as sensors, communication gear, hardy computing systems, and satellite systems constitute the essential physical components that form the base of all digital battlefield solutions, right from soldier-mounted gear to space-based surveillance systems. The high cost incurred in developing military hardware, capable of operating in severe environmental conditions, continues to contribute to the dominance of the hardware segment in the digital battlefield market.
Services constitute the fastest-growing category as the defense ministries favor outcome-oriented deals in which the integrators offer system integration along with guaranteeing the security and uptime of the hardware and software instead of purchasing hardware and software individually. The fast-growing complexities involved in the integration of digital battlefield systems in joint force operations are contributing to the growth of the services segment.
By Technology, Artificial Intelligence Dominates the Digital Battlefield Market and Digital Twin Simulation Grows Fastest
Artificial intelligence dominates the market because AI and big-data analytics capability increasingly underlies modern battlefield decision-support systems, processing high-resolution sensor data from ISR platforms to deliver actionable intelligence faster than traditional manual analysis methods allow. Rising military investment in AI-enabled situational awareness and autonomous system coordination continues to reinforce artificial intelligence's position as the largest and most strategically prioritized technology category.
Digital twin simulation is the fastest-growing technology as defense organizations increasingly adopt virtual replicas of equipment, systems, and operational environments to support mission planning, predictive maintenance, and training without the cost and risk of live-exercise testing. This growth is reinforced by digital twin technology's ability to accelerate equipment lifecycle management and reduce unplanned maintenance downtime across increasingly complex, sensor-integrated military platforms.
By Platform, Land Dominates the Digital Battlefield Market and Space Grows Fastest
Land platforms dominate the market because ground force digitization, spanning soldier-worn systems, vehicle-mounted communication equipment, and command post infrastructure, represents the most widely deployed and numerous category of digital battlefield technology across global militaries. The scale of ground force personnel and equipment relative to naval, airborne, and space assets continues to sustain land's position as the largest platform category for digital battlefield investment.
Space is the fastest-growing platform as proliferated low-Earth-orbit satellite constellations increasingly deliver resilient global missile warning, tracking, and communication coverage that ground and airborne-based systems cannot match in coverage or survivability. This growth is reinforced by major government satellite procurement programs, including the U.S. Space Development Agency's expanding Tranche-based tracking layer contracts, which continue to scale the number of operational military satellites at an accelerating pace.
By Application, Command & Control Systems Dominates the Digital Battlefield Market and Cyber Warfare Grows Fastest
Command and control systems lead the market due to their critical role in acting as the backbone through which information collected from intelligence, surveillance, and reconnaissance can be processed and acted upon to coordinate military efforts, thus having unified command within joint force operations. This important role of command and control systems in practically every modern-day military operation makes them continue to hold the title of the leading application market within digital battlefields.
Cyber warfare is the fastest growing functional application due to the increasing importance of digital resilience within every military domain, as there is an increased trend towards attacks aimed at the same digital technologies that enable coordination within modern-day battlefields. This increase is fueled by higher defense budget allocation for offensive and defensive cyber capabilities, which are essential for achieving digital dominance in battlefields.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.60% |
|
Europe |
Germany |
28.60% |
|
Asia Pacific |
China |
38.60% |
|
Middle East & Africa |
Israel |
32.60% |
|
Latin America |
Brazil |
27.80% |
North America Digital Battlefield Market Insights
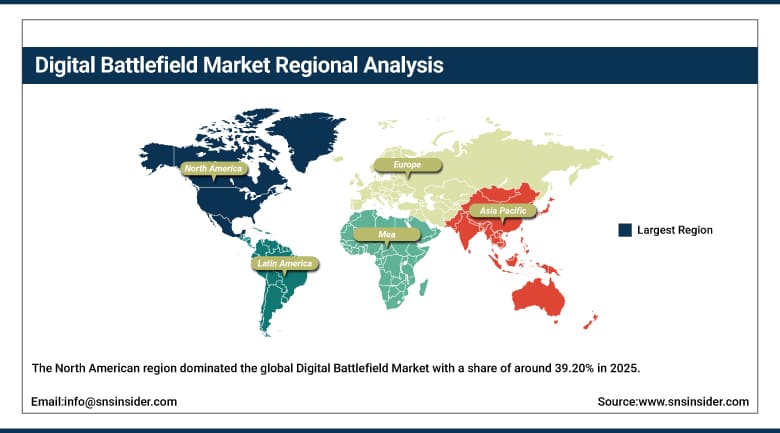
The North American region dominated the global Digital Battlefield Market with a share of around 39.20% in 2025, which makes it the biggest regional market, driven by huge defense budgets of the US aimed at updating the airborne and space-based systems and fastening the adoption of AI-powered data analytics tools for analyzing high-resolution imagery.
The US belongs to one of the biggest countries in terms of defense spending in the world and maintains significant investments in modern command, control, and surveillance systems in all the military areas.
The Canadian country contributes to additional demand from the increasing regional modernization initiatives. Further large government contracts, such as those of the Space Development Agency in terms of growing satellite tranches, are anticipated to maintain the North American leadership during the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Digital Battlefield Market Insights
Europe holds a substantial market presence in the global Digital Battlefield Market, owing to the strong military industrial base of Germany and increased modernization investments being made in the defense sector of the region, considering the rising geopolitical tensions. The members of NATO alliance are continuously making progress in their interoperability initiatives, such as agreements made recently by the defense firms of the region to provide integrated electronic warfare and naval defense capabilities to the naval forces of the allies.
There has been a constant contribution from France, UK, and Italy in terms of demand growth in the region on account of investment being made in digital battlefield technology in the command and control, cyber warfare, and naval defense modernization initiatives.
Asia Pacific Digital Battlefield Market Insights
The Asia Pacific region is the fastest growing market, witnessing a CAGR of about 19.20% during 2026-2035, owing to increased spending on connected force solutions in countries such as China, India, Japan, and South Korea amid increasing security concerns in the region. Significant investments in defense modernization made by China will continue to boost the market growth in the region.
India, Japan, and South Korea will be making significant contributions to the growth due to their continued investments in the digitization of their forces, including artificial intelligence and satellite-based surveillance systems. These factors along with increasing defense budget and defense modernization efforts will help retain the position of the fastest growing market for the region throughout the forecast period.
MEA & Latin America Digital Battlefield Market Insights
The Middle East & Africa market is anchored by Israel's advanced defense technology sector, where leading domestic contractors continue to develop and export sophisticated electronic warfare, missile defense, and command and control systems, reinforced by recent agreements to deliver integrated maritime electronic warfare capability for NATO allied naval forces. Rising regional security tensions continue to sustain substantial defense modernization investment across the broader Middle East.
Latin America's market is led by Brazil, where gradual defense modernization investment continues to expand digital battlefield capability across the country's armed forces. Regional governments across the broader Latin America market continue to invest cautiously in digital command and surveillance infrastructure, with adoption remaining concentrated among larger, better-resourced militaries.
Market Dynamics
Growth Drivers: Geopolitical Tensions and Real-Time Situational Awareness Requirements
Escalating geopolitical tensions represent the primary driver of Digital Battlefield Market growth, as militaries worldwide accelerate defense modernization programs to maintain persistent, real-time situational awareness and enhanced threat identification capability across increasingly contested operational domains. The urgent military requirement for unified command structures capable of enabling swift, coordinated action across joint land, naval, air, and space forces continues to sustain sustained government investment independent of broader economic cycles.
Growing importance of cyber warfare and advancements in unmanned vehicle and communication technologies represent a second major growth driver, as militaries increasingly recognize that digital battlefield superiority depends on both offensive and defensive capability across the networks connecting sensors, command systems, and combat platforms. Rising autonomous surveillance and AI-enabled decision-support adoption continues to reinforce this trend, extending digital battlefield investment across an increasingly comprehensive range of military technology categories.
Restraints: Stringent Regulations and Data Security Concerns
Stringent government regulations and policies related to defense technology procurement, exports, and international technology transfers constitute a real restriction on the market growth because the companies have to go through the lengthy process of approval in order to provide their new digital battlefield technologies to allied countries. This lengthy approval process may affect program timelines and reduce the speed of the deployment of advanced technologies within the allies’ military units.
Data security and privacy issues constitute another restriction, since the introduction of the new digital battlefield technologies increases the attack surface that can be used by enemies for conducting attacks. This creates an ongoing necessity of cybersecurity measures that add cost and complexity to modern military systems compared to traditional military systems.
Opportunities: Space-Based Infrastructure Expansion and AI-Enabled Decision Support
Continued expansion of proliferated low-Earth-orbit satellite constellations represents a substantial opportunity, as government space agencies continue to scale missile warning, tracking, and communication satellite programs at an accelerating pace. Contractors that can deliver reliable, cost-effective satellite production at scale are positioned to capture sustained, multi-tranche government investment as space-based digital battlefield infrastructure continues to expand.
Continued integration of AI-enabled decision-support systems offers a further avenue for growth, as militaries increasingly seek to process expanding volumes of sensor and intelligence data faster than human analysts can manage manually. Contractors that can demonstrate reliable, combat-tested AI decision-support capability are well positioned to capture demand from defense ministries prioritizing information-advantage capability across all military domains.
Recent Developments:
-
In March 2025, RAFAEL and Elbit Systems agreed to deliver an Integrated Maritime Electronic Warfare Self-Protection kit for NATO frigates, strengthening allied naval electronic warfare capability.
-
On December 19, 2025, Lockheed Martin was awarded a contract worth up to USD 1.1 billion as part of the Space Development Agency's Tranche 3 Tracking Layer program, to provide 18 satellites carrying missile warning, tracking, and defense sensors.
-
On December 19, 2025, Rocket Lab USA secured a contract worth up to USD 805 million as part of the Space Development Agency's Tranche 3 Tracking Layer program, marking the company's first contract for developing missile warning and tracking satellites.
-
On December 19, 2025, Northrop Grumman was awarded a contract worth up to USD 784 million as part of the Space Development Agency's Tranche 3 Tracking Layer program, extending its role across the agency's proliferated satellite architecture.
Digital Battlefield Market Key Players
-
Lockheed Martin Corporation
-
RTX Corporation
-
Northrop Grumman Corporation
-
BAE Systems plc
-
Thales Group
-
Airbus SE
-
AeroVironment, Inc.
-
Elbit Systems Ltd.
-
General Dynamics Corporation
-
L3Harris Technologies, Inc.
-
Leonardo S.p.A.
-
Rafael Advanced Defense Systems Ltd.
-
Saab AB
-
Textron Inc.
-
The Boeing Company
-
Israel Aerospace Industries Ltd.
-
Kongsberg Gruppen ASA
-
QinetiQ Group plc
-
Rocket Lab USA, Inc.
-
Hanwha Aerospace Co., Ltd.
Digital Battlefield Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 66.20 Billion |
| Market Size by 2035 | USD 309.80 Billion |
| CAGR | CAGR of 16.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Component (Hardware, Software, and Services) • by Technology (Artificial Intelligence, Digital Twin Simulation, Big Data Analytics, 3D Printing, and Others) • by Platform (Land, Naval, Airborne, and Space) • by Application (Command & Control Systems, ISR, Cyber Warfare, and Warfare Platforms) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, Airbus SE, AeroVironment, Inc., Elbit Systems Ltd., General Dynamics Corporation, L3Harris Technologies, Inc., Leonardo S.p.A., Rafael Advanced Defense Systems Ltd., Saab AB, Textron Inc., The Boeing Company, Israel Aerospace Industries Ltd., Kongsberg Gruppen ASA, QinetiQ Group plc, Rocket Lab USA, Inc., Hanwha Aerospace Co., Ltd. |
Frequently Asked Questions
Key players include Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, L3Harris Technologies, Inc., and Elbit Systems Ltd., among other global defense contractors.
Continued expansion of proliferated low-Earth-orbit satellite constellations for missile warning and tracking, along with continued integration of AI-enabled decision-support systems, represent the primary opportunities.
Growth is primarily driven by escalating geopolitical tensions and the urgent military requirement for persistent, real-time situational awareness combined with growing importance of cyber warfare capability.
By Component, Hardware dominated the market with approximately 52.60% share in 2025, reflecting the foundational role of sensors, communication equipment, and computing infrastructure across digital battlefield applications.
North America dominated the market with approximately 39.20% share in 2025, supported by massive U.S. defense budgets dedicated to modernizing airborne and space-based platforms.
