
High Density Polyethylene (HDPE) Bottles Market Report Scope & Overview:
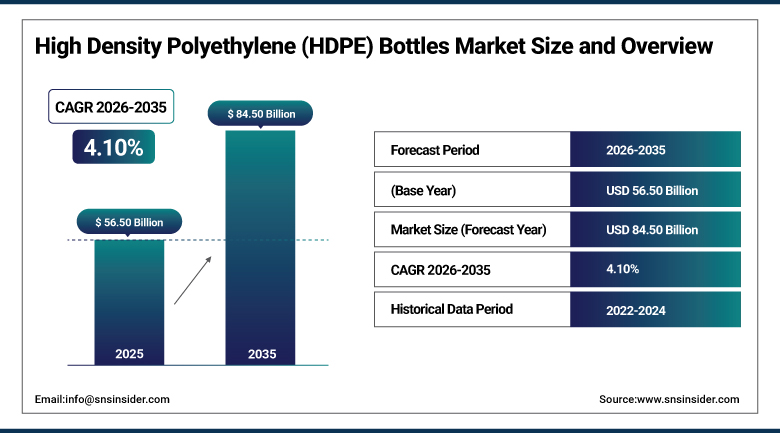
The High Density Polyethylene (HDPE) Bottles Market was valued at USD 56.50 Billion in 2025 and is expected to reach USD 84.50 Billion by 2035, growing at a CAGR of 4.10% from 2026–2035.
HDPE bottles are the workhorse of rigid plastic packaging, holding everything from milk and laundry detergent to shampoo and prescription pills, chosen because the resin is tough, chemically resistant, and cheap enough to mold at enormous scale without sacrificing the moisture barrier a bottle needs to protect what's inside. It's one of the most widely recycled plastics in the world, which has made it the default choice as brand owners face growing pressure to reduce virgin plastic use without abandoning rigid packaging altogether. E-commerce growth, expanding pharmaceutical logistics, and rising packaged goods consumption across emerging markets have all been pushing demand for exactly the kind of secure, lightweight, protective container HDPE bottles were built to be.
Berry Global launched a range of reusable bottles made entirely from post-consumer recycled HDPE for Bio-D, a B Corp-certified cleaning brand, blow molding 33-ounce laundry detergent and fabric conditioner bottles built from what was, until recently, someone else's waste plastic. Bio-D's sustainability manager framed the choice directly: a fully PCR reusable bottle beats even a supposedly greener pouch alternative, since the plastic doing the job was already out there in the world rather than freshly extracted from the ground.
To Get more information High Density Polyethylene (HDPE) Bottles Market - Request Free Sample Report
High Density Polyethylene (HDPE) Bottles Market Trends
-
Post-consumer recycled HDPE content continues expanding across food-grade and personal care applications, as brand owners chase credible sustainability commitments and increasingly binding recycled-content mandates in multiple jurisdictions.
-
Lightweighting continues advancing through improved blow molding technology, letting manufacturers reduce material use per bottle without compromising the structural strength and barrier protection HDPE is valued for.
-
Reusable, refillable bottle formats are gaining genuine commercial traction beyond pilot programs, particularly in household and personal care categories where brands increasingly offer 100% PCR bottles designed for repeated use.
-
E-commerce growth continues reinforcing demand for tamper-evident, shipping-durable HDPE packaging that can survive parcel handling and warehouse logistics better than more fragile alternative materials.
-
Manufacturers continue investing in advanced recycling infrastructure to secure reliable, food-grade recycled resin supply, since demand for recycled HDPE now regularly outpaces the volume collection systems can reliably deliver.
U.S. High Density Polyethylene (HDPE) Bottles Market Outlook
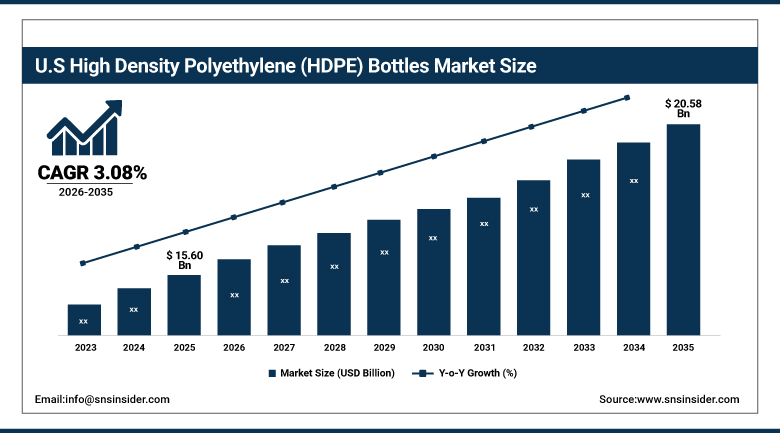
The U.S. High Density Polyethylene (HDPE) Bottles Market was valued at approximately USD 15.60 Billion in 2025 and is expected to reach approximately USD 20.58 Billion by 2035, growing at a CAGR of approximately 3.08%.
Demand in the United States is anchored by a deep concentration of pharmaceutical manufacturers alongside a large food and beverage, household chemical, and personal care manufacturing base that has relied on HDPE bottles for decades. Domestic converters continue investing in expanded recycling capacity to secure reliable post-consumer resin supply, since demand for recycled content now regularly exceeds what current collection infrastructure can consistently deliver at food-grade or pharmaceutical purity. A handful of long-established American and multinational packaging companies with deep pharmaceutical customer relationships continue anchoring the domestic supply base, giving the country a level of manufacturing depth and regulatory compliance expertise that newer entrants find genuinely difficult to replicate quickly.
Graham Packaging, a York, Pennsylvania-based bottle manufacturer, signed a multi-year contract in the first quarter of 2025 to supply plastic water bottles to Nestlé, extending its role as a key packaging partner for one of the world's largest beverage companies. The deal reflects how much of the U.S. HDPE bottle industry's growth still runs through a small number of long-term supply relationships with major consumer brands, rather than through the kind of fragmented, spot-market purchasing that defines less consolidated packaging categories.
High Density Polyethylene (HDPE) Bottles Market Segment Analysis
-
By Resin Source, the Virgin HDPE segment dominated the High Density Polyethylene (HDPE) Bottles Market with approximately 68.00% share in 2025, while the Recycled HDPE segment is the fastest growing with a CAGR of approximately 5.60%.
-
By Bottle Capacity, the 101–500 ml segment dominated the High Density Polyethylene (HDPE) Bottles Market with approximately 45.00% share in 2025, while the Less than 30 ml segment is the fastest growing with a CAGR of approximately 4.50%.
-
By Cap/Closure Type, the Screw Closures segment dominated the High Density Polyethylene (HDPE) Bottles Market with approximately 48.60% share in 2025, while the Others segment is the fastest growing with a CAGR of approximately 4.80%.
-
By End-Use Industry, the Pharmaceutical & Healthcare segment dominated the High Density Polyethylene (HDPE) Bottles Market with approximately 30.00% share in 2025, while the Household & Homecare segment is the fastest growing with a CAGR of approximately 5.90%.
By Resin Source, virgin HDPE dominates, recycled HDPE grows fastest
Virgin HDPE held the large majority of the resin-source segment in 2025, remaining the default choice for applications requiring guaranteed, consistent material purity, particularly pharmaceutical and food-contact packaging where regulatory approval processes still favor well-characterized virgin resin over blended recycled feedstock. Its predictable mechanical properties and broad regulatory acceptance across nearly every jurisdiction keep virgin HDPE the practical foundation the entire bottle industry is still built around, even as recycled content adoption accelerates elsewhere in the mix. Established, decades-long supply relationships between resin producers and bottle manufacturers further reinforce virgin HDPE's continued dominance across the majority of production volume worldwide.
Recycled HDPE is growing fastest as global regulatory mandates increasingly require recycled content integration across multiple packaging categories, pushing brand owners and manufacturers to secure reliable post-consumer resin supply well ahead of binding compliance deadlines. Building circular economy infrastructure through localized recycling networks, along with developing food-grade recycled HDPE formulations that meet strict purity and safety requirements, represents one of the industry's most significant near-term investment priorities. That combination of regulatory pressure and genuine brand-owner sustainability commitment is pulling recycled HDPE's growth well ahead of the broader, virgin-resin-dominated material mix across nearly every end-use category.
By Bottle Capacity, 101–500 ml dominates, less than 30 ml grows fastest
Bottles in the 101 to 500 milliliter range held the largest share of the capacity segment in 2025, matching the standard household, personal care, and pharmaceutical packaging sizes most commonly specified across the industry's largest end-use categories. That broad compatibility with typical consumer purchase quantities, from a standard shampoo bottle to a month's supply of tablets, keeps this the default capacity range across the majority of HDPE bottle production. Established filling line equipment across the industry is largely calibrated around this capacity range, further reinforcing its continued dominance as manufacturers standardize equipment investment around the most common format.
Bottles under 30 milliliters are growing fastest as single-serve, travel-size, and sample packaging formats continue expanding across personal care and pharmaceutical applications where portability and portion control both matter increasingly to consumers. Rising demand for trial-size and travel-friendly packaging, particularly in personal care and over-the-counter healthcare categories, continues reinforcing this above-average growth trajectory. Growing e-commerce distribution of smaller, more shipping-efficient package formats is adding further momentum to this capacity category's accelerating growth relative to the broader, mid-range-dominated capacity mix.
By Cap/Closure Type, screw closures dominates, others grows fastest
Screw caps accounted for the biggest market share within the cap and closure category in 2025, due to their high effectiveness of providing sealing performance and being versatile across virtually all uses for HDPE bottles such as consumer goods or pharmaceuticals. The reliability of sealing and simple manufacturing process ensure screw closures' continued dominance in the cap and closure market, which gives consumers and regulators certainty about the quality and integrity of the product from the moment of manufacture to the delivery point.
Child-resistant, tamper-proof closures, as well as other closures with dispensing capabilities, are the fastest-growing segments of the cap and closure market, due to the growing needs of the pharmaceutical and household chemicals markets in special capabilities beyond sealing performance. More regulations regarding child safety and tamper-proof seals in a number of product categories ensure the further increase in the demand for such specialized closures. Manufacturers with capability to produce such closure types can benefit from the above average growth trend.
By End-Use Industry, pharmaceutical & healthcare dominates, household & homecare grows fastest
Pharmaceutical and healthcare accounted for the largest end-use share in 2025, reflecting the rising use of plastic containers in pharmaceutical packaging alongside the sector's strict quality and traceability requirements that keep demand consistent regardless of broader economic conditions. Growing global healthcare spending and expanding pharmaceutical manufacturing capacity, particularly across emerging markets building out domestic production capability, continue reinforcing this application's dominant position within the broader HDPE bottle market.
Household and homecare is the fastest-growing end-use industry as growth in household and personal care products worldwide continues expanding, with rising demand for cleaning products, laundry detergent, and other homecare formulations that depend heavily on HDPE bottle packaging. Expanding reusable and refillable bottle programs across major household brands, offering up to 100% post-consumer recycled content, are reinforcing this above-average growth trajectory as sustainability-focused product lines continue gaining shelf space across major retailers worldwide.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.20% |
|
Europe |
Germany |
24.60% |
|
Asia Pacific |
China |
38.40% |
|
Latin America |
Brazil |
35.30% |
|
Middle East & Africa |
Saudi Arabia |
29.80% |
North America High Density Polyethylene (HDPE) Bottles Market Insights
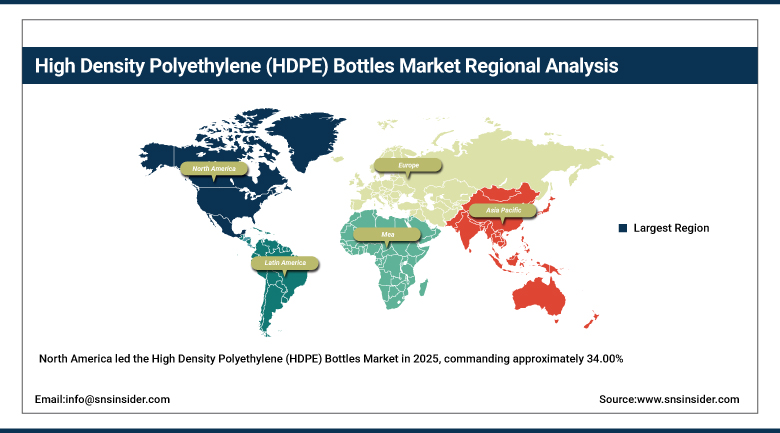
North America led the High Density Polyethylene (HDPE) Bottles Market in 2025, commanding approximately 34.00% of overall global market revenue, anchored by the United States' deep concentration of pharmaceutical manufacturers and a large, established food and beverage, household chemical, and personal care manufacturing base. That combination of pharmaceutical industry depth and consumer goods manufacturing scale gives the region a level of demand diversity that keeps HDPE bottle production consistently high regardless of which specific end-use category is currently accelerating fastest. Continued investment in domestic recycling infrastructure keeps reinforcing this leading position as manufacturers work to secure reliable recycled resin supply closer to their largest customer base.
Canada contributes a meaningful share through its own pharmaceutical and consumer goods manufacturing sectors, while Mexico's market continues expanding alongside growing nearshoring-driven manufacturing investment tied to broader North American supply chain integration. Cross-border supply relationships tie much of North American demand together, with major bottle manufacturers typically serving all three markets through shared production networks and long-established distribution infrastructure spanning the continent.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific High Density Polyethylene (HDPE) Bottles Market Insights
APAC is anticipated to be the fastest-growing regional market through 2035, due to the fast-growing manufacturing of packaged foods and beverages, increasing pharmaceuticals capacity and higher consumption of household and personal care packaging products across the biggest and fastest urbanizing markets of the region. Manufacturing capacity expansion in numerous Asian countries, supported by the governments, continues to fuel the growth at an accelerated rate, with the East APAC market expected to grow even faster due to increased packaging consumption associated with the development of organized retail and manufacturing industries.
The huge consumer goods and pharmaceutical manufacturing base in China ensures the region has a strong demand base, while India sees a lot of investments made into HDPE bottle capacity, due to the developing organized retail and healthcare industries there. Japan and South Korea are more mature markets, having well-established manufacturing standards, while the Southeast APAC markets follow the same urbanization-led growth pattern.
Europe High Density Polyethylene (HDPE) Bottles Market Insights
Europe represents a mature, sustainability-focused HDPE bottles market, shaped by ambitious recycled-content commitments from major producers and comprehensive EU packaging waste regulation targeting single-use plastic categories across nearly every industry. Germany anchors regional demand, home to a large pharmaceutical and consumer goods manufacturing base and several major bottle manufacturers investing heavily in advanced recycling infrastructure to meet expanding regulatory recycled-content requirements.
France, Italy, and the United Kingdom contribute meaningful volume as well, each with substantial food, personal care, and household chemical manufacturing sectors adapting to tightening EU sustainability requirements across their packaging supply chains. Industry-wide investment in advanced recycling technologies, including chemical recycling and improved sorting systems, continues reinforcing genuine circularity across the region's HDPE bottle supply chain more directly than in most other global markets.
MEA & Latin America High Density Polyethylene (HDPE) Bottles Market Insights
The Middle East and Africa represent a smaller but strategically developing HDPE bottles market, with Saudi Arabia driving demand through substantial petrochemical production capacity and expanding food processing and pharmaceutical retail investment tied to the country's broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader consumer goods manufacturing and organized retail infrastructure development across neighboring markets.
Latin America is a growing market led by Brazil, where expanding food processing, pharmaceutical, and household chemical manufacturing continue driving demand for cost-efficient, durable HDPE bottle packaging. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing manufacturing sectors serving both domestic consumption and export-oriented consumer goods markets across the broader region.
Market Dynamics
Growth Drivers: E-commerce protective packaging demand and pharmaceutical logistics growth fueling adoption
Rising e-commerce adoption is one of the clearest forces behind rising HDPE bottles demand, as expanding online retail continues fueling demand for secure, lightweight packaging solutions capable of surviving parcel handling and warehouse logistics better than more fragile alternative materials. That structural shift toward direct-to-consumer shipping continues reshaping packaging specification priorities across food, personal care, and household chemical categories that increasingly move through e-commerce channels rather than exclusively through traditional retail distribution.
Increasing food and beverage consumption in emerging economies, combined with rising pharmaceutical logistics volume, adds a second major driver, as expanding packaged goods consumption and healthcare infrastructure investment across developing markets continue driving sustained demand for protective, moisture-resistant bottle packaging. Growing use of plastic containers in pharmaceutical packaging specifically continues reinforcing this demand base as global healthcare spending and drug manufacturing capacity both continue expanding.
Restraints: Raw material price volatility and tightening recycled-content mandates limiting margin stability
Fluctuating polyethylene resin prices add real cost unpredictability for manufacturers, since HDPE bottle producers remain exposed to broader petrochemical commodity market swings that directly affect production costs and, ultimately, project budgets for brand owner customers across every end-use category. Manufacturers without long-term resin supply contracts are particularly exposed to these swings, which can compress margins even when finished-bottle demand remains steady across the broader market.
Tightening global regulatory mandates requiring recycled content integration add a further restraint, as manufacturers face genuine compliance costs and supply chain complexity securing reliable, food-grade recycled HDPE resin that meets both regulatory requirements and brand owner quality expectations simultaneously. That compliance burden falls disproportionately on smaller manufacturers without dedicated recycling infrastructure investment capability built into their operations.
Opportunities: Circular economy infrastructure and food-grade recycled formulation development opening new growth avenues
The development of circular economy infrastructure through regionalized recycling channels is a real strategy by which manufacturers can achieve premium revenue streams in response to the increasing demand by brand owners for sustainability commitments in the face of impending recycled content regulations in several key markets. Manufacturers that develop regionalized recycling infrastructure will find themselves well-positioned to generate disproportionate growth as a result of the increasing mandates and rising focus on traceability among brand owners.
The creation of food grade recycled HDPE formulations that meet the stringent purity requirements while addressing the demands of premium packaging is another significant opportunity, given the continued growth of demand for true food safe recycled materials relative to available supply. Manufacturers that are able to launch these formulations will find themselves well-positioned to capitalize on premium revenue streams from brand owners looking to make credible sustainability commitments.
Recent Developments:
-
Q2 2024: Berry Global opened a new plastic bottle manufacturing facility in India dedicated to producing bottles for the beverage and personal care sectors, expanding its Asia-Pacific footprint.
-
2025: Berry Global released its 2024 Sustainability Report, detailing progress under its Impact 2025 strategy toward a circular, net-zero packaging economy.
-
2025: ALPLA continued expanding its global recycling infrastructure toward its Ellen MacArthur Foundation-aligned targets of 100% recyclable packaging and 25% average recycled content, backed by roughly €50 million in recycling investment.
-
Q2 2025: Berry Global appointed a new CEO to lead its plastic bottle division, aiming to drive innovation and growth across its packaging business.
High Density Polyethylene (HDPE) Bottles Market Key Players
-
Amcor plc
-
Berry Global Group Inc.
-
ALPLA Werke Alwin Lehner GmbH & Co KG
-
Gerresheimer AG
-
Plastipak Holdings Inc.
-
Sonoco Products Company
-
Berk Enterprises (Berk Company LLC)
-
CL Smith Company
-
RPC Group Plc
-
Graham Packaging Company
-
Nampak Limited
-
Silgan Holdings Inc.
-
Comar, LLC
-
Alpha Packaging, Inc.
-
Consolidated Container Company LLC
-
O.Berk Company, LLC
-
Rutland Plastics Ltd.
-
UFP Technologies, Inc.
-
Weener Plastics Holding B.V.
-
AptarGroup, Inc.
High Density Polyethylene (HDPE) Bottles Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 56.50 Billion |
| Market Size by 2035 | USD 84.50 Billion |
| CAGR | CAGR of 4.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Resin Source (Virgin HDPE, Recycled HDPE) • by Bottle Capacity (Less than 30 ml, 31–100 ml, 101–500 ml, 501 ml–1 Liter, Above 1 Liter) • by Cap/Closure Type (Screw Closures, Snap Closures, Others) • by End-Use Industry (Pharmaceutical & Healthcare, Food & Beverages, Household & Homecare, Personal Care & Cosmetics, Industrial Chemicals, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Amcor plc, Berry Global Group Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Gerresheimer AG, Plastipak Holdings Inc., Sonoco Products Company, Berk Enterprises (Berk Company LLC), CL Smith Company, RPC Group Plc, Graham Packaging Company, Nampak Limited, Silgan Holdings Inc., Comar, LLC, Alpha Packaging, Inc., Consolidated Container Company LLC, O.Berk Company, LLC, Rutland Plastics Ltd., UFP Technologies, Inc., Weener Plastics Holding B.V., AptarGroup, Inc. |
Frequently Asked Questions
Key players in the High Density Polyethylene (HDPE) Bottles Market include Amcor plc, Berry Global Group Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Gerresheimer AG, and Plastipak Holdings Inc., among others.
Key opportunities in the High Density Polyethylene (HDPE) Bottles Market include building circular economy infrastructure through localized recycling networks and developing food-grade recycled HDPE formulations that comply with premium packaging regulations.
The market is driven by rising e-commerce adoption fueling demand for secure, lightweight packaging, combined with increasing food and beverage consumption and pharmaceutical logistics in emerging economies.
The Virgin HDPE segment dominated the High Density Polyethylene (HDPE) Bottles Market, accounting for approximately 68.00% market share.
The North America region dominated the High Density Polyethylene (HDPE) Bottles Market in 2025 with approximately 34.00% share, driven by a deep concentration of pharmaceutical manufacturers and a large consumer goods manufacturing base.
